

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Crop Protection (Agrochemicals) Market — Strategic Briefing for 2026 Decisions
As companies prepare strategy for 2026, the crop protection market is evolving under the combined pressure of raw-material volatility, regulatory reshaping, and a clear, sustained demand trajectory. PW Consulting’s new market study synthesizes historical performance (2020–2025), a detailed 2026–2032 forecast, and scenario-based strategic guidance designed to support executive decisions this year. In brief: the global market is on a steady expansion path (compound annual growth ~5.2%), rising from roughly USD 52 billion in 2020 to nearly USD 70 billion by the 2025 base year and projecting to exceed USD 100 billion late in the next planning cycle. What follows is an executive-oriented preview of the study’s practical value and how decision-makers should use it to shape 2026 priorities.
Crop Protection (Agrochemicals) Market
Why this study matters for 2026
-
Actionable foresight: We quantify near-term revenue and cost levers and translate those into tactical actions for procurement, pricing, and portfolio optimization.
Crop Protection (Agrochemicals) Market -
Risk-aware planning: The report maps supply-chain pinch points and regulatory shock scenarios so you can prioritize hedges and contingency investments now — not after disruption arrives.
Crop Protection (Agrochemicals) Market -
Competitive playbooks: Profiles and scenario implications for the largest players give commercial and R&D teams a tactical edge when negotiating partners, licensing, or acquisition targets.
-
Capital allocation clarity: Forward-looking scenario economics allow CFOs and strategy teams to test ROI for new modes of action, biologicals, and formulation upgrades under multiple commodity- and regulatory-stress cases.
Market trajectory and what it implies for 2026 choices
The market’s CAGR of approximately 5.2% reflects a mix of steady acreage-driven demand, intensifying adoption of integrated pest management solutions, and growing but uneven uptake of biologicals and biorationals. The study’s baseline projects the global market moving from the mid-2025 level (~USD 70 billion) to a north-of-USD 100 billion market by the end of the forecast horizon — a compelling absolute growth opportunity, but one that conceals pronounced margin and supply divergence by product type and geography.
For executives, the implication is straightforward: volume growth alone will not guarantee margin expansion. 2026 strategy should therefore combine modest top-line growth ambitions with decisive moves to protect margins — through raw-material contracts, formulation rationalization, and prioritizing higher-value differentiated solutions.
What the report contains (practical, decision-ready modules)
-
Integrated market sizing and forecast model — scenario-enabled across base, upside, and stress cases with sensitivity levers for key inputs (commodity feedstocks, regulatory delistings, and technology adoption curves).
-
Supply-chain and input-cost matrix — supplier concentration maps, lead-time analysis, and stress-tested price-impact simulations to inform procurement and hedging for 2026 budgeting.
-
Regulatory-impact playbook — a prioritized list of jurisdictions where regulatory action will disproportionately affect product viability and timelines for compliance or exit options.
-
Competitive strategic dossiers — concise, comparative profiles of the sector’s largest firms (R&D focus, pipeline highlights, manufacturing footprint, and likely M&A behavior), with implications for partnership or defensive strategies.
-
Commercial go-to-market guidance — channel optimization, digital-sell-through options for seed and biological adjacencies, and pricing strategies calibrated to elasticities exposed by our demand model.
-
M&A and alliance scoring tool — prioritizes targets by technology, geography, and supply resilience, supplying a short-list and an indicative valuation framework for 2026 negotiation planning.
-
Product portfolio optimization workbook — a pragmatic triage framework for discontinuing, retaining, or investing in actives/formulations aligned to corporate risk tolerance and margin targets.
Competitive landscape — how incumbents are repositioning
The market remains concentrated: roughly three global players collectively account for the majority share, and the next tier elevates overall concentration further. That structure is producing two clear strategic responses among incumbents.
-
Defensification and efficiency: Large multinational crop protection groups are actively streamlining portfolios, consolidating manufacturing footprints, and trimming lower-margin products to protect margins and accelerate R&D investment into new modes of action and biologicals.
-
Vertical and capability reinvestment: Several leading players are strengthening capabilities in biologicals, formulations, and seed-trait integration — differentiating through platform capabilities rather than relying solely on legacy chemistries.
Firm-level implications (executive summary):
-
Bayer CropScience — continuing to rationalize non-core actives and streamline production and R&D footprints. Expect further portfolio outsourcing and targeted investments in novel MOAs and biologicals as the firm reallocates capital toward higher-return programs.
-
BASF SE — reinforcing integrated agricultural solutions and actively reacting to feedstock-cost pressure through pricing and commercial discipline. Their moves on pricing and raw-material management are a bellwether for commodity-driven margin stress across the value chain.
-
Syngenta Group — leveraging strength in seed-treatment and biological solutions to offset pressure on commodity actives; a likely acquirer/partner for firms with complementary biological assets or digital agronomy capabilities.
-
Corteva Agriscience — integrating traits and protection solutions while managing feedstock and export-control exposures; their financial calls signal sensitivity to input-cost shocks affecting active-ingredient pricing.
-
UPL Limited — pursuing sustainability-angled formulations and differentiated supply solutions, positioning as a low-cost but innovation-focused alternative for select markets.
-
FMC Corporation — focusing on biorationals and insecticide/fungicide innovation, serving specialty segments and higher-margin niches where rapid adoption of new chemistries is possible.
Recent industry signals you cannot ignore in 2026 planning
-
Raw-material shocks have immediate pass-through consequences. Recent supplier price moves and feedstock disruptions demonstrate that logistics and petrochemical pressures materially affect intermediate and active-ingredient costs, and companies should assume periodic cost shocks when stress-testing 2026 P&Ls.
-
Regulatory consolidation and portfolio pruning are accelerating among majors. The trend toward outsourcing and plant rationalization is structural — firms are reallocating to protect R&D pipelines and margins, which will reshape competitive positioning in select active classes.
-
Export-controls and regional supply restrictions have localized effects. Shifts in export policy and feedstock availability are raising the effective cost and lead times for certain actives; firms with diversified manufacturing and flexible sourcing will gain a sustainable advantage.
How to use this research in 2026: decision steps
-
Procurement: Establish tiered supply agreements and negotiate clauses that mitigate feedstock price spikes for the next 12–24 months. Use our supplier-risk heat map to prioritize backup sourcing.
-
Portfolio: Execute a rapid portfolio triage using our investment-priority framework — accelerate high-margin differentiated products and biologicals; divest or partner on lower-return legacy actives.
-
R&D: Reallocate a portion of incremental R&D spend to biologicals and formulation platforms that reduce raw-material intensity and regulatory exposure.
-
Commercial: Reweight channel mix toward more predictable, value-accretive routes-to-market and adjust pricing models to reflect input-cost pass-through realities.
-
M&A: Use the report’s target-screening to identify acquisition or alliance candidates that address supply, capability, or geographic gaps.
What we intentionally withhold here — and why
This briefing demonstrates the actionable intelligence and strategic scaffolding contained in the full PW Consulting study while preserving the granular segment-level economics and company-specific forecast details that deliver commercial advantage. The full report contains detailed region- and application-level splits, product-by-product margin tables, proprietary demand elasticities, and a live modeling workbook — elements we reserve for full-report access to protect client value and proprietary methodology.
Next steps
If your 2026 plan requires defensible choices on procurement, R&D allocation, or M&A priorities, PW Consulting’s full Crop Protection market study provides the scenario models, supplier maps, and company dossiers you need to move from analysis to execution. Contact our team to schedule a tailored briefing; we will walk you through the model, stress-test your hypotheses, and co-develop the 90-day action plan aligned to your risk appetite.
For detailed analysis of this topic, please visit the official page: Crop Protection (Agrochemicals) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heavy Duty Conveyor Belts Market to Grow at 5.5% CAGR to 2032
By pmarketresearch, 2026-07-09
Heavy Duty Conveyor Belts Market — Strategic Outlook for 2026 Decision‑Making
Executive teaser: why this market matters to your 2026 agenda
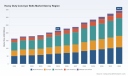
The heavy duty conveyor belts market is entering its most strategically consequential window in a decade. Between 2020 and the base year 2025, the global market expanded from approximately USD 163.2 Million to USD 215.0 Million; our modeling then projects growth to roughly USD 228.1 Million in 2026 and continues to a market size near USD 344.8 Million by 2032, underpinned by a compound annual growth rate (CAGR) of about 5.5% over the forecast horizon (2026–2032). For procurement leads, product strategists, and M&A teams, that trajectory signals persistent demand coupled with structural change — an opportunity to convert tactical wins this year into durable competitive advantage.
What this briefing delivers (and what it intentionally withholds)
- Confidence-building, data-driven context on market scale and pace (historical and forecast).
- Operationally actionable perspectives on supply chain risk, product innovation priorities, aftermarket economics, and regulatory drivers that will shape budgets and partner selection in 2026.
- A forward-looking competitive lens on the manufacturers and platform plays who will set price and service benchmarks.
- Strictly curated excerpts of analysis and implications — we deliberately withhold granular subsegment tables and exact regional/application splits to encourage direct access to the full dataset and dynamic models in the complete report.
Market structure and competitive dynamics — what you must internalize
Two structural features define the landscape for heavy duty conveyor belts in 2026: steady, mid-single-digit growth at the aggregate level, and a fragmented supplier base that keeps pricing and service quality highly local and relationship-driven. Measured concentration ratios (CR3 ≈ 24.6%; CR5 ≈ 26.2%) indicate that no small set of firms controls the majority of sales — an environment that both invites consolidation and rewards organizations that can orchestrate superior value chains, aftermarket offerings, or advanced materials.
Demand remains dominated by capital‑intensive sectors with long asset lifecycles. That creates a bifurcated buyer universe: large operators who prioritize total cost of ownership, reliability, and digital monitoring; and smaller integrators focused on price-to-performance and speed of delivery. Winning requires a tailored go-to-market that blends product engineering, field service excellence, and digital enablement.
Key strategic forces to prioritize in 2026
- Raw‑material and reinforcement dynamics: Steel‑cord reinforcement continues to be the backbone for heavy‑duty belts, with tensile specifications that range widely for mining and bulk handling applications. Securing upstream supply and engineering alternatives (e.g., performance fabrics, hybrid constructs) should be a procurement and R&D priority given price cyclicality and geopolitical exposure in steel markets.
- Regulatory and energy efficiency pressure: Energy standards and industry labeling regimes are accelerating development of low‑rolling‑resistance rubbers and higher‑efficiency belt systems. Firms that can credibly demonstrate energy savings will unlock both procurement preferences and longer service life economics.
- Labor and service cost optimization: Maintenance, splicing, and specialist field service labor are critical cost centers. Investments in training, advanced splicing technologies, and remote diagnostics reduce downtime and materially shift the lifetime cost equation.
- Digitalization and aftermarket monetization: Digital attachments and condition monitoring (sensors, IoT gateways, analytics) are transitioning from “nice-to-have” to procurement criteria. Mobile applications and on-site tools that simplify calculation, splicing guidance, and lifecycle tracking reduce operational friction and create recurring revenue opportunities.
Competitive snapshot — who to watch (and why)
Incumbent producers are moving beyond commodity supply into integrated product-service offerings. Below are concise strategic profiles of market movers whose plays will inform partner selection, benchmarking, and M&A screening in 2026:
- Continental AG (Germany) — ContiTech’s conveyor division pairs steel‑cord heavy‑duty belts with embedded digital monitoring solutions targeted at mining, construction, and bulk logistics. Their integrated sensor and service approach raises the bar on warranty and uptime guarantees; evaluate them when assessing end‑to‑end SLAs. ( continental.com )
- Fenner Dunlop Conveyor Belting (Netherlands / UK) — A broad portfolio of high‑strength steel‑cord and fabric belts, complemented by recent digital initiatives. Notably, in May 2026 Fenner Dunlop launched a mobile app—MyBelt—providing field crews and procurement teams with calculation tools, specifications, and splicing guidance. This exemplifies the platformization of aftermarket services. ( fennerdunlopamericas.com )
- Sempertrans Conveyor Belt Solutions GmbH (Austria) — Offers steel‑cord families with emphasis on energy savings and cover chemistries (flame retardant, heat‑resistant). Their product focus speaks to buyers balancing safety standards and thermal endurance in harsh installations. ( semperit.com )
- Habasit AG (Switzerland) — Known for durable rubber compounds for industrial material handling applications. Their strength lies in compound engineering and consistent regional service networks. ( habasit.com )
- Intralox L.L.C. (United States) — Focused on modular and heavy‑duty belt systems for processing environments; their modular approach appeals to processors seeking reduced downtime and rapid changeover. ( intralox.com )
Practical, tested actions for executives to take in 2026
- Procurement and supplier strategy: Reassess supplier panels with a double lens on raw‑material security and digital service capability. Introduce multi‑year contracts with indexed pricing and service KPIs; pilot vendor‑managed inventory in two high‑impact sites.
- R&D and product prioritization: Target low‑rolling‑resistance compounds and hybrid reinforcement architectures that lower system energy draw. Accelerate at least one product trial that couples belts with embedded sensing for predictive splicing alerts.
- Aftermarket and services monetization: Launch a tiered service catalogue (baseline warranty, performance guarantee, premium predictive package) and bundle mobile‑first tooling for field crews. Use telematics data to rationalize spare parts inventory and reduce mean time to repair.
- Operational cost control: Invest in technician upskilling and standardized splicing protocols; quantify expected downtime reduction and bake that into CapEx decision models for new installations.
- M&A and partnerships: With the market still fragmented, target acquisitions that bring either digital monitoring capabilities or regional aftermarket footprints. Prioritize bolt‑ons that accelerate time to first‑service revenue.
What the full PW Consulting report contains (select highlights)
- Comprehensive market sizing (historical 2020–2025; base year 2025; forecast 2026–2032) and scenario variants reflecting commodity price shocks and regulatory tightening.
- Segment profitability maps and total cost of ownership models by application class (note: full segment tables and exact regional splits are available only in the paid report).
- Supplier scorecards and an M&A playbook with valuation multipliers built for buyer synergies in manufacturing, digital services, and aftermarket.
- Operational playbooks: splicing and maintenance optimization, technician training curricula, and a pilot template for condition‑based monitoring deployment.
- Procurement RFP templates and risk mitigation checklists for steel cord and specialty rubber sourcing.
Implications for boardrooms planning 2026 budgets
Boards should view expenditures that align with digital monitoring, technician capability building, and secured upstream supply as investments that shift long‑term operating levers, not simple cost items. The projected growth path — from USD 215.0 Million in 2025 to an estimated USD 228.1 Million in 2026, and toward USD 344.8 Million by 2032 at a ~5.5% CAGR — makes a persuasive case to reallocate a modest share of CapEx into prototypes for energy‑efficient belts and into pilot deployments of condition monitoring. These initiatives shorten payback on service contracts and reduce the P&L volatility that stems from unplanned downtime and raw‑material swings.
Closing — why this is the right moment to act
The market’s steady growth, low concentration, and the rapid emergence of digital and material innovations create a rare window: incumbents with clear aftermarket and services strategies can convert growth into higher margin, while new entrants can capture niches by combining materials know‑how with plug‑and‑play digital services. PW Consulting’s full Heavy Duty Conveyor Belts Market report supplies the granular segmentation, scenario models, supplier benchmarking, and executable templates you need to convert 2026 investments into durable advantage. For an executive summary, model access, and to license the full dataset and operational toolkits, please consult the report landing page.
For detailed analysis of this topic, please visit the official page: Heavy Duty Conveyor Belts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheat Straw Pulp Market — Strategic Preview for 2026 Decision-Makers
As companies prepare strategic moves in 2026, wheat straw pulp has transitioned from a niche sustainability play to a mainstream industrial raw material. Our latest PW Consulting industry study—anchored on a 2025 base year and projecting through 2032—shows a market that has roughly doubled in scale since 2020 and is set to continue expanding at a mid-single-digit compound annual growth rate. For executives weighing investments, partnerships, and product-roadmap decisions next year, a disciplined read of the structural drivers and competitive dynamics in this report will materially change risk-return assumptions.
Wheat Straw Pulp Market
Why this market matters in 2026
-
Macro momentum. The global wheat straw pulp market has expanded from an early 2020 base to a multi-billion-dollar industry by 2025, and our forecast points to steady expansion through 2032 at a compounded rate of approximately 7.8% annually. That growth is not cyclical flaring; it reflects durable substitution trends across packaging, tissue, specialty paper, textiles and emerging biodegradable polymer feedstocks.
Wheat Straw Pulp Market -
Policy and corporate decarbonization align. Regulatory pressure on forestry-based fiber and corporate net‑zero commitments are making agricultural residues an economically and politically attractive feedstock. Wheat straw scores high on both lifecycle carbon and land-use neutrality compared to wood‑derived pulp, which reshapes buyer preferences from procurement committees to brand marketing teams.
Wheat Straw Pulp Market -
Value migration in the paper-fiber stack. Raw material cost volatility in wood pulp, combined with investments in non-wood pulping technologies and process efficiencies, are shifting product economics. Buyers increasingly view wheat-straw-derived fibers as a reliable substitute for specific grades, not merely an alternative for sustainability messaging.
Market trajectory and what the numbers signal
The market’s historical trajectory highlights two complementary dynamics: accelerating adoption and improving unit economics. Since 2020 the global market has grown meaningfully, and our 2026 opening-point scenario positions the industry on a rising curve toward the 2032 horizon. With an average growth rate approaching 7.8% over the forecast period, this implies that decisions made in 2026—about capacity expansion, offtake agreements, feedstock logistics, and technology licensing—will capture a significant portion of lifetime value for new entrants and incumbents alike.
Importantly, growth is not uniform across every value chain node. The incremental demand for wheat straw pulp is concentrated where substitution is most technically feasible and where buyers reward sustainability credentials with price premiums. The full report contains the granular regional and end-market decomposition, as well as price curve dynamics and unit-cost sensitivity models required to stress-test investment cases; those details are intentionally reserved for the complete deliverable.
Drivers and headwinds to prioritize in your 2026 planning
-
Supply-side dynamics. Wheat straw is a residual agricultural stream; its commercial availability is scale-dependent and sensitive to crop rotations, yield shifts and competing uses (e.g., animal bedding, soil amendment). Strategic sourcing and farmer engagement programs—rather than pure spot-market purchases—reduce feedstock risk and improve margin visibility.
-
Technology and product differentiation. Process choices (bleached vs. unbleached processes, yield-optimized pulping recipes, and post-pulp functionalization for molded products) create defensible product segmentation. Companies that pair process IP with downstream integration (tissue, molded fiber packaging, specialty papers) capture more value.
-
Logistics and regional fit. Economics are sensitive to haul distances and seasonal collection windows. Cities with integrated mill ecosystems and efficient transport corridors have a structural cost advantage—a factor that should inform greenfield planning and M&A target screening.
-
Market concentration and partnership opportunities. The market is moderately consolidated: leading suppliers account for a meaningful share of capacity, but there remains room for new large-scale entrants. This dynamic creates fertile ground for offtake partnerships, joint ventures with agricultural co-ops and white-label supply agreements with global paper converters.
-
Regulatory and certification tailwinds. Lifecycle certifications and compliance schemes are evolving rapidly. Early alignment with recognized sustainability standards reduces time-to-market for premium placements, while missteps can lead to commercial delays.
Competitive landscape — positioning and conflict zones
The ecosystem today includes a mix of legacy pulp producers adapting to non-wood feedstocks, vertically integrated tissue and packaging players, and new scale entrants focused specifically on straw mills. A brief, non-exhaustive orientation to representative players illustrates strategic archetypes you will confront when moving into or expanding within the space:
-
Regional scale specialty producers: Companies that started with refined non-wood pulps and have integrated downstream (e.g., household paper and molded products). Their strengths are established farmer networks and product formulations tuned for consumer goods.
-
Large-scale commodity manufacturers pivoting to straw: Major paper groups that add straw-based lines to existing mills, leveraging distribution reach and brand relationships to accelerate adoption in tissue and towel grades.
-
Greenfield, climate-first entrants: New-build projects that emphasize high throughput and low lifecycle carbon footprints, targeting premium segments like sustainable packaging and climate-positive tissue. Their playbook centers on financing for infrastructure and high-volume offtake contracts.
-
Regional non-wood pioneers: Companies that focus on localized mill deployments to serve adjacent markets, optimizing logistics and engaging deeply with agricultural suppliers for feedstock security.
These archetypes are embodied by incumbent names that have different risk profiles and strategic objectives—ranging from established tissue majors operating large bleached straw pulp lines to regional innovators developing climate-positive capacity. The competitive balance—top players holding a substantive share but with room for new challengers—underscores why 2026 is a pivotal timing window for partnerships, capacity commitments, and defensive contracts.
What the PW Consulting report delivers — practical assets for 2026 execution
Our study is designed as a decision-support toolkit for commercial, strategy, and M&A teams. The deliverables are practical, transaction-focused and ready to be operationalized into 2026 planning cycles:
-
Dynamic market model. Interactive base and scenario forecasts (base, conservative, upside) with sensitivity toggles for feedstock cost, pulp yields, capital intensity and price premia—built to be plugged into internal investment models.
-
Supply-demand matrix and regional sourcing map. A practical guide to where material can be aggregated at scale, with logistics-cost envelopes and seasonal availability windows (note: the granular regional and application-level split is available in the full dataset).
-
Commercial playbooks. Negotiation scripts and model contract clauses for long-term offtake, tolling agreements and feedstock procurement frameworks—tuned for both buyers and sellers.
-
Technology and process benchmarking. Comparative analysis of bleaching approaches, yield vs. brightness trade-offs, and decarbonization levers; plus a vendor short-list for turnkey plant solutions.
-
M&A and JV scorecards. A replicable scoring framework to rank targets on feedstock security, technical fit, regulatory exposure and integration complexity.
-
Regulatory & certification roadmap. Practical pathways to certification and EPD readiness to achieve premium positioning in buyer tenders.
-
Executive dashboard. KPIs that matter for 2026 execution—cash-on-cash payback ranges, breakeven deltas versus wood pulp, and operating metrics for ramp planning.
Recommended 90‑day agenda for C-suite and corporate development teams (teaser)
-
Align valuation assumptions. Use a conservative base-case for feedstock availability and run upside scenarios for premium product adoption. The full model in our report gives instant visibility into valuation sensitivity.
-
Secure pilot offtakes. Lock one or two strategic customers for blended supply to derisk early operations and demonstrate conversion economics to investors or lenders.
-
Design a feedstock partner network. Move beyond spot procurement—design an aggregator model with farmer incentives, seasonal storage, and price collars to stabilize costs.
-
Prioritize incremental quality improvements. Invest in process tweaks that unlock at-scale substitution in high-margin grades rather than trying to be everything to all customers at launch.
Closing perspective
Wheat straw pulp is no longer a curiosity; it is a commercially viable lever for companies targeting lower-carbon fibers at scale. The market’s growth trajectory and the evolving competitive map create concrete opportunities for new entrants and established players willing to make targeted 2026 commitments. However, the value is captured by teams that combine rigorous supply-chain design, process differentiation and a pragmatic commercial rollout.
PW Consulting’s full Wheat Straw Pulp Market report provides the complete, transaction-grade intelligence—regional and application-level breakdowns, price curves, contract templates and the detailed scenario models required to finalize a 2026 investment or partnership decision. For executives intent on making a decisive move next year, the full dataset and playbooks are available via our report portal.
For detailed analysis of this topic, please visit the official page: Wheat Straw Pulp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electromechanical Switch Market to Reach USD 8.18 Billion by 2032 (CAGR 4.9%)
By pmarketresearch, 2026-07-09
Electromechanical Switch Market 2026: Strategic Imperatives for Decision‑Makers
At PW Consulting, our latest Electromechanical Switch Market study frames the commercial reality that purchasing, R&D, and M&A teams will confront in 2026. Built on a base year of 2025 with a five‑year historical window (2020–2025) and a forward view to 2032, the analysis synthesizes macro momentum — the market moved from approximately USD 4.61 billion in 2020 to USD 5.85 billion in 2025 — and projects continued expansion through the forecast horizon. Under our central forecast the market grows at a compound annual growth rate (CAGR) of 4.9% over 2026–2032, reaching roughly USD 8.18 billion by 2032. This trajectory masks important inflection points and competitive dynamics that will determine who captures durable value.
Electromechanical Switch Market
Why 2026 Is a Pivotal Year for Electromechanical Switch Strategy
-
Capital allocation cycles align: many OEMs and tier‑1 suppliers are finalizing 3–5 year development and procurement plans in 2026, making this year a natural decision point to commit to platform choices, long‑term supply contracts, and tooling investments.
Electromechanical Switch Market -
Technology and form‑factor pressures intensify: miniaturization, ingress protection (IP) requirements for harsh environments, and increased demand for tactile feedback in HMI are converging, shifting cost and performance trade‑offs for new product programs.
Electromechanical Switch Market -
Supply resilience moves from checkbox to boardroom priority: manufacturers who do not rework their sourcing and logistics strategies in 2026 face margin compression and slower time‑to‑market as raw material and component volatility persists.
What the PW Consulting Electromechanical Switch Report Delivers
This report is built as a practical playbook for corporate decision‑makers. We preserve proprietary granularity behind the paywall while surfacing the strategic levers executives need to act. Key deliverables include:
-
Holistic market sizing and validated time series (2020–2025) plus scenario‑based forecasts to 2032, allowing finance and strategy teams to stress‑test capex and revenue plans against downside and upside paths.
-
Demand‑driver mapping and use‑case archetypes that link macro trends (automation, electrification, consumer device cycles, healthcare device adoption) to switch design and procurement requirements.
-
Supply‑chain and cost‑to‑serve analysis covering tiered supplier models, critical raw‑material exposure, manufacturing footprints, and logistics sensitivity — presented as decision matrices for S&OP and procurement.
-
Competitive benchmarking and supplier scorecards with qualitative and quantitative metrics across reliability, IP rating capability, lead‑time performance, and engineering support — intentionally summarized in the public brief while deeper matrices and raw scores are accessible in the full report.
-
M&A and partnership playbooks that identify where bolt‑on acquisitions or co‑development agreements can accelerate entry into adjacent segments or strengthen IP in miniaturized and sealed switches.
-
Commercial tools: pricing sensitivity models, serviceable obtainable market (SOM) estimation templates, and GTM roadmaps for both OEMs and component suppliers to translate market forecasts into quarterly revenue targets.
Market Structure and Concentration: What the Numbers Mean
The electromechanical switch market shows moderate consolidation. Our concentration measures indicate that the three largest players account for just under half of industry revenues, while the top five raise that share into the mid‑50s percentile. Practically, this means:
-
There is room for scale advantages: larger suppliers can leverage global manufacturing footprints and distribution to defend margins, especially on industrial and harsh‑environment product lines.
-
Specialists and regional players still capture profitable niches: specialized tactile, ultra‑compact, or medical‑grade switches remain strategic targets for acquisition or partnership to fill portfolio gaps quickly.
Competitive Landscape: How to Read the Leaders
Understanding incumbent strengths helps buyers and investors identify partnership and disruption risks. Our qualitative read of core companies in the ecosystem follows.
-
Omron Corporation (Kyoto, Japan) — Deep OEM relationships in industrial automation and broad product breadth across tactile, rotary, limit and sealed switches. Their strength lies in systems integration and long‑standing automation credentials; watch for bundled automation solutions that lock in switch sourcing.
-
Honeywell International Inc. (Charlotte, NC, USA) — Known for durable limit switches and precision electromechanical components tailored to harsh industrial environments. Honeywell’s differentiator is engineered reliability and compliance expertise, making them a preferred supplier where safety and certification are decisive.
-
TE Connectivity Ltd. (Galway, Ireland) — Strong in ruggedized, IP‑rated switch formats (including M12 variants) and systems for industrial automation. TE’s global connectivity platform and channel depth make them a natural partner for programs seeking standardized, robust components.
-
Panasonic Corporation (Tokyo, Japan) — Competes on miniaturization and ultra‑compact tactile switches for consumer electronics and automotive infotainment. Their strength is scale in high‑volume consumer supply chains and cross‑domain productization.
-
C&K Components (Waltham, MA, USA) — Focused on high‑reliability tactile, toggle and pushbutton switches suitable for aerospace, medical and other demanding sectors. Niche specialization and qualification capabilities are their core assets.
-
NKK Switches (Kawasaki, Japan) — Positioned in illuminated and process‑sealed switches for industrial panels and machine control. Their strength is customization for operator interfaces and panel OEMs.
-
Eaton Corporation (Dublin, Ireland) — Emphasizes industrial and power management electromechanical switches with an emphasis on system safety and integration into electrical distribution equipment.
-
ALPS Alpine Co., Ltd. (Tokyo, Japan) — Specialist in tactile, rotary and encoder switches for automotive and consumer HMI, with a focus on ergonomic and integrated sensor solutions that support modern infotainment and instrument clusters.
Five Strategic Actions for 2026
-
Reprioritize product roadmaps to favor modular, serviceable designs. Modular switch platforms reduce NPI time and enable aftermarket upsell — critical as product lifecycles shorten in consumer and automotive segments.
-
Lock selective long‑term supply contracts with dual‑sourcing clauses. Secure capacity for critical subcomponents while maintaining alternative qualified suppliers to manage price and lead‑time shock risks.
-
Pursue targeted M&A or IP licensing to accelerate miniaturization and sealing capabilities. Acquiring niche specialists can be faster and less risky than sole in‑house development, especially where qualification cycles are long.
-
Invest in test and validation labs that mirror end‑customer environments. Reliability and ingress testing reduce field failures and can be monetized through co‑validated supplier programs to shorten OEM acceptance timelines.
-
Develop aftermarket and service propositions. As devices become more complex, field‑replaceable switch modules, extended warranties and “switch as a service” models can create recurring revenue streams and increase customer stickiness.
Risk Scenarios and Investment Triggers
We model three qualitative scenarios (conservative, base, aggressive). Key triggers that shift outcomes include supply‑chain shocks, accelerated electrification in transport, regulatory tightening on safety standards, and breakthrough material or actuation technologies. For investors and corporate planners, monitor these KPIs as early warning signals:
- Lead‑time variance and backorder ratios across major suppliers
- Rate of design wins tied to new EV platforms or industrial automation tenders
- Certification cycle lengths for new ingress/safety standards
- Price movements for commodity inputs used in contacts and housings
How to Use the Full PW Consulting Report
The public brief is intentionally selective: it demonstrates the analytical framing and strategic depth you receive from PW Consulting while withholding proprietary breakouts that are frequently the decisive input for commercial negotiations. The full report augments the overview presented here with:
- Segment‑level demand forecasts and unit economics by product family (available to subscribers).
- Regional and application maps that link buyer personas to procurement cycles and certification requirements.
- Interactive dashboards to run custom scenarios against your product portfolio and supply chain assumptions.
- Supplier scorecards with quantifiable metrics and due‑diligence appendices suitable for M&A screening.
For leadership teams preparing 2026 budgets and strategic plans, this full dataset is the difference between confident, executable decisions and uncomfortable, reactive bargaining in the face of changing demand and supplier dynamics.
Closing: The Strategic Value for 2026 Decisions
Decisions made in 2026 will compound across product roadmaps, supplier relationships, and customer commitments. The electromechanical switch market’s steady expansion — from about USD 4.61 billion in 2020 to USD 5.85 billion in 2025, with a projected CAGR of 4.9% through 2032 — provides tailwinds but also heightens competition for design wins and margin resilience. Executives who combine selective inorganic activity, disciplined supply‑chain design, and modular product architectures will turn this growth into durable profit pools. PW Consulting’s full Electromechanical Switch Market report equips leadership teams with the quantified scenarios, supplier diagnostics, and commercial tools needed to make those 2026 choices with confidence. To access the full set of segment breakouts, supplier matrices, and interactive modeling tools, please visit our report page or contact your PW Consulting advisor.
For detailed analysis of this topic, please visit the official page: Electromechanical Switch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 3D Optical Profiler Market to Reach USD 202.5M by 2032 at 5.48% CAGR
By pmarketresearch, 2026-07-09
3D Optical Profiler Market: Strategic Outlook for 2026 Decision‑Makers
As the lead industry analyst at PW Consulting, I present a concise, decision‑focused synthesis of our 3D Optical Profiler Market research that is explicitly designed to inform capital allocation, product strategy, and regulatory planning in 2026. The market reached an estimated USD 139.6 Million in the base year 2025 and—under the assumptions and modeling described in our full study—is projected to grow to approximately USD 202.5 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window. This briefing highlights the strategic implications of that trajectory without disclosing the detailed segment-by-segment intelligence reserved for the full report.
3D Optical Profiler Market
Why this market matters to executives in 2026
-
Consolidated, sustained growth. The 3D optical profiler market has expanded materially since 2020, accelerating investment into non‑contact, areal surface metrology solutions. The mid‑single‑digit CAGR we project through 2032 signals a market that is large enough to justify product roadmaps and GTM investments, yet dynamic enough that innovation and go‑to‑market discipline will substantially influence vendor and buyer outcomes.
3D Optical Profiler Market -
Regulatory and quality pressure is reshaping demand. Regulatory regimes—most notably tightened European medical device rules and established U.S. quality system requirements—are converting qualitative inspection routines into quantitative, traceable measurement programs. For device OEMs and medical device suppliers this is not an optional upgrade; surface metrology data has become a core component of design validation and post‑market surveillance dossiers.
3D Optical Profiler Market -
Technology-driven differentiation. Advances in interferometry, confocal techniques, and areal analysis software are increasing the value proposition of modern profilers beyond mere surface topography: more robust defect detection, automated reports for regulatory submissions, and integration with factory MES/quality stacks are now differentiating purchase decisions.
Demand drivers, risks and structural trends
-
Medical vertical acceleration. Our sector analysis identifies medical device applications—implantables, ophthalmic optics, and minimally invasive instruments—as among the most rapidly expanding end markets for 3D profilers. Heightened regulatory scrutiny plus OEM investment in fixation and surface treatments (e.g., to improve osseointegration) are creating durable measurement requirements. In practical terms, organizations preparing 2026 capital plans should expect sustained specification tightening and more frequent measurement audits as part of conformity assessments.
-
Semiconductor cycle sensitivity. Semiconductor metrology remains a foundational demand pillar. While long‑term secular needs for node‑level and packaging metrology persist, short and medium‑term spending is tied to wafer fab capex cycles. Procurement timelines that align profiler purchases with wafer‑fab upgrade cycles will capture value and reduce obsolescence risk.
-
Capital intensity and procurement cadence. Advanced 3D optical profilers are capital equipment with meaningful upfront cost and integration effort. Buyers must evaluate total cost of ownership across service models, calibration regimes, and lifecycle software updates. This is particularly relevant for centralized lab models versus distributed inspection strategies.
-
Concentration and competitive pressure. Market concentration is moderate: the top three vendors account for a meaningful share of revenues while the leading five consolidate most branded pedigree and service capabilities. This structure favors differentiated offerings (verticalized applications, compliance toolkits, and lifecycle services) and creates opportunities for niche players that can rapidly solve a regulatory or process pain point.
Competitive landscape — what buyers and investors need to know
-
Keyence Corporation (Japan): Renowned for pragmatic, application‑driven instrumentation, Keyence markets profiler series that emphasize throughput and ease of use for industrial and selected medical uses. Recent trade show demonstrations highlighted medical stent surface analysis—demonstrations that underline Keyence’s focus on translating device‑level use cases into sales momentum.
-
Bruker Corporation (United States): Bruker’s Contour series emphasizes surface finish verification and wear analysis for critical medical implants and ophthalmic devices. Their strengths are in combining precision hardware with metrology‑grade software analytics that serve validation and failure analysis workflows.
-
Zygo Corporation (United States): Zygo positions itself on standards compliance and nano‑scale accuracy, supporting micro‑ and nano‑characterization projects where traceability to ISO standards is a procurement requirement for regulated device manufacturers.
-
Sensofar Group (Spain): Sensofar’s platforms focus on areal measurement and industrial/biomedical applications. Sensofar is notable for integrating flexible optics and modular workflows that appeal to R&D labs and production test cells seeking a single‑platform approach.
-
Taylor Hobson (Ametek, United Kingdom): Taylor Hobson’s non‑contact profilometers are targeted at ultra‑precision form measurement for medical optics and high‑precision devices. The company’s legacy in form metrology and Ametek’s service footprint provide a compelling combination for high‑assurance buyers.
Collectively, these vendors illustrate the strategic choices facing buyers: buy broad, application‑focused platforms with strong service networks or procure specialized systems optimized for a single vertical’s regulatory and measurement challenges. Recent vendor activity—trade shows, product demos, and targeted application messaging—indicates that competition will increasingly center on software workflows, compliance documentation, and integration ease rather than raw hardware specs alone.
Pragmatic 2026 actions for three executive profiles
-
For CPOs and procurement leads: implement a two‑track acquisition plan. Track A addresses immediate compliance requirements (short‑list profilers that can generate regulatory‑grade reports and integrate into QMS). Track B secures modular capacity for higher throughput and future scalability. Build multi‑year service agreements into capital approvals to smooth lifecycle costs and secure software updates and calibration support.
-
For product and R&D heads at device OEMs: embed metrology earlier in the design cycle. Quantitative surface metrics should be part of design inputs, not an afterthought for verification. Early investment in an in‑house measurement capability can reduce iterative validation cycles and shorten time‑to‑market for regulatory submissions.
-
For investors and corporate development teams: monitor pockets of consolidation and verticalized value. The market’s concentration profile suggests acquisitive scale plays will continue—especially where a vendor can add strong service networks, domain‑specific analytics, or access to large OEM accounts. Target assets that plug capability gaps (e.g., software analysis suites, vertical application templates) rather than duplicating hardware lines.
Scenarios and sensitivity — how to use the forecast in planning
-
Baseline (our central case): CAGR 5.48% 2026–2032, with steady adoption across traditional industrial end markets and rising penetration in medical device manufacturing. This scenario assumes steady capital markets and no significant new regulatory shocks beyond current trajectories.
-
Upside: faster medical adoption. If device OEMs accelerate investments in surface metrology to comply with stricter post‑market surveillance and implantability criteria, the market could re‑rate higher—driven by more frequent instrument refresh cycles and bundled software services.
-
Downside: capex interruption. Prolonged semiconductor capex pauses or macroeconomic contractions could delay high‑value purchases, compressing near‑term growth and lengthening payback cycles for vendors and buyers alike.
What the full PW Consulting report delivers (operationally actionable)
-
Validated historical time series and a forward financial model calibrated to base year 2025 that supports scenario re‑runs for your internal planning.
-
Vendor profiles with capability mapping, service footprints, product roadmaps, and strategic positioning that allow buyers to build short lists aligned to their compliance and throughput needs.
-
Go‑to‑procurement checklists and integration playbooks: recommended RFx structures, calibration and acceptance test scripts, and software interoperability requirements for MES and QMS integration.
-
Regulatory impact analysis focused on medical device conformity requirements and a set of templates to translate those rules into inspection and reporting specifications.
-
Deal‑flow and M&A screening criteria for investors—highlighting capability annexes that materially increase vendor attractiveness (e.g., validated regulatory reporting modules, global service networks, and vertical application suites).
Concluding guidance — the strategic short list for 2026
Executives approaching 2026 should treat the 3D optical profiler market as a strategic enabler: for device OEMs it is a compliance and innovation lever; for industrial manufacturers it is a precision productivity tool; and for vendors and investors it is an adjacency that rewards focused productization and lifecycle services. Use the central forecast (CAGR 5.48% to 2032) as your planning baseline, overlay industry‑specific adoption curves for medical and semiconductor end markets, and prioritize procurement decisions that reduce technical debt and accelerate regulatory readiness.
For teams that require the segmented intelligence to operationalize these recommendations—including regional demand heat maps, sensor‑type economics, granular application shares, and downloadable vendor scorecards—our full report contains the proprietary datasets and templates necessary to convert market insight into executable 2026 plans. Contact PW Consulting to access the complete analysis and the accompanying modeling toolset.
For detailed analysis of this topic, please visit the official page: 3D Optical Profiler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Quartz Glass Market to Reach USD 2,216 Million by 2032 at 6.8% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-09
Quartz Glass Market — 2026 Strategic Primer
Executive snapshot
PW Consulting’s Quartz Glass Market study is designed for executives who must make capital, procurement and M&A decisions in 2026 with limited runway. The global quartz glass market stood at USD 1.42 billion in our 2025 base year and, under our central case, is projected to grow at a 6.8% CAGR through a seven-year forecast window (2026–2032), reaching approximately USD 2.22 billion by 2032. That steady, above-market industrial growth is being driven by a confluence of semiconductor scaling (including EUV and photomask demand), the continued rollout of power electronics for EVs and renewables, and incremental growth in optics, lighting and laboratory segments.
Quartz Glass Market
This primer highlights the report’s strategic value for decisions you must finalize in 2026: where to allocate capex, which suppliers to lock, how to hedge feedstock exposure, when to accelerate vertical integration, and which competitive moves will materially change your position over the next 12–24 months. The full report contains the granular segmentation, supplier scorecards and interactive financial models that underpin the recommendations summarized below; this article purposely illustrates the insights while omitting the detailed segment tables and raw vendor scores to guide you to the full deliverable.
Quartz Glass Market
Why this study matters for 2026 decisions
-
Timing is critical. Mid-decade demand surges for EUV-quality and large-format synthetic substrates have created pockets of lead-time risk for high-purity fused silica and precision components. Capital commitments made in 2026 will determine supply balances for the early 2030s.
Quartz Glass Market -
Complex quality differentiation. Not all quartz is equal: purity, defect density, dimensional tolerances and thermal performance drive customer value in semiconductor and photomask applications. Suppliers that can demonstrate EUV-grade consistency and advanced ovality or flatness tolerances capture premium contracts.
-
Supply-side signal: capacity investments and supplier awards. Recent announcements—in particular large-scale European capacity expansions and supplier recognitions from major OEMs—signal a market reshuffle where capacity and certified OEM relationships will be primary competitive moats.
-
Input-cost dynamics are manageable but shifting. North American feedstock showed mild downward movement in Q1 2026, while broader silicon dioxide indices show a slight upward trajectory into 2026 after inventory-driven declines in 2025. Procurement strategies should balance short-term price relief against an anticipated, gentle recovery.
-
Regulatory continuity lowers near-term trade risk. Quartz glass is listed under HS 70200010 and, as of the latest reviews, has not been subject to specific new import/export controls or environmental surcharges—removing one layer of policy uncertainty for cross-border sourcing and capacity allocation.
What the full report delivers — practical content for direct action
- Top-line market sizing and historical trend analysis (2020–2025) and a transparent forecast engine for 2026–2032 with scenario toggles for low/base/high demand outcomes.
- Demand-driver deep dives covering semiconductor process roadmaps (EUV, advanced nodes), photovoltaic manufacturing cycles, EV power electronics, optics and specialty lamp markets.
- Supply-chain mapping: feedstock sources, synthetic quartz routes, conversion bottlenecks, and a prioritized list of long‑lead, single‑source components.
- Supplier scorecards and vendor risk matrices assessing quality, capacity, geographic footprint, certification status and customer concentration.
- CapEx and margin sensitivity models allowing finance teams to stress-test expansions under differing price and demand curves.
- Scenario playbooks: contract procurement (spot vs. long-term), lean vs. resilience strategies, and M&A and JV frameworks tailored for OEMs, fabs, and component houses.
- Regulatory & raw-material appendix summarizing tariff status, feedstock price indices and environmental compliance considerations.
Note: this primer intentionally omits the granular regional and application splits and the detailed supplier scores contained in the full report. Those tables are often the actionable intelligence buyers and investors need to finalize negotiations and are therefore delivered in the paid research package.
Competitive landscape — strategic read of core players
The quartz glass supplier ecosystem blends legacy materials specialists, regional high-volume producers and precision component fabricators. No single firm dominates the market; leadership is built on a combination of purity capability, OEM certifications, scale of synthetic quartz production and proximity to demand hubs.
-
Tosoh Quartz Corporation (Tokyo) — A heritage materials player pivoting aggressively toward silica glass to capture demand from AI hardware, power electronics and RF systems. Recently recognized by a major OEM, Tosoh’s strategic alignment with chipmakers and broad product portfolio make it a prime partner for long-term supply agreements. Key decision factor: Tosoh’s ability to convert strategic intent into repeatable, certified EUV-grade deliveries.
-
Heraeus Quarzglas (Hanau) — Investing materially in Europe with new flame hydrolysis furnaces and expanded EUV-grade ingot capacity. Heraeus is also deploying AI-enabled quality control for defect detection—an advantage where microscopic defects carry outsized value. Key decision factor: validation timelines for the new capacity and consistency of EUV-grade output.
-
Technical Glass Products & Swift Glass (USA) — These fabricators specialize in finished components, labware and application-specific products with strengths in short-run customization and thermal/mechanical performance. They are natural partners for customers seeking agile supply with technical co-development.
-
Hubei Feilihua (China) — A large-volume manufacturer focused on semiconductor-grade fused quartz with strong cost-positioning. Their scale is a double-edged sword: attractive for volume sourcing but potentially constrained for ultra-high-purity, large-format substrates where specialized processes are required.
-
Specialist precision houses (QSIL, Raesch, Maruwa, MGS, Sintrex) — These firms excel at precision drawing, finishing and custom components. For OEMs requiring bespoke tube, rod, plate or machined parts, these suppliers are often decisive enablers of product differentiation.
Recent industry developments change the competitive calculus: European capacity additions shift some long-term bargaining power; product-line enhancements (improved ovality, tighter flatness tolerances) create new premium tiers; and supplier awards from marquee OEMs accelerate consolidation in the supply chains for high-end, high-purity segments.
Strategic priorities and playbook for 2026
-
Prioritize contract certifications for mission-critical grades. If your product roadmap depends on EUV-grade or large-format photomask substrates, negotiate multi-year supply-and-performance agreements with penalty-and-reward clauses tied to defect rates and delivery windows.
-
Hedge feedstock tactically. Take advantage of short-term relief in certain regions while establishing contingent supply contracts to protect against the modest rebound in silicon dioxide indices forecast for 2026.
-
Invest in upstream assurance. For OEMs and fabs, consider minority equity or joint-venture stakes with high-purity producers to secure allocation without full capex exposure.
-
Target precision fabricators for bolt-on M&A. Small-to-mid market precision component makers can be integrated to shorten lead times and protect IP in specialized optical or thermal components.
-
Implement AI-enabled QC in your incoming-inspection protocols. Suppliers deploying these tools have a demonstrable edge in detecting subsurface defects and improving yield—require transparency on defect-detection methodology as part of supplier selection.
-
Build flexible sourcing geographies. Even though tariffs and controls are not a near-term constraint, geographic diversification reduces concentration risk from single-region outages or capacity bottlenecks.
-
Embed sustainability and recycling clauses into procurement. Recycled quartz and closed-loop programs are emerging as differentiators for capital projects and can reduce long-term feedstock exposure.
Decision triggers and metrics to monitor in 2026
- Feedstock price indices (especially regional silicon dioxide trends).
- Vendor capacity announcements and furnace installations for EUV-grade and large-format ingots.
- Lead times for critical components (ingots, large plates, precision tubes) and trend lines versus booked backlog.
- Defect and yield metrics from pilot runs—especially for EUV-grade and photomask substrates.
- Customer backlog at major buyers in semiconductor and photovoltaic value chains.
How to use the full PW Consulting deliverable
If you are setting procurement budgets, designing a two‑year capex cadence or evaluating strategic acquisitions in 2026, the full Quartz Glass Market report provides the models and scored supplier universe to convert these strategic themes into executable decisions. The paid report includes downloadable scenario models you can plug into your board materials, a procurement negotiation playbook with contract language templates, and a prioritized M&A watchlist aligned to different corporate strategies (volume-scaling, premium-differentiation, or regional resilience).
We have intentionally sketched the strategic landscape and recommendations here while withholding the granular regional and application splits, per-supplier numerical scores and the full financial models. That granularity is the difference between a good negotiation and a market-winning agreement, and it is available in the full report package where you can access the underlying data, sensitivity tables and supplier scorecards.
For guidance tailored to your specific position—buyer, component manufacturer, or investor—contact PW Consulting’s Quartz Glass practice to arrange a workshop where we apply the model to your balance sheet, contract portfolio and technology roadmap.
For detailed analysis of this topic, please visit the official page: Quartz Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Broadcast & Cinema Cameras to Reach USD 3.27B by 2032 at 7.25% CAGR
By pmarketresearch, 2026-07-09
Digital Broadcast and Cinematography Cameras: Strategic Outlook for 2026 Decision-Makers
As media businesses, hardware OEMs, systems integrators, and investors plan for the next strategic cycle, understanding the topology of demand, supply-side pressure points, and technology inflection becomes a prerequisite for defensible decisions. PW Consulting’s latest market study on Digital Broadcast and Cinematography Cameras (base year 2025) synthesizes seven years of historic behavior and a near-term forecast horizon to 2032—delivering the contextual intelligence needed to prioritize capex, R&D, M&A, and channel strategies through 2026 and beyond.
Digital Broadcast and Cinematography Cameras Market
Executive snapshot
The market has shown a steady expansion across the 2020–2025 historical window and is projected to continue growing through our forecast period. Using 2025 as the reference point, the study applies a 7.25% compound annual growth rate (CAGR) across the forecast horizon. That steady, above-average growth reflects durable secular tailwinds: continued content production, higher-resolution capture requirements for premium streaming and live-event workflows, and the transition to IP-native studio architectures. Importantly, the market exhibits moderate concentration—neither a closed oligopoly nor a highly atomized commodity segment—creating room for both incumbents and well-capitalized challengers to shape outcomes.
Digital Broadcast and Cinematography Cameras Market
Why this study matters for 2026 decisions
-
Capital allocation under uncertainty: Our modeling reconciles multiple demand scenarios (base, accelerated, downside) and translates each into balanced investment roadmaps for manufacturers and content owners. The result is a short-list of timing-sensitive opportunities—upgrade cycles, SKU rationalization, and platform investments—that materially affect IRR timelines.
Digital Broadcast and Cinematography Cameras Market -
Supplier risk and resiliency: Component volatility—particularly for flash storage and precision glass—has compressed product development timelines and margins across the ecosystem. The study quantifies supplier exposure and presents mitigation options (dual-sourcing, inventory strategy, and design-level substitutions) that remain actionable in 2026 procurement cycles.
-
Product and channel playbooks: Our buyer-seller matrices identify where premium-spec cinema cameras, modular cinema platforms, and broadcast-oriented system cameras intersect with evolving customer preferences—live sports, streaming drama, immersive 3D, and cloud-based production. For channel leaders, we map the GTM approaches that yield the highest commercial leverage within each scenario.
Market dynamics and technology inflection points
The camera market is at the intersection of multiple structural shifts. Resolution and sensor performance continue to climb—driven by studios, streaming platforms, and advanced live-event productions—while transport and connectivity standards (e.g., IP-centric SMPTE flows and 100G Ethernet) accelerate system-level change. Simultaneously, supply-side noise has become a practical planning constraint:
-
Flash storage pricing and availability: Elevated demand from AI compute infrastructure has tightened the flash market. Our scenario analyses show that storage cost dynamics materially affect price/performance in high-resolution camera platforms, influencing both BOM costs and service economics for rental houses and broadcasters.
-
Lens glass and optics supply: Competitive pricing pressure from select Asian glass manufacturers is reshaping lens margins and has prompted some premium optics houses to reconsider vertical or partnership strategies to protect quality and lead times.
-
Regulatory and standards-driven feature sets: Emerging requirements—such as multi-sensor redundancy for immersive 3D capture and tighter interoperability for IP-native live production—drive incremental engineering scope and certification costs. OEMs that front-load compliance design will enjoy faster enterprise adoption.
Competitive landscape — who matters and why
The competitive map blends legacy broadcast champions with cinema-focused innovators and software-driven newcomers. Market concentration metrics indicate a landscape where a handful of leaders control material share, but an enlarged middle tier continues to win on specialization and price-performance.
-
Sony Corporation — Strong crosswalk between high-performance cinema sensors and live production systems; their product family spans live HDC systems to full-frame cinema cameras, enabling end-to-end workflows for broadcast and film clients.
-
Canon Inc. — Deep strength in hybrid and cinema-class bodies, coupled with an expanding lens portfolio and IP control surfaces—well-positioned for customers seeking tight optical-system integration and established service networks.
-
Panasonic — A dual-purpose supplier with cinema-grade VariCam technologies and broadcast-focused system cameras; notable where vendors must support both narrative and live-event workflows.
-
Blackmagic Design — Aggressive product cadence and disruptive pricing that accelerates feature adoption. Recent 100G Ethernet-enabled models signal a strategic push into live, multicamera IP production environments.
-
RED Digital Cinema / Nikon — The integration of RED’s modular high-resolution platforms into a broader imaging portfolio (post-acquisition) creates a notable vector for high-end cinematography and studio-level capture ecosystems.
-
ARRI — The premium reference in digital cinema; recent ownership and strategic moves indicate a sharper focus on aligning camera and lighting systems to live event and multicam environments.
-
Regional and systems players (JVC Kenwood, Grass Valley, Ikegami, AJA, Kokusai Denki) — These firms are critical where IP workflows, studio integration, and broadcast-specific tooling matter most. They are often the preferred partners for systems integrators and broadcasters executing large-scale transitions to cloud and IP-native operations.
Recent company-level developments—SKU introductions that emphasize 100G and SMPTE-2110 outputs, strategic acquisitions to combine optics and systems expertise, and lens/telemetry extensions—underline that incumbents are jockeying for platform-level differentiation rather than competing on single-product features alone.
Strategic implications by stakeholder
-
OEMs and product leaders — Prioritize system interoperability, certify for emergent IP transport standards, and architect modular upgrade paths. Differentiation through optics and imaging pipelines will remain a high-value territory—especially where price elasticity is lower (high-end production and rental markets).
-
Systems integrators and broadcasters — Adopt staged migration plans that allow hybrid operation between SDI and IP environments. Invest in staff training and orchestration layers now to reduce switching friction when moving to fully IP-native workflows.
-
Rental houses and production services — Flexibility and rapid refresh matter: a balanced fleet that includes modular cinema bodies, high-resolution capture kits, and broadcast-oriented multi-cam systems will maximize utilization across event and scripted work.
-
Investors and M&A strategists — Acquisition targets that combine optics expertise, IP transport know-how, and cloud-friendly middleware present the most attractive value-creation runway. The market shows room for tuck-ins that fill gaps in interoperability and live production automation.
What the PW Consulting study delivers (practical, decision-ready outputs)
-
Scenario-based revenue models anchored to the 2020–2025 historical cadence and extending through 2032, reflecting multiple adoption curves and input-cost shocks.
-
Supplier risk matrix and mitigation playbook—prioritizing component exposures (storage, optics), recommended sourcing strategies, and cost pass-through sensitivities for contract design.
-
Go-to-market and product roadmaps linked to buyer segmentation, channel economics, and rental versus purchase lifetime value models for 2026 planning cycles.
-
Competitive benchmarking and M&A playbook, including diligence checklists for integration-readiness across imaging pipelines and live-production software stacks.
-
Implementation checklists for IP migration, staff re-skilling timelines, and capital-expenditure phasing to avoid capability gaps during transitional windows.
The “trailer” — what we’re intentionally not disclosing here
In keeping with the report’s role as both a strategic primer and a client-ready deliverable, this overview intentionally omits granular segment-level figures and regional/application splits that materially influence transaction-level decisions. The full study contains the detailed segmentation, scenario spreadsheets, supplier lists, and customer-use case analytics that enable a board-level vote or a capex allocation with confidence. Consider this piece a strategic preview—offering the patterns and implications without publishing the discrete figures that our enterprise clients rely on for execution.
How to use this analysis in Q3–Q4 2026 planning
-
Frame capital allocation decisions against the scenario set—opt for options (modular platforms, firmware-enabled upgrades) that preserve upside if the accelerated-adoption case materializes.
-
Run supplier stress tests now: model component shocks in partnership with procurement to size buffer inventories and evaluate alternative architectures that reduce storage and glass content sensitivity.
-
Accelerate interop certifications and strategic partnerships where IP and 100G workflows matter; the first movers here will capture disproportionate share among large broadcasters and event producers.
For leaders preparing board materials, structuring acquisition diligence, or calibrating product roadmaps for 2026, PW Consulting’s full Digital Broadcast and Cinematography Cameras Market study is designed to be the operational playbook you can act on immediately. The preview above maps the strategic contours—download the full report to access the granular forecasts, supplier matrices, and transaction-level insights required to convert strategy into capture-ready outcomes.
For detailed analysis of this topic, please visit the official page: Digital Broadcast and Cinematography Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerant Leak Detectors Market to hit USD 1,658M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-09
Refrigerant Leak Detectors Market — Strategic Outlook for 2026 Decisions (PW Consulting)
As regulatory pressure, refrigerant chemistry transitions, and digital monitoring converge, the refrigerant leak detectors market is entering a phase of sustained, engineered growth. PW Consulting’s latest study—anchored on a 2025 base year and providing a forward view to 2032—models this market expanding at a compound annual growth rate (CAGR) of 6.8%. That trajectory implies a step-change in addressable revenue and investment opportunity between 2026 and the end of the forecast horizon. This article summarizes the strategic value of the research for executives preparing 2026 budgets, product roadmaps, compliance programs, and M&A pipelines, while preserving the detailed segment-level datasets and financial breakdowns for subscribers to the full report.
Refrigerant Leak Detectors Market
Why this study is essential for 2026 strategic planning
-
Regulatory compliance is now a procurement driver: new requirements effective from 2026 accelerate replacement, retrofit, and monitoring investments across regulated equipment classes.
Refrigerant Leak Detectors Market -
Technology differentiation matters: sensor chemistry, detection methodology (infrared, heated-diode, ultrasonic, solid-state), and connectivity options are reshaping product roadmaps and pricing power.
Refrigerant Leak Detectors Market -
Service-led monetization is maturing: remote monitoring, subscription models, and centralized alarm management convert hardware sales into recurring revenue.
-
Channel and aftermarket playbooks require refresh: contractors, OEMs, and facility managers are altering buying behavior in response to compliance deadlines and technician certification requirements.
Market trajectory and macro context
Our top-line model shows the market already beyond the billion-dollar threshold in the 2025 base year, with a steady expansion through 2032 driven by replacement cycles, retrofits for lower-GWP refrigerants, and mandated monitoring for high-charge installations. The CAGR of 6.8% encapsulates both organic growth in serviceable equipment populations and the premium captured by higher-value fixed-monitoring and remote-supervision solutions. Importantly for 2026 planning, the next 12–18 months represent a compressive period in which regulation, standards adoption, and product rollouts converge — creating windows for first-mover advantage.
Key dynamics shaping supplier and buyer decisions (2026–2027)
-
Regulatory acceleration: Expanded refrigerant management rules that took effect in early 2026 increase the number of appliances subject to formal leak management. Further, mandates requiring automatic leak detection for very large HFC-charged systems create near-term demand spikes for fixed and centralized monitoring platforms.
-
Standards harmonization: New and updated standards for electronic probe detectors and certification protocols (including SAE updates and state-level calibration requirements) are moving buyers toward certified, traceable devices — raising the bar for market entry and second-source qualification.
-
Refrigerant transitions: Growing adoption of mildly flammable A2L refrigerants, CO2 systems, and low-GWP blends drives demand for detector technologies validated across a broader chemistry set and for devices rated to specific safety standards.
-
Digital and remote monitoring: Product launches and trade-show previews in late 2025 and early 2026 highlight embedded connectivity, cloud platforms, and 24/7 remote alarm management as differentiators — particularly for commercial and industrial accounts.
-
Workforce competency: Expanded certification requirements for technicians introduce a practical barrier that favors suppliers offering simple-to-use, low-calibration, or maintenance-free instruments, as well as training partnerships with distributors.
Competitive landscape — implication for positioning and partnerships
The competitive map is a mix of legacy test-equipment OEMs, specialized sensor innovators, industrial monitoring firms, and a growing set of manufacturers from Asia focused on cost-competitive units. The market exhibits a moderate concentration: the top three providers control roughly half of the market by revenue, and the top five approach the upper half‑decile. This structure creates room both for scale players to protect share through certification and channel depth, and for focused specialists to win premium niches through technology leadership.
-
Technology and product leaders: Firms with proven multi-chemistry detectors (including infrared and heated-diode platforms), long-life sensors, and validated A2L solutions are best positioned to command premium margins in regulated commercial and industrial segments. Recent new-product introductions highlight an industry pivot toward higher sensitivity, better pump performance, and extended sensor life.
-
Connectivity and systems players: Suppliers integrating cloud connectivity and centralized supervision systems are converting one-time hardware sales into managed services. Remote-monitoring capabilities displayed at industry events in 2026 indicate substantial interest from end-users seeking continuous compliance and analytics.
-
Standards and certification differentiators: Companies that quickly certify to updated SAE procedures and to region-specific calibration standards gain a practical advantage in procurement processes where traceability is required.
-
Regional and cost-focused competitors: Competitive pressure from lower-cost manufacturers persists for handheld and portable models. These suppliers can gain volume share in less-regulated markets or in price-sensitive service channels.
Recent product and industry moves to watch
-
Late‑2025/early‑2026 product rollouts and trade-show reveals emphasize three trends: improved sensitivity and pump designs for handhelds, maintenance-free infrared options for A2L chemistries, and centralized remote monitoring systems suited to large commercial portfolios.
-
Certifications against updated SAE test procedures and other standards materially change buying criteria for contractors and facility operators—making certification timetables a critical part of go‑to‑market planning.
What the full PW Consulting report contains (operational detail)
-
Transparent market-sizing and forecasting methodology (base year 2025, historic review 2020–2025, forecast 2026–2032), with downloadable model files for scenario stress-testing.
-
Segment-level analyses across product types, application verticals, and regions, with adoption curves, addressable market estimates, and sensitivity testing (note: detailed segment tables are reserved for report subscribers).
-
Competitive profiles for the industry’s leading and fast-emerging players, including product portfolios, differentiating IP, channel strategies, and comparative capability matrices.
-
Regulatory impact mapping that aligns rules, standards, and compliance dates to procurement windows and retrofit cycles — enabling compliance-first prioritization in capital planning.
-
Technology evaluation framework that scores detector technologies against sensitivity, cross-refrigerant compatibility, lifecycle cost, certification readiness, and integration potential with building/plant supervisory systems.
-
Commercial playbooks: pricing elasticity models, service and SaaS packaging options, distributor engagement strategies, and pilot-to-scale roadmaps for SaaS-enabled monitoring offerings.
-
M&A and investment scorecards, identifying acquisition archetypes (sensor providers, cloud-platform vendors, regional channel consolidators) and valuation sensitivities informed by recurring revenue potential.
How to use this intelligence to shape 2026 decisions
-
Prioritize compliance-driven demand: Align R&D and inventory investments to the equipment classes and installation profiles that are first impacted by regulation. Time product certifications to precede procurement cycles.
-
Bundle hardware with managed services: Pilot remote-monitoring subscriptions with strategic customers to demonstrate recurring revenue economics and to shorten sales cycles for larger fixed-monitoring deployments.
-
Certify early, market loudly: Attaining updated SAE standards and regional calibration approvals should be treated as commercial milestones — factor certification timelines into launch calendars and channel incentives.
-
Optimize channel economics: Re-calibrate distributor margins and field‑technician incentives to accelerate adoption among service contractors, who are often the de facto buyers of handheld and portable solutions.
-
Screen M&A targets by tech defensibility and service attach potential: Prioritize assets that complement an existing monitoring stack or that accelerate access to certified sensors and cloud telemetry.
Final observations — urgency and opportunity
For executives mapping 2026 spend and strategic initiatives, the refrigerant leak detectors market presents a predictable, regulation‑anchored growth environment with clear levers for value creation. Hardware sales remain the foundation, but the real upside is in certified, multi-chemistry solutions and in converting monitoring into recurring services. The market’s moderate concentration enables both scale consolidation plays and specialist premium niches; success will depend on moving quickly on certification, connectivity, and channel alignment.
PW Consulting’s full report provides the underlying data, segment-level revenue tables, regional breakouts, and actionable model workbooks required to justify capital allocations, prioritize R&D, and select acquisition targets. The summary above outlines the strategic contours — the report itself is the operational map senior leaders need to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Refrigerant Leak Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com