

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wheat Straw Pulp Market to Expand at 7.77% CAGR

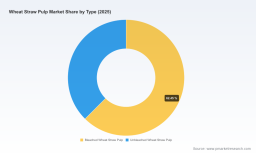
Wheat Straw Pulp Market — Strategic Preview for 2026 Decision-Makers
As companies prepare strategic moves in 2026, wheat straw pulp has transitioned from a niche sustainability play to a mainstream industrial raw material. Our latest PW Consulting industry study—anchored on a 2025 base year and projecting through 2032—shows a market that has roughly doubled in scale since 2020 and is set to continue expanding at a mid-single-digit compound annual growth rate. For executives weighing investments, partnerships, and product-roadmap decisions next year, a disciplined read of the structural drivers and competitive dynamics in this report will materially change risk-return assumptions.
Wheat Straw Pulp Market
Why this market matters in 2026
-
Macro momentum. The global wheat straw pulp market has expanded from an early 2020 base to a multi-billion-dollar industry by 2025, and our forecast points to steady expansion through 2032 at a compounded rate of approximately 7.8% annually. That growth is not cyclical flaring; it reflects durable substitution trends across packaging, tissue, specialty paper, textiles and emerging biodegradable polymer feedstocks.
Wheat Straw Pulp Market -
Policy and corporate decarbonization align. Regulatory pressure on forestry-based fiber and corporate net‑zero commitments are making agricultural residues an economically and politically attractive feedstock. Wheat straw scores high on both lifecycle carbon and land-use neutrality compared to wood‑derived pulp, which reshapes buyer preferences from procurement committees to brand marketing teams.
Wheat Straw Pulp Market -
Value migration in the paper-fiber stack. Raw material cost volatility in wood pulp, combined with investments in non-wood pulping technologies and process efficiencies, are shifting product economics. Buyers increasingly view wheat-straw-derived fibers as a reliable substitute for specific grades, not merely an alternative for sustainability messaging.
Market trajectory and what the numbers signal
The market’s historical trajectory highlights two complementary dynamics: accelerating adoption and improving unit economics. Since 2020 the global market has grown meaningfully, and our 2026 opening-point scenario positions the industry on a rising curve toward the 2032 horizon. With an average growth rate approaching 7.8% over the forecast period, this implies that decisions made in 2026—about capacity expansion, offtake agreements, feedstock logistics, and technology licensing—will capture a significant portion of lifetime value for new entrants and incumbents alike.
Importantly, growth is not uniform across every value chain node. The incremental demand for wheat straw pulp is concentrated where substitution is most technically feasible and where buyers reward sustainability credentials with price premiums. The full report contains the granular regional and end-market decomposition, as well as price curve dynamics and unit-cost sensitivity models required to stress-test investment cases; those details are intentionally reserved for the complete deliverable.
Drivers and headwinds to prioritize in your 2026 planning
-
Supply-side dynamics. Wheat straw is a residual agricultural stream; its commercial availability is scale-dependent and sensitive to crop rotations, yield shifts and competing uses (e.g., animal bedding, soil amendment). Strategic sourcing and farmer engagement programs—rather than pure spot-market purchases—reduce feedstock risk and improve margin visibility.
-
Technology and product differentiation. Process choices (bleached vs. unbleached processes, yield-optimized pulping recipes, and post-pulp functionalization for molded products) create defensible product segmentation. Companies that pair process IP with downstream integration (tissue, molded fiber packaging, specialty papers) capture more value.
-
Logistics and regional fit. Economics are sensitive to haul distances and seasonal collection windows. Cities with integrated mill ecosystems and efficient transport corridors have a structural cost advantage—a factor that should inform greenfield planning and M&A target screening.
-
Market concentration and partnership opportunities. The market is moderately consolidated: leading suppliers account for a meaningful share of capacity, but there remains room for new large-scale entrants. This dynamic creates fertile ground for offtake partnerships, joint ventures with agricultural co-ops and white-label supply agreements with global paper converters.
-
Regulatory and certification tailwinds. Lifecycle certifications and compliance schemes are evolving rapidly. Early alignment with recognized sustainability standards reduces time-to-market for premium placements, while missteps can lead to commercial delays.
Competitive landscape — positioning and conflict zones
The ecosystem today includes a mix of legacy pulp producers adapting to non-wood feedstocks, vertically integrated tissue and packaging players, and new scale entrants focused specifically on straw mills. A brief, non-exhaustive orientation to representative players illustrates strategic archetypes you will confront when moving into or expanding within the space:
-
Regional scale specialty producers: Companies that started with refined non-wood pulps and have integrated downstream (e.g., household paper and molded products). Their strengths are established farmer networks and product formulations tuned for consumer goods.
-
Large-scale commodity manufacturers pivoting to straw: Major paper groups that add straw-based lines to existing mills, leveraging distribution reach and brand relationships to accelerate adoption in tissue and towel grades.
-
Greenfield, climate-first entrants: New-build projects that emphasize high throughput and low lifecycle carbon footprints, targeting premium segments like sustainable packaging and climate-positive tissue. Their playbook centers on financing for infrastructure and high-volume offtake contracts.
-
Regional non-wood pioneers: Companies that focus on localized mill deployments to serve adjacent markets, optimizing logistics and engaging deeply with agricultural suppliers for feedstock security.
These archetypes are embodied by incumbent names that have different risk profiles and strategic objectives—ranging from established tissue majors operating large bleached straw pulp lines to regional innovators developing climate-positive capacity. The competitive balance—top players holding a substantive share but with room for new challengers—underscores why 2026 is a pivotal timing window for partnerships, capacity commitments, and defensive contracts.
What the PW Consulting report delivers — practical assets for 2026 execution
Our study is designed as a decision-support toolkit for commercial, strategy, and M&A teams. The deliverables are practical, transaction-focused and ready to be operationalized into 2026 planning cycles:
-
Dynamic market model. Interactive base and scenario forecasts (base, conservative, upside) with sensitivity toggles for feedstock cost, pulp yields, capital intensity and price premia—built to be plugged into internal investment models.
-
Supply-demand matrix and regional sourcing map. A practical guide to where material can be aggregated at scale, with logistics-cost envelopes and seasonal availability windows (note: the granular regional and application-level split is available in the full dataset).
-
Commercial playbooks. Negotiation scripts and model contract clauses for long-term offtake, tolling agreements and feedstock procurement frameworks—tuned for both buyers and sellers.
-
Technology and process benchmarking. Comparative analysis of bleaching approaches, yield vs. brightness trade-offs, and decarbonization levers; plus a vendor short-list for turnkey plant solutions.
-
M&A and JV scorecards. A replicable scoring framework to rank targets on feedstock security, technical fit, regulatory exposure and integration complexity.
-
Regulatory & certification roadmap. Practical pathways to certification and EPD readiness to achieve premium positioning in buyer tenders.
-
Executive dashboard. KPIs that matter for 2026 execution—cash-on-cash payback ranges, breakeven deltas versus wood pulp, and operating metrics for ramp planning.
Recommended 90‑day agenda for C-suite and corporate development teams (teaser)
-
Align valuation assumptions. Use a conservative base-case for feedstock availability and run upside scenarios for premium product adoption. The full model in our report gives instant visibility into valuation sensitivity.
-
Secure pilot offtakes. Lock one or two strategic customers for blended supply to derisk early operations and demonstrate conversion economics to investors or lenders.
-
Design a feedstock partner network. Move beyond spot procurement—design an aggregator model with farmer incentives, seasonal storage, and price collars to stabilize costs.
-
Prioritize incremental quality improvements. Invest in process tweaks that unlock at-scale substitution in high-margin grades rather than trying to be everything to all customers at launch.
Closing perspective
Wheat straw pulp is no longer a curiosity; it is a commercially viable lever for companies targeting lower-carbon fibers at scale. The market’s growth trajectory and the evolving competitive map create concrete opportunities for new entrants and established players willing to make targeted 2026 commitments. However, the value is captured by teams that combine rigorous supply-chain design, process differentiation and a pragmatic commercial rollout.
PW Consulting’s full Wheat Straw Pulp Market report provides the complete, transaction-grade intelligence—regional and application-level breakdowns, price curves, contract templates and the detailed scenario models required to finalize a 2026 investment or partnership decision. For executives intent on making a decisive move next year, the full dataset and playbooks are available via our report portal.
For detailed analysis of this topic, please visit the official page: Wheat Straw Pulp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com