

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Refrigerant Leak Detectors Market to hit USD 1,658M by 2032 at 6.8% CAGR

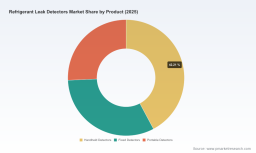
Refrigerant Leak Detectors Market — Strategic Outlook for 2026 Decisions (PW Consulting)
As regulatory pressure, refrigerant chemistry transitions, and digital monitoring converge, the refrigerant leak detectors market is entering a phase of sustained, engineered growth. PW Consulting’s latest study—anchored on a 2025 base year and providing a forward view to 2032—models this market expanding at a compound annual growth rate (CAGR) of 6.8%. That trajectory implies a step-change in addressable revenue and investment opportunity between 2026 and the end of the forecast horizon. This article summarizes the strategic value of the research for executives preparing 2026 budgets, product roadmaps, compliance programs, and M&A pipelines, while preserving the detailed segment-level datasets and financial breakdowns for subscribers to the full report.
Refrigerant Leak Detectors Market
Why this study is essential for 2026 strategic planning
-
Regulatory compliance is now a procurement driver: new requirements effective from 2026 accelerate replacement, retrofit, and monitoring investments across regulated equipment classes.
Refrigerant Leak Detectors Market -
Technology differentiation matters: sensor chemistry, detection methodology (infrared, heated-diode, ultrasonic, solid-state), and connectivity options are reshaping product roadmaps and pricing power.
Refrigerant Leak Detectors Market -
Service-led monetization is maturing: remote monitoring, subscription models, and centralized alarm management convert hardware sales into recurring revenue.
-
Channel and aftermarket playbooks require refresh: contractors, OEMs, and facility managers are altering buying behavior in response to compliance deadlines and technician certification requirements.
Market trajectory and macro context
Our top-line model shows the market already beyond the billion-dollar threshold in the 2025 base year, with a steady expansion through 2032 driven by replacement cycles, retrofits for lower-GWP refrigerants, and mandated monitoring for high-charge installations. The CAGR of 6.8% encapsulates both organic growth in serviceable equipment populations and the premium captured by higher-value fixed-monitoring and remote-supervision solutions. Importantly for 2026 planning, the next 12–18 months represent a compressive period in which regulation, standards adoption, and product rollouts converge — creating windows for first-mover advantage.
Key dynamics shaping supplier and buyer decisions (2026–2027)
-
Regulatory acceleration: Expanded refrigerant management rules that took effect in early 2026 increase the number of appliances subject to formal leak management. Further, mandates requiring automatic leak detection for very large HFC-charged systems create near-term demand spikes for fixed and centralized monitoring platforms.
-
Standards harmonization: New and updated standards for electronic probe detectors and certification protocols (including SAE updates and state-level calibration requirements) are moving buyers toward certified, traceable devices — raising the bar for market entry and second-source qualification.
-
Refrigerant transitions: Growing adoption of mildly flammable A2L refrigerants, CO2 systems, and low-GWP blends drives demand for detector technologies validated across a broader chemistry set and for devices rated to specific safety standards.
-
Digital and remote monitoring: Product launches and trade-show previews in late 2025 and early 2026 highlight embedded connectivity, cloud platforms, and 24/7 remote alarm management as differentiators — particularly for commercial and industrial accounts.
-
Workforce competency: Expanded certification requirements for technicians introduce a practical barrier that favors suppliers offering simple-to-use, low-calibration, or maintenance-free instruments, as well as training partnerships with distributors.
Competitive landscape — implication for positioning and partnerships
The competitive map is a mix of legacy test-equipment OEMs, specialized sensor innovators, industrial monitoring firms, and a growing set of manufacturers from Asia focused on cost-competitive units. The market exhibits a moderate concentration: the top three providers control roughly half of the market by revenue, and the top five approach the upper half‑decile. This structure creates room both for scale players to protect share through certification and channel depth, and for focused specialists to win premium niches through technology leadership.
-
Technology and product leaders: Firms with proven multi-chemistry detectors (including infrared and heated-diode platforms), long-life sensors, and validated A2L solutions are best positioned to command premium margins in regulated commercial and industrial segments. Recent new-product introductions highlight an industry pivot toward higher sensitivity, better pump performance, and extended sensor life.
-
Connectivity and systems players: Suppliers integrating cloud connectivity and centralized supervision systems are converting one-time hardware sales into managed services. Remote-monitoring capabilities displayed at industry events in 2026 indicate substantial interest from end-users seeking continuous compliance and analytics.
-
Standards and certification differentiators: Companies that quickly certify to updated SAE procedures and to region-specific calibration standards gain a practical advantage in procurement processes where traceability is required.
-
Regional and cost-focused competitors: Competitive pressure from lower-cost manufacturers persists for handheld and portable models. These suppliers can gain volume share in less-regulated markets or in price-sensitive service channels.
Recent product and industry moves to watch
-
Late‑2025/early‑2026 product rollouts and trade-show reveals emphasize three trends: improved sensitivity and pump designs for handhelds, maintenance-free infrared options for A2L chemistries, and centralized remote monitoring systems suited to large commercial portfolios.
-
Certifications against updated SAE test procedures and other standards materially change buying criteria for contractors and facility operators—making certification timetables a critical part of go‑to‑market planning.
What the full PW Consulting report contains (operational detail)
-
Transparent market-sizing and forecasting methodology (base year 2025, historic review 2020–2025, forecast 2026–2032), with downloadable model files for scenario stress-testing.
-
Segment-level analyses across product types, application verticals, and regions, with adoption curves, addressable market estimates, and sensitivity testing (note: detailed segment tables are reserved for report subscribers).
-
Competitive profiles for the industry’s leading and fast-emerging players, including product portfolios, differentiating IP, channel strategies, and comparative capability matrices.
-
Regulatory impact mapping that aligns rules, standards, and compliance dates to procurement windows and retrofit cycles — enabling compliance-first prioritization in capital planning.
-
Technology evaluation framework that scores detector technologies against sensitivity, cross-refrigerant compatibility, lifecycle cost, certification readiness, and integration potential with building/plant supervisory systems.
-
Commercial playbooks: pricing elasticity models, service and SaaS packaging options, distributor engagement strategies, and pilot-to-scale roadmaps for SaaS-enabled monitoring offerings.
-
M&A and investment scorecards, identifying acquisition archetypes (sensor providers, cloud-platform vendors, regional channel consolidators) and valuation sensitivities informed by recurring revenue potential.
How to use this intelligence to shape 2026 decisions
-
Prioritize compliance-driven demand: Align R&D and inventory investments to the equipment classes and installation profiles that are first impacted by regulation. Time product certifications to precede procurement cycles.
-
Bundle hardware with managed services: Pilot remote-monitoring subscriptions with strategic customers to demonstrate recurring revenue economics and to shorten sales cycles for larger fixed-monitoring deployments.
-
Certify early, market loudly: Attaining updated SAE standards and regional calibration approvals should be treated as commercial milestones — factor certification timelines into launch calendars and channel incentives.
-
Optimize channel economics: Re-calibrate distributor margins and field‑technician incentives to accelerate adoption among service contractors, who are often the de facto buyers of handheld and portable solutions.
-
Screen M&A targets by tech defensibility and service attach potential: Prioritize assets that complement an existing monitoring stack or that accelerate access to certified sensors and cloud telemetry.
Final observations — urgency and opportunity
For executives mapping 2026 spend and strategic initiatives, the refrigerant leak detectors market presents a predictable, regulation‑anchored growth environment with clear levers for value creation. Hardware sales remain the foundation, but the real upside is in certified, multi-chemistry solutions and in converting monitoring into recurring services. The market’s moderate concentration enables both scale consolidation plays and specialist premium niches; success will depend on moving quickly on certification, connectivity, and channel alignment.
PW Consulting’s full report provides the underlying data, segment-level revenue tables, regional breakouts, and actionable model workbooks required to justify capital allocations, prioritize R&D, and select acquisition targets. The summary above outlines the strategic contours — the report itself is the operational map senior leaders need to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Refrigerant Leak Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com