

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Heavy Duty Conveyor Belts Market to Grow at 5.5% CAGR to 2032

Heavy Duty Conveyor Belts Market — Strategic Outlook for 2026 Decision‑Making
Executive teaser: why this market matters to your 2026 agenda
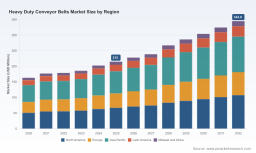
The heavy duty conveyor belts market is entering its most strategically consequential window in a decade. Between 2020 and the base year 2025, the global market expanded from approximately USD 163.2 Million to USD 215.0 Million; our modeling then projects growth to roughly USD 228.1 Million in 2026 and continues to a market size near USD 344.8 Million by 2032, underpinned by a compound annual growth rate (CAGR) of about 5.5% over the forecast horizon (2026–2032). For procurement leads, product strategists, and M&A teams, that trajectory signals persistent demand coupled with structural change — an opportunity to convert tactical wins this year into durable competitive advantage.
What this briefing delivers (and what it intentionally withholds)
- Confidence-building, data-driven context on market scale and pace (historical and forecast).
- Operationally actionable perspectives on supply chain risk, product innovation priorities, aftermarket economics, and regulatory drivers that will shape budgets and partner selection in 2026.
- A forward-looking competitive lens on the manufacturers and platform plays who will set price and service benchmarks.
- Strictly curated excerpts of analysis and implications — we deliberately withhold granular subsegment tables and exact regional/application splits to encourage direct access to the full dataset and dynamic models in the complete report.
Market structure and competitive dynamics — what you must internalize
Two structural features define the landscape for heavy duty conveyor belts in 2026: steady, mid-single-digit growth at the aggregate level, and a fragmented supplier base that keeps pricing and service quality highly local and relationship-driven. Measured concentration ratios (CR3 ≈ 24.6%; CR5 ≈ 26.2%) indicate that no small set of firms controls the majority of sales — an environment that both invites consolidation and rewards organizations that can orchestrate superior value chains, aftermarket offerings, or advanced materials.
Demand remains dominated by capital‑intensive sectors with long asset lifecycles. That creates a bifurcated buyer universe: large operators who prioritize total cost of ownership, reliability, and digital monitoring; and smaller integrators focused on price-to-performance and speed of delivery. Winning requires a tailored go-to-market that blends product engineering, field service excellence, and digital enablement.
Key strategic forces to prioritize in 2026
- Raw‑material and reinforcement dynamics: Steel‑cord reinforcement continues to be the backbone for heavy‑duty belts, with tensile specifications that range widely for mining and bulk handling applications. Securing upstream supply and engineering alternatives (e.g., performance fabrics, hybrid constructs) should be a procurement and R&D priority given price cyclicality and geopolitical exposure in steel markets.
- Regulatory and energy efficiency pressure: Energy standards and industry labeling regimes are accelerating development of low‑rolling‑resistance rubbers and higher‑efficiency belt systems. Firms that can credibly demonstrate energy savings will unlock both procurement preferences and longer service life economics.
- Labor and service cost optimization: Maintenance, splicing, and specialist field service labor are critical cost centers. Investments in training, advanced splicing technologies, and remote diagnostics reduce downtime and materially shift the lifetime cost equation.
- Digitalization and aftermarket monetization: Digital attachments and condition monitoring (sensors, IoT gateways, analytics) are transitioning from “nice-to-have” to procurement criteria. Mobile applications and on-site tools that simplify calculation, splicing guidance, and lifecycle tracking reduce operational friction and create recurring revenue opportunities.
Competitive snapshot — who to watch (and why)
Incumbent producers are moving beyond commodity supply into integrated product-service offerings. Below are concise strategic profiles of market movers whose plays will inform partner selection, benchmarking, and M&A screening in 2026:
- Continental AG (Germany) — ContiTech’s conveyor division pairs steel‑cord heavy‑duty belts with embedded digital monitoring solutions targeted at mining, construction, and bulk logistics. Their integrated sensor and service approach raises the bar on warranty and uptime guarantees; evaluate them when assessing end‑to‑end SLAs. ( continental.com )
- Fenner Dunlop Conveyor Belting (Netherlands / UK) — A broad portfolio of high‑strength steel‑cord and fabric belts, complemented by recent digital initiatives. Notably, in May 2026 Fenner Dunlop launched a mobile app—MyBelt—providing field crews and procurement teams with calculation tools, specifications, and splicing guidance. This exemplifies the platformization of aftermarket services. ( fennerdunlopamericas.com )
- Sempertrans Conveyor Belt Solutions GmbH (Austria) — Offers steel‑cord families with emphasis on energy savings and cover chemistries (flame retardant, heat‑resistant). Their product focus speaks to buyers balancing safety standards and thermal endurance in harsh installations. ( semperit.com )
- Habasit AG (Switzerland) — Known for durable rubber compounds for industrial material handling applications. Their strength lies in compound engineering and consistent regional service networks. ( habasit.com )
- Intralox L.L.C. (United States) — Focused on modular and heavy‑duty belt systems for processing environments; their modular approach appeals to processors seeking reduced downtime and rapid changeover. ( intralox.com )
Practical, tested actions for executives to take in 2026
- Procurement and supplier strategy: Reassess supplier panels with a double lens on raw‑material security and digital service capability. Introduce multi‑year contracts with indexed pricing and service KPIs; pilot vendor‑managed inventory in two high‑impact sites.
- R&D and product prioritization: Target low‑rolling‑resistance compounds and hybrid reinforcement architectures that lower system energy draw. Accelerate at least one product trial that couples belts with embedded sensing for predictive splicing alerts.
- Aftermarket and services monetization: Launch a tiered service catalogue (baseline warranty, performance guarantee, premium predictive package) and bundle mobile‑first tooling for field crews. Use telematics data to rationalize spare parts inventory and reduce mean time to repair.
- Operational cost control: Invest in technician upskilling and standardized splicing protocols; quantify expected downtime reduction and bake that into CapEx decision models for new installations.
- M&A and partnerships: With the market still fragmented, target acquisitions that bring either digital monitoring capabilities or regional aftermarket footprints. Prioritize bolt‑ons that accelerate time to first‑service revenue.
What the full PW Consulting report contains (select highlights)
- Comprehensive market sizing (historical 2020–2025; base year 2025; forecast 2026–2032) and scenario variants reflecting commodity price shocks and regulatory tightening.
- Segment profitability maps and total cost of ownership models by application class (note: full segment tables and exact regional splits are available only in the paid report).
- Supplier scorecards and an M&A playbook with valuation multipliers built for buyer synergies in manufacturing, digital services, and aftermarket.
- Operational playbooks: splicing and maintenance optimization, technician training curricula, and a pilot template for condition‑based monitoring deployment.
- Procurement RFP templates and risk mitigation checklists for steel cord and specialty rubber sourcing.
Implications for boardrooms planning 2026 budgets
Boards should view expenditures that align with digital monitoring, technician capability building, and secured upstream supply as investments that shift long‑term operating levers, not simple cost items. The projected growth path — from USD 215.0 Million in 2025 to an estimated USD 228.1 Million in 2026, and toward USD 344.8 Million by 2032 at a ~5.5% CAGR — makes a persuasive case to reallocate a modest share of CapEx into prototypes for energy‑efficient belts and into pilot deployments of condition monitoring. These initiatives shorten payback on service contracts and reduce the P&L volatility that stems from unplanned downtime and raw‑material swings.
Closing — why this is the right moment to act
The market’s steady growth, low concentration, and the rapid emergence of digital and material innovations create a rare window: incumbents with clear aftermarket and services strategies can convert growth into higher margin, while new entrants can capture niches by combining materials know‑how with plug‑and‑play digital services. PW Consulting’s full Heavy Duty Conveyor Belts Market report supplies the granular segmentation, scenario models, supplier benchmarking, and executable templates you need to convert 2026 investments into durable advantage. For an executive summary, model access, and to license the full dataset and operational toolkits, please consult the report landing page.
For detailed analysis of this topic, please visit the official page: Heavy Duty Conveyor Belts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com