

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Crop Protection Market to reach USD 100.3B by 2032

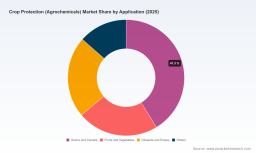
Crop Protection (Agrochemicals) Market — Strategic Briefing for 2026 Decisions
As companies prepare strategy for 2026, the crop protection market is evolving under the combined pressure of raw-material volatility, regulatory reshaping, and a clear, sustained demand trajectory. PW Consulting’s new market study synthesizes historical performance (2020–2025), a detailed 2026–2032 forecast, and scenario-based strategic guidance designed to support executive decisions this year. In brief: the global market is on a steady expansion path (compound annual growth ~5.2%), rising from roughly USD 52 billion in 2020 to nearly USD 70 billion by the 2025 base year and projecting to exceed USD 100 billion late in the next planning cycle. What follows is an executive-oriented preview of the study’s practical value and how decision-makers should use it to shape 2026 priorities.
Crop Protection (Agrochemicals) Market
Why this study matters for 2026
-
Actionable foresight: We quantify near-term revenue and cost levers and translate those into tactical actions for procurement, pricing, and portfolio optimization.
Crop Protection (Agrochemicals) Market -
Risk-aware planning: The report maps supply-chain pinch points and regulatory shock scenarios so you can prioritize hedges and contingency investments now — not after disruption arrives.
Crop Protection (Agrochemicals) Market -
Competitive playbooks: Profiles and scenario implications for the largest players give commercial and R&D teams a tactical edge when negotiating partners, licensing, or acquisition targets.
-
Capital allocation clarity: Forward-looking scenario economics allow CFOs and strategy teams to test ROI for new modes of action, biologicals, and formulation upgrades under multiple commodity- and regulatory-stress cases.
Market trajectory and what it implies for 2026 choices
The market’s CAGR of approximately 5.2% reflects a mix of steady acreage-driven demand, intensifying adoption of integrated pest management solutions, and growing but uneven uptake of biologicals and biorationals. The study’s baseline projects the global market moving from the mid-2025 level (~USD 70 billion) to a north-of-USD 100 billion market by the end of the forecast horizon — a compelling absolute growth opportunity, but one that conceals pronounced margin and supply divergence by product type and geography.
For executives, the implication is straightforward: volume growth alone will not guarantee margin expansion. 2026 strategy should therefore combine modest top-line growth ambitions with decisive moves to protect margins — through raw-material contracts, formulation rationalization, and prioritizing higher-value differentiated solutions.
What the report contains (practical, decision-ready modules)
-
Integrated market sizing and forecast model — scenario-enabled across base, upside, and stress cases with sensitivity levers for key inputs (commodity feedstocks, regulatory delistings, and technology adoption curves).
-
Supply-chain and input-cost matrix — supplier concentration maps, lead-time analysis, and stress-tested price-impact simulations to inform procurement and hedging for 2026 budgeting.
-
Regulatory-impact playbook — a prioritized list of jurisdictions where regulatory action will disproportionately affect product viability and timelines for compliance or exit options.
-
Competitive strategic dossiers — concise, comparative profiles of the sector’s largest firms (R&D focus, pipeline highlights, manufacturing footprint, and likely M&A behavior), with implications for partnership or defensive strategies.
-
Commercial go-to-market guidance — channel optimization, digital-sell-through options for seed and biological adjacencies, and pricing strategies calibrated to elasticities exposed by our demand model.
-
M&A and alliance scoring tool — prioritizes targets by technology, geography, and supply resilience, supplying a short-list and an indicative valuation framework for 2026 negotiation planning.
-
Product portfolio optimization workbook — a pragmatic triage framework for discontinuing, retaining, or investing in actives/formulations aligned to corporate risk tolerance and margin targets.
Competitive landscape — how incumbents are repositioning
The market remains concentrated: roughly three global players collectively account for the majority share, and the next tier elevates overall concentration further. That structure is producing two clear strategic responses among incumbents.
-
Defensification and efficiency: Large multinational crop protection groups are actively streamlining portfolios, consolidating manufacturing footprints, and trimming lower-margin products to protect margins and accelerate R&D investment into new modes of action and biologicals.
-
Vertical and capability reinvestment: Several leading players are strengthening capabilities in biologicals, formulations, and seed-trait integration — differentiating through platform capabilities rather than relying solely on legacy chemistries.
Firm-level implications (executive summary):
-
Bayer CropScience — continuing to rationalize non-core actives and streamline production and R&D footprints. Expect further portfolio outsourcing and targeted investments in novel MOAs and biologicals as the firm reallocates capital toward higher-return programs.
-
BASF SE — reinforcing integrated agricultural solutions and actively reacting to feedstock-cost pressure through pricing and commercial discipline. Their moves on pricing and raw-material management are a bellwether for commodity-driven margin stress across the value chain.
-
Syngenta Group — leveraging strength in seed-treatment and biological solutions to offset pressure on commodity actives; a likely acquirer/partner for firms with complementary biological assets or digital agronomy capabilities.
-
Corteva Agriscience — integrating traits and protection solutions while managing feedstock and export-control exposures; their financial calls signal sensitivity to input-cost shocks affecting active-ingredient pricing.
-
UPL Limited — pursuing sustainability-angled formulations and differentiated supply solutions, positioning as a low-cost but innovation-focused alternative for select markets.
-
FMC Corporation — focusing on biorationals and insecticide/fungicide innovation, serving specialty segments and higher-margin niches where rapid adoption of new chemistries is possible.
Recent industry signals you cannot ignore in 2026 planning
-
Raw-material shocks have immediate pass-through consequences. Recent supplier price moves and feedstock disruptions demonstrate that logistics and petrochemical pressures materially affect intermediate and active-ingredient costs, and companies should assume periodic cost shocks when stress-testing 2026 P&Ls.
-
Regulatory consolidation and portfolio pruning are accelerating among majors. The trend toward outsourcing and plant rationalization is structural — firms are reallocating to protect R&D pipelines and margins, which will reshape competitive positioning in select active classes.
-
Export-controls and regional supply restrictions have localized effects. Shifts in export policy and feedstock availability are raising the effective cost and lead times for certain actives; firms with diversified manufacturing and flexible sourcing will gain a sustainable advantage.
How to use this research in 2026: decision steps
-
Procurement: Establish tiered supply agreements and negotiate clauses that mitigate feedstock price spikes for the next 12–24 months. Use our supplier-risk heat map to prioritize backup sourcing.
-
Portfolio: Execute a rapid portfolio triage using our investment-priority framework — accelerate high-margin differentiated products and biologicals; divest or partner on lower-return legacy actives.
-
R&D: Reallocate a portion of incremental R&D spend to biologicals and formulation platforms that reduce raw-material intensity and regulatory exposure.
-
Commercial: Reweight channel mix toward more predictable, value-accretive routes-to-market and adjust pricing models to reflect input-cost pass-through realities.
-
M&A: Use the report’s target-screening to identify acquisition or alliance candidates that address supply, capability, or geographic gaps.
What we intentionally withhold here — and why
This briefing demonstrates the actionable intelligence and strategic scaffolding contained in the full PW Consulting study while preserving the granular segment-level economics and company-specific forecast details that deliver commercial advantage. The full report contains detailed region- and application-level splits, product-by-product margin tables, proprietary demand elasticities, and a live modeling workbook — elements we reserve for full-report access to protect client value and proprietary methodology.
Next steps
If your 2026 plan requires defensible choices on procurement, R&D allocation, or M&A priorities, PW Consulting’s full Crop Protection market study provides the scenario models, supplier maps, and company dossiers you need to move from analysis to execution. Contact our team to schedule a tailored briefing; we will walk you through the model, stress-test your hypotheses, and co-develop the 90-day action plan aligned to your risk appetite.
For detailed analysis of this topic, please visit the official page: Crop Protection (Agrochemicals) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com