

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital Broadcast & Cinema Cameras to Reach USD 3.27B by 2032 at 7.25% CAGR

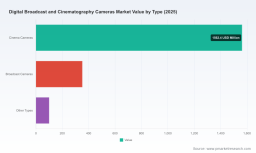
Digital Broadcast and Cinematography Cameras: Strategic Outlook for 2026 Decision-Makers
As media businesses, hardware OEMs, systems integrators, and investors plan for the next strategic cycle, understanding the topology of demand, supply-side pressure points, and technology inflection becomes a prerequisite for defensible decisions. PW Consulting’s latest market study on Digital Broadcast and Cinematography Cameras (base year 2025) synthesizes seven years of historic behavior and a near-term forecast horizon to 2032—delivering the contextual intelligence needed to prioritize capex, R&D, M&A, and channel strategies through 2026 and beyond.
Digital Broadcast and Cinematography Cameras Market
Executive snapshot
The market has shown a steady expansion across the 2020–2025 historical window and is projected to continue growing through our forecast period. Using 2025 as the reference point, the study applies a 7.25% compound annual growth rate (CAGR) across the forecast horizon. That steady, above-average growth reflects durable secular tailwinds: continued content production, higher-resolution capture requirements for premium streaming and live-event workflows, and the transition to IP-native studio architectures. Importantly, the market exhibits moderate concentration—neither a closed oligopoly nor a highly atomized commodity segment—creating room for both incumbents and well-capitalized challengers to shape outcomes.
Digital Broadcast and Cinematography Cameras Market
Why this study matters for 2026 decisions
-
Capital allocation under uncertainty: Our modeling reconciles multiple demand scenarios (base, accelerated, downside) and translates each into balanced investment roadmaps for manufacturers and content owners. The result is a short-list of timing-sensitive opportunities—upgrade cycles, SKU rationalization, and platform investments—that materially affect IRR timelines.
Digital Broadcast and Cinematography Cameras Market -
Supplier risk and resiliency: Component volatility—particularly for flash storage and precision glass—has compressed product development timelines and margins across the ecosystem. The study quantifies supplier exposure and presents mitigation options (dual-sourcing, inventory strategy, and design-level substitutions) that remain actionable in 2026 procurement cycles.
-
Product and channel playbooks: Our buyer-seller matrices identify where premium-spec cinema cameras, modular cinema platforms, and broadcast-oriented system cameras intersect with evolving customer preferences—live sports, streaming drama, immersive 3D, and cloud-based production. For channel leaders, we map the GTM approaches that yield the highest commercial leverage within each scenario.
Market dynamics and technology inflection points
The camera market is at the intersection of multiple structural shifts. Resolution and sensor performance continue to climb—driven by studios, streaming platforms, and advanced live-event productions—while transport and connectivity standards (e.g., IP-centric SMPTE flows and 100G Ethernet) accelerate system-level change. Simultaneously, supply-side noise has become a practical planning constraint:
-
Flash storage pricing and availability: Elevated demand from AI compute infrastructure has tightened the flash market. Our scenario analyses show that storage cost dynamics materially affect price/performance in high-resolution camera platforms, influencing both BOM costs and service economics for rental houses and broadcasters.
-
Lens glass and optics supply: Competitive pricing pressure from select Asian glass manufacturers is reshaping lens margins and has prompted some premium optics houses to reconsider vertical or partnership strategies to protect quality and lead times.
-
Regulatory and standards-driven feature sets: Emerging requirements—such as multi-sensor redundancy for immersive 3D capture and tighter interoperability for IP-native live production—drive incremental engineering scope and certification costs. OEMs that front-load compliance design will enjoy faster enterprise adoption.
Competitive landscape — who matters and why
The competitive map blends legacy broadcast champions with cinema-focused innovators and software-driven newcomers. Market concentration metrics indicate a landscape where a handful of leaders control material share, but an enlarged middle tier continues to win on specialization and price-performance.
-
Sony Corporation — Strong crosswalk between high-performance cinema sensors and live production systems; their product family spans live HDC systems to full-frame cinema cameras, enabling end-to-end workflows for broadcast and film clients.
-
Canon Inc. — Deep strength in hybrid and cinema-class bodies, coupled with an expanding lens portfolio and IP control surfaces—well-positioned for customers seeking tight optical-system integration and established service networks.
-
Panasonic — A dual-purpose supplier with cinema-grade VariCam technologies and broadcast-focused system cameras; notable where vendors must support both narrative and live-event workflows.
-
Blackmagic Design — Aggressive product cadence and disruptive pricing that accelerates feature adoption. Recent 100G Ethernet-enabled models signal a strategic push into live, multicamera IP production environments.
-
RED Digital Cinema / Nikon — The integration of RED’s modular high-resolution platforms into a broader imaging portfolio (post-acquisition) creates a notable vector for high-end cinematography and studio-level capture ecosystems.
-
ARRI — The premium reference in digital cinema; recent ownership and strategic moves indicate a sharper focus on aligning camera and lighting systems to live event and multicam environments.
-
Regional and systems players (JVC Kenwood, Grass Valley, Ikegami, AJA, Kokusai Denki) — These firms are critical where IP workflows, studio integration, and broadcast-specific tooling matter most. They are often the preferred partners for systems integrators and broadcasters executing large-scale transitions to cloud and IP-native operations.
Recent company-level developments—SKU introductions that emphasize 100G and SMPTE-2110 outputs, strategic acquisitions to combine optics and systems expertise, and lens/telemetry extensions—underline that incumbents are jockeying for platform-level differentiation rather than competing on single-product features alone.
Strategic implications by stakeholder
-
OEMs and product leaders — Prioritize system interoperability, certify for emergent IP transport standards, and architect modular upgrade paths. Differentiation through optics and imaging pipelines will remain a high-value territory—especially where price elasticity is lower (high-end production and rental markets).
-
Systems integrators and broadcasters — Adopt staged migration plans that allow hybrid operation between SDI and IP environments. Invest in staff training and orchestration layers now to reduce switching friction when moving to fully IP-native workflows.
-
Rental houses and production services — Flexibility and rapid refresh matter: a balanced fleet that includes modular cinema bodies, high-resolution capture kits, and broadcast-oriented multi-cam systems will maximize utilization across event and scripted work.
-
Investors and M&A strategists — Acquisition targets that combine optics expertise, IP transport know-how, and cloud-friendly middleware present the most attractive value-creation runway. The market shows room for tuck-ins that fill gaps in interoperability and live production automation.
What the PW Consulting study delivers (practical, decision-ready outputs)
-
Scenario-based revenue models anchored to the 2020–2025 historical cadence and extending through 2032, reflecting multiple adoption curves and input-cost shocks.
-
Supplier risk matrix and mitigation playbook—prioritizing component exposures (storage, optics), recommended sourcing strategies, and cost pass-through sensitivities for contract design.
-
Go-to-market and product roadmaps linked to buyer segmentation, channel economics, and rental versus purchase lifetime value models for 2026 planning cycles.
-
Competitive benchmarking and M&A playbook, including diligence checklists for integration-readiness across imaging pipelines and live-production software stacks.
-
Implementation checklists for IP migration, staff re-skilling timelines, and capital-expenditure phasing to avoid capability gaps during transitional windows.
The “trailer” — what we’re intentionally not disclosing here
In keeping with the report’s role as both a strategic primer and a client-ready deliverable, this overview intentionally omits granular segment-level figures and regional/application splits that materially influence transaction-level decisions. The full study contains the detailed segmentation, scenario spreadsheets, supplier lists, and customer-use case analytics that enable a board-level vote or a capex allocation with confidence. Consider this piece a strategic preview—offering the patterns and implications without publishing the discrete figures that our enterprise clients rely on for execution.
How to use this analysis in Q3–Q4 2026 planning
-
Frame capital allocation decisions against the scenario set—opt for options (modular platforms, firmware-enabled upgrades) that preserve upside if the accelerated-adoption case materializes.
-
Run supplier stress tests now: model component shocks in partnership with procurement to size buffer inventories and evaluate alternative architectures that reduce storage and glass content sensitivity.
-
Accelerate interop certifications and strategic partnerships where IP and 100G workflows matter; the first movers here will capture disproportionate share among large broadcasters and event producers.
For leaders preparing board materials, structuring acquisition diligence, or calibrating product roadmaps for 2026, PW Consulting’s full Digital Broadcast and Cinematography Cameras Market study is designed to be the operational playbook you can act on immediately. The preview above maps the strategic contours—download the full report to access the granular forecasts, supplier matrices, and transaction-level insights required to convert strategy into capture-ready outcomes.
For detailed analysis of this topic, please visit the official page: Digital Broadcast and Cinematography Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com