

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Release Agent Market to Reach USD 3,410 Million by 2032 at 7.17% CAGR
By pmarketresearch, 2026-07-09
Release Agent Market — Strategic Outlook for 2026: Why this PW Consulting Study Matters
As companies finalize their 2026 strategic plans, one seemingly specialized input is emerging as a cross-industry lever for both risk mitigation and growth: release agents. PW Consulting’s new Release Agent Market study — calibrated to a 2025 base year and projecting through 2032 — translates commodity dynamics, regulatory shockwaves, and supplier positioning into an actionable decision framework. This introduction sketches the decision-grade insights you can expect from the full report, while deliberately withholding the granular segmentation tables and proprietary scorecards that we reserve for subscribers. Think of this narrative as the trailer: it demonstrates depth, frames strategic choices, and points you to the full dossier for execution-level detail.
Release Agent Market
Macro trajectory and what it means for 2026 planning
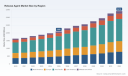
Our updated market model shows a steady enlargement of the global release agent market from an estimated USD 1,631.5 Million in 2020 to USD 2,100.0 Million in 2025. Under our base forecast, the market expands further to roughly USD 3,410.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 7.17% across the projection window. That trajectory is meaningful: it signals robust, sustained demand across food processing, plastics and rubber molding, construction, composites, and specialty industrial applications.
Release Agent Market
For corporate planners, a few implications follow immediately. First, modest-to-strong market growth justifies targeted capacity investments and product development budgets in water-based, bio-based, and carrier-free chemistries. Second, pricing levers will have to accommodate upstream volatility (see raw-material dynamics), while commercial teams should prepare segmented pricing and value-capture frameworks for customers that face their own regulatory headwinds.
Release Agent Market
Regulatory inflection points: the non-negotiable risk
-
European policy is re-shaping product eligibility. Recent EU measures impose higher documentation and migration-testing requirements for food-contact materials and have moved to ban or tightly restrict substances such as certain bisphenols. These changes are not theoretical: they mandate reformulation timelines and create first-mover advantages for suppliers with validated, high-purity technologies.
-
U.S. environmental guidance and state-level restrictions are accelerating adoption of biodegradable formulations in infrastructure applications; we observe double-digit annual growth in some niche biodegradable segments. Firms that ignore this trajectory risk market access problems and reputational costs.
-
Our full report maps the regulatory timelines that matter and translates them into product-compliance deadlines by application. We model enforcement phasing and propose practical remediation roadmaps for product lines that fail to meet upcoming migration and documentation tests.
Raw-material and cost dynamics: tactical playbook for procurement
Commodity pressure is an undercurrent that will determine whether margin expansion accompanies volume growth. Through 2025 we observed a 15–20% rise in oil-indexed costs relative to traditional solvent formulations. That movement is accelerating customer interest in lower-solvent, water-based systems and in substitution with vegetable oils, wax esters, and polymeric carriers where application-appropriate.
Procurement implications are straightforward: hedge raw-material exposure, prioritize dual-sourcing for critical intermediates (siloxanes, specialty esters, food-grade carriers), and push for supplier partnerships that include formula-stability guarantees and raw-material pass-through mechanisms. Our report includes a procurement playbook with supplier negotiation tactics and a sensitivity model that quantifies margin at different oil-price scenarios.
Competitive structure: consolidation with opportunity pockets
The release agent market displays a concentrated competitive structure. The top three players command a substantial share of the market, and the top five occupy an even larger combined footprint — a fact that creates both defensive and offensive imperatives for mid-tier manufacturers and newcomers. High concentration delivers predictable channel dynamics but also increases the strategic value of niche differentiation: food-grade traceability, fast regulatory-compliant reformulations, and application-specific performance claims.
Key supplier profiles covered in the study include established multinationals and specialty players. Highlights:
-
Chem-Trend L.P.: Known for diverse delivery formats, including water-based, solvent-based, and carrier-free systems; recent launches focus on high-pressure aluminum casting solutions with improved operational efficiency.
-
Miller-Stephenson Chemical Co.: Specialist offerings for concrete, rotational molding, and high-temperature applications; strong reputation in industrial-grade specialty chemistries.
-
Henkel AG & Co. KGaA: A global systems provider with a strong foothold in automotive and aerospace applications through established brands and integrated customer programs.
-
Wacker Chemie AG and Shin-Etsu Chemical: Silicon-focused portfolios and an increasing emphasis on food-grade and eco-friendly formulations that align with regulatory trends.
-
Dow Inc. and BASF SE: Broad platform players pushing performance- and sustainability-oriented innovations, including biodegradable and bio-based options for construction and industrial uses.
-
Synova (Bundy Baking Solutions), Marbocote, and Mallet & Company: Niche specialists in bakery/foodservice and precision engineering who are leveraging focused portfolios to win category-specific share.
We analyze these firms across seven strategic dimensions — technology leadership, regulatory readiness, scale advantage, go-to-market capability, pricing power, innovation pipeline, and M&A appetite — and translate that analysis into prioritized engagement strategies for OEMs, distributors, and private equity sponsors.
Innovation vectors and product architecture
Three innovation themes will shape winners in 2026 and beyond: 1) high-purity, traceable chemistries that satisfy tighter food-contact regimes; 2) carrier-free and low-VOC systems that reduce lifecycle environmental impact; and 3) formulation modularity that enables rapid, cost-effective customization for specialty applications (e.g., high-temperature composites, high-throughput bakery lines, and asphalt release agents).
The study provides a technology roadmap that connects R&D investment to near-term commercial outcomes, enabling R&D leaders to prioritize projects with the highest IRR and shortest regulatory-compliance runway.
Actionable content in the full report (what you’ll get)
-
Proprietary market-sizing model (historical 2020–2025, base 2025; forecasts 2026–2032) with scenario toggles for regulatory and raw-material shocks.
-
Supplier scorecards and benchmarking dashboards that quantify competitive positioning across the seven strategic dimensions noted above.
-
Regulatory impact matrix and compliance timetable tailored to food-contact applications and infrastructure segments.
-
Go-to-market playbooks for manufacturers and distributors (pricing strategies, channel segmentation, co-development agreements).
-
M&A target list and diligence checklist for private equity and corporate development teams, including integration risk scoring.
-
Operational playbooks: SKU rationalization guidance, formulation transition blueprints, and plant retrofit costing for water-based production lines.
-
Excel-based sensitivity models and downloadable datasets to integrate into your internal financial planning systems.
Strategic recommendations for 2026 decision cycles
-
Prioritize compliance-driven reformulation programs for food-contact lines. Treat migration testing and documentation as a product feature, not a compliance tax.
-
Accelerate capital allocation toward modular, water-based production capacity where customer demand and regulatory imperatives overlap.
-
Secure strategic raw-material supply through long-term contracts and selective equity or JV arrangements upstream in ester and carrier supply chains.
-
Explore bolt-on acquisitions of niche players with validated food-grade or biodegradable portfolios — these assets create rapid market access and regulatory credence.
-
Deploy scenario planning: run base, regulatory-tight, and raw-material-shock scenarios during Q1 budget reviews and stress-test commercial commitments under each.
Recent developments and what they reveal
-
Product portfolio expansions and new product launches in 2025 reflect vendor responses to both technical demand and regulatory timelines. For example, a leading bakery-focused supplier expanded its Integra portfolio in August 2025 to capture foodservice demand, and Chem-Trend launched a high-pressure casting-specific release agent earlier in 2025. These moves underscore how suppliers are bifurcating investments between performance differentiation and compliance-ready offerings.
-
Market concentration increases the strategic value of partnerships: smaller suppliers can accelerate growth by partnering with or being acquired by scale players that provide distribution breadth and global compliance infrastructure.
Why PW Consulting’s study is decision-grade for 2026
This study is built to connect board-level imperatives to plant-floor actions. It quantifies the market opportunity, models regulatory impact, and provides the tactical playbooks necessary to convert compliance pressure into competitive advantage. Importantly, while this introduction highlights the themes and the implications, the full study contains the granular segmentation, financial tables, supplier scorecards, and downloadable models that operational teams will need to execute through 2026 and beyond.
To preserve the strategic value of our research and to protect the proprietary segmentation and supplier scoring methodology, we intentionally withhold the detailed tables and split-level metrics in this public overview. If you are planning product portfolio moves, plant investments, or M&A activity in 2026, access the full report to obtain the complete datasets, scenario models, and the supplier playbooks necessary to act with confidence.
PW Consulting stands ready to brief executive teams, run customized scenario workshops, and support diligence and integration planning for transactions originating from insights in this study. Contact our Release Agent Market practice to schedule a private walkthrough of the full dataset and to license the modeling tools that power our recommendations.
For detailed analysis of this topic, please visit the official page: Release Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Luggage Rack Market to Hit USD 2,247 Million by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-09
Car Luggage Rack Market 2026 — Strategic Briefing for Executive Decision‑Making
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a concise, decision‑focused orientation to our full Car Luggage Rack Market study. This briefing is designed to surface the evidence you need to set priorities in 2026 — product roadmaps, channel investments, regulatory preparedness, and M&A screening — while reserving the granular segment tables and company‑level revenue splits for the full report. Consider this a high‑resolution trailer: deep on trends and implications, intentionally light on the exact segment tabulations to prompt direct access to the complete intelligence package.
Car Luggage Rack Market
Executive snapshot
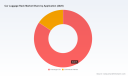
The Car Luggage Rack market completed a robust recovery through 2025 after pandemic‑era disruption. Our base year is 2025, and the report covers historical performance from 2020–2025 with a forward view to 2032. The global market in 2025 is measured at USD 1,560 Million (revenue, USD Million), and the forecast period 2026–2032 uses a central CAGR of 5.5%. Under our base scenario the market grows steadily across the forecast window, underscoring both renewal demand from OEM and aftermarket channels and an expanding set of use cases tied to electrification and outdoor mobility lifestyles.
Car Luggage Rack Market
Why this research matters to executives in 2026
- Prioritization under bounded resources: the study translates macro growth into product and channel priorities so you can allocate engineering, certification, and commercial budgets where ROI is highest.
- Regulatory and certification risk control: emerging NHTSA/IIHS and EU mandates materially shift product requirements — our analysis quantifies compliance cost exposure and time‑to‑market implications.
- M&A and partnership scouting: with moderate concentration at the top of the market, the report identifies strategic buyer/seller archetypes and value levers for inorganic growth.
- Commercial execution templates: practitioners will find go‑to‑market playbooks for premium OEM fitment, scaled aftermarket rollouts, and subscription-based asset monetization.
Key market dynamics shaping 2026 strategy
Several converging dynamics are setting the agenda for near‑term corporate action:
Car Luggage Rack Market
- Electrification and aerodynamics: As EV penetration increases, aerodynamic drag penalties and range impact are now central to product specification. Leading suppliers have already redesigned roof boxes and platforms to minimize efficiency losses — and buyers are willing to pay a premium for EV‑optimized solutions.
- Premiumization and multi‑activity use: Consumers are buying higher‑value, multi‑functional carriers (bike, ski, watersport) that emphasize quick interchangeability and tool‑less installation. This shifts competition from simple commodity racks to integrated systems and accessories ecosystems.
- Aftermarket versus OEM channel dynamics: OEM factory fitment remains strategically attractive because it embeds lifetime warranties and integration validation, whereas the aftermarket continues to scale through digital retail and subscription offerings that lower adoption barriers.
- Supply chain and materials: Lightweighting (aluminum, composite hybrids) and emissions‑aware manufacturing are differentiators. Suppliers that can demonstrate lower embodied emissions and predictable cost inputs will win OEM and fleet contracts.
- Regulatory tightening: Recent protocol updates are not peripheral — they mandate that racks remain installed during structural testing and require continuous certification for load capacity and aerodynamic performance, changing both product development cycles and warranty risk profiles.
Regulatory and testing considerations (operational impact)
Regulatory developments have moved from a compliance cost to a strategic gate. Authorities and testing bodies have increased the scrutiny of roof‑mounted accessories:
- NHTSA and IIHS roof strength protocols now explicitly require that roof racks remain installed during vehicle structural tests — this raises potential liability if racks contribute to structural compromise.
- Continuous certification requirements for aftermarket load capacity and aerodynamic performance (noted in US sector analyses) mean companies must invest in recurrent testing and retain design margins to accommodate evolving protocols.
- The EU General Safety Regulation harmonizes aftermarket accessory compliance across member states, raising the bar for cross‑border aftermarket distribution.
For product and compliance leaders, the implication is clear: make certification, test capacity, and traceable material sourcing founding elements of your 2026 product roadmap.
Competitive landscape — focal players and strategic moves
The market shows a moderate degree of concentration with the three largest players holding a meaningful share and the five largest approaching a clear majority presence. This structure supports both scale plays and profitable niche strategies.
- Thule Group AB (Malmö, Sweden) — a global leader in premium roof boxes, bike carriers, and integrated systems. Thule’s recent launches underscore a product strategy focused on aerodynamic integration and emissions reduction: in 2025 Thule introduced an upgraded Force 3 roof box optimized for EV efficiency and the Xscape cargo rack emphasizing lower emissions and reduced weight. Prior launches include the Motion 3 and the high‑capacity ReVert bike carrier. These moves reveal Thule’s dual play of product differentiation and sustainability credentialing.
- Yakima Products, Inc. (Vashon Island, Washington, USA) — specializes in crossbars, roof racks and cargo carriers, with a strong aftermarket channel presence and innovator reputation for mounting flexibility and accessory ecosystems.
- Rhino‑Rack (Australia) — focuses on heavy‑duty roof platforms and off‑road solutions, serving adventure vehicle niches and fleet segments that require robustness and modularity.
Notable independent innovations include Prinsu Design Studio’s 2025 demonstration of a sunroof‑compatible rack for specific SUVs — an example of how small, agile players can unlock new fitment use cases and attract OEM attention.
What the full report delivers — actionable modules
The full PW Consulting study is structured for immediate operationalization. Key modules include:
- Market sizing and trend analysis (historical 2020–2025, base year 2025, forecast 2026–2032) with sensitivities around fuel price, EV adoption, and outdoor recreation indices.
- Demand model and downloadable Excel workbook — ingredient‑level forecasts by type, application and region (note: detailed segment tables are reserved for the full report).
- Product benchmarking and feature matrix — aerodynamic coefficients, weight, materials, installation time, warranty exposure, and certification status.
- Regulatory and test matrix — mapping of NHTSA, IIHS and EU requirements to product design checkpoints and recommended test plans.
- Go‑to‑market playbooks — OEM partnership templates, aftermarket channel scaling (digital retail and subscription), and service/installation network design.
- Supply chain diagnostics — supplier map, cost‑to‑serve analysis, and decarbonization levers for manufacturing footprints.
- M&A and partnership screen — buyer/seller archetypes, valuation sensitivities, and integration risk checklist informed by current market concentration dynamics.
- Primary interviews and supplier due diligence summaries — insights from OEM procurement, fleet managers and specialty aftermarket retailers.
How to use these insights in 2026 — practical recommendations
- Make aerodynamic validation compulsory for all EV‑market product signoffs. Small drag reductions translate to measurable range gains and compelling marketing claims.
- Prioritize lightweight composite and multi‑material designs where lifecycle emissions and load capacity interplay favor premium pricing and OEM fitment.
- Build or partner for certification capability. Recurrent testing and traceable documentation will be a commercial barrier for competitors that lack in‑house resources.
- Segregate product lines by route‑to‑market: tailor OEM platforms for integration and warranty terms; design modular, easy‑install kits for the direct‑to‑consumer channel.
- Screen M&A targets by strategic fit to three vectors: engineering capability (aero/composites), distribution reach (digital/install network), and certification assets (test labs/documentation).
- Establish a subscription or service offering in select markets to monetize seasonality and reduce upfront purchase friction.
Limitations and next steps — how to obtain the full intelligence
This briefing intentionally omits the granular regional and application revenue splits, and specific segment dollar tables — those detailed tables, the complete Excel demand model, company revenue profiles, and primary interview transcripts are available only in the full PW Consulting report and client deliverables. The full package includes scenario variants (accelerated EV adoption, supply chain disruption, premiumization pivot) and a ready‑to‑use strategic dashboard for board‑level presentation.
If your 2026 plan requires prioritized initiatives — whether a product refresh for EVs, an OEM partnership negotiation, or a targeted acquisition screen — the full report will convert this briefing into executable next steps, with quantified investment requirements and downside risk tolerances. Contact PW Consulting for access to the complete study, model, and a tailored executive workshop to translate findings into your operational plan.
Prepared by PW Consulting — Senior Strategic Advisor & Chief Industry Analyst. The full Car Luggage Rack Market study provides the tables and underlying data that underpin the observations in this briefing. Use this note to align leadership discussion; use the full report to commit capital and operational resources in 2026.
For detailed analysis of this topic, please visit the official page: Car Luggage Rack Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Briquette Market 2026: Strategic Imperatives for Decision Makers
As the global energy and recycling landscape shifts, briquettes have moved from niche fuel and recycling solutions to a strategically important product at the intersection of decarbonization, waste valorization, and distributed energy. PW Consulting’s forthcoming Briquette Market study—anchored on 2025 as the base year and projecting through 2032—translates market dynamics into actionable strategy for executives planning capital allocation, sourcing, and go-to-market moves in 2026 and beyond.
Briquette Market
Market snapshot: growth trajectory and what it means
-
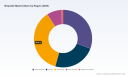
Momentum: The briquette market has expanded materially over the last half-decade. From a market size of approximately USD 4.5 Billion in 2020, the sector reached roughly USD 6.5 Billion in 2025 and is projected to grow to around USD 10.7 Billion by 2032—an implied compound annual growth rate (CAGR) of about 7.2% across the forecast horizon.
Briquette Market -
Interpretation: This trajectory reflects a convergence of drivers: higher commodity and energy prices that increase interest in lower-cost, high-density fuels; stronger circular-economy mandates that favor waste-to-energy pathways; and targeted policy support that lowers the total cost of equipment ownership for new entrants and existing operators alike.
Briquette Market -
Competitive environment: The industry remains relatively fragmented—market share is dispersed across equipment OEMs, regional machine builders, and local feedstock consolidators—creating pockets of opportunity for scale operators, specialized technology providers, and vertically integrated players.
Why the 2026 decision window is pivotal
-
Capital cycles: Many countries implemented capital subsidy programs and incentive schemes through 2025 that materially reduce upfront equipment costs. With several of these programs entering new phases or sunset clauses in 2026, organizations that finalize investment cases and procurement strategies early in 2026 are best positioned to capture favorable financing and subsidy stacks.
-
Feedstock dynamics: Seasonal and regional variability in agricultural and forestry residues creates first-mover advantage for organizations that secure long-term feedstock contracts, invest in preservation and storage, and design flexible production lines capable of handling variable moisture and particle sizes.
-
Compliance and product standards: Recent regulatory attention—both in environmental discharge rules and product standards—means compliance-ready designs and third-party certification will be procurement differentiators. Firms that embed compliance and traceability into their product and operations roadmap in 2026 will lower time-to-market and reduce regulatory friction.
What the PW Consulting Briquette Market study delivers (practical, operational, decision-ready)
-
Robust market sizing and scenario forecasting: A historical series (2020–2025) and probabilistic forecasts (2026–2032) that quantify upside and downside scenarios under varying price, subsidy, and feedstock availability assumptions.
-
CapEx / OpEx playbooks: Unit economics and plant-level models (modifiable by throughput, feedstock cost, and energy price inputs) to generate project IRR, payback, and sensitivity tables suitable for board-level investment memos.
-
Supply chain and procurement toolkit: Supplier scorecards, negotiation checklists, and modular procurement templates calibrated for equipment types (mechanical, hydraulic, screw/stamping) and for buyers targeting small, medium, or industrial scale output.
-
Regulatory and compliance compendium: A practical checklist linking key regulatory developments to equipment specs, effluent and emissions monitoring, and product testing (including national standards that affect product grading and market access).
-
Commercial go-to-market playbooks: Channel strategies, pricing archetypes, contracting templates for offtake, and service / spare-parts revenue models designed to accelerate payback.
-
Interactive data appendices: Granular, queryable datasets and regional dashboards that let users slice the market by geography, feedstock dynamics, and application demand—available only in the full report to protect competitive insights and to enable customizable client engagements.
Competitive landscape: how to read vendor positioning
The briquette equipment ecosystem is diverse: from precision mechanical presses to high-tonnage hydraulic systems and integrated processing lines that include shredders, dryers, and control systems. Key vendor archetypes and strategic implications include:
-
Specialized European OEMs (engineering-led): Companies with long histories in heavy-duty briquetting equipment bring high reliability and proven throughput performance. Their machines are often chosen for large industrial installations where uptime and durability justify higher capital intensity. These vendors are attractive partners for projects prioritizing longevity and process integration.
-
Integrated recyclers and machinery providers: Firms offering full lines—shredders to presses—enable faster project deployment and single-supplier accountability. Their value proposition is especially compelling for circular economy projects that must manage mixed-waste feedstock and require turnkey delivery.
-
High-volume, cost-competitive Asian manufacturers: These suppliers deliver competitive pricing and flexible machine types (screw, stamping) suitable for rapid deployment across distributed sites. They are often preferred in cost-sensitive markets and for quick scale-up strategies.
-
Regional specialists and system integrators: Local players supply tailored solutions adapted to domestic feedstock characteristics, regulatory regimes, and service models. Partnering with these firms can dramatically shorten deployment cycles and increase local procurement eligibility for subsidy programs.
Recent market signals underline these dynamics: a UK-based manufacturer showcased advanced biomass models with live demos in mid-2026, signaling both product maturity and market activation at trade events—an important lead indicator for near-term procurement cycles.
Strategic playbook for 2026—what leaders should do now
-
Run multiple capex scenarios now: Use the 7.2% baseline growth and the report’s plant-level models to stress-test IRR at various subsidy, feedstock-cost, and product-price assumptions. Prioritize projects that remain attractive across conservative scenarios.
-
Secure feedstock and logistics: Negotiate multi-year supply agreements with clause mechanisms for seasonality and quality variance. Consider near-site pre-processing or densification hubs to stabilize raw-material input.
-
Pursue strategic equipment partnerships: Select at most two primary equipment partners—one engineering-focused OEM for industrial lines and one cost-efficient supplier for distributed sites—to balance performance and price.
-
Leverage subsidy windows and blended finance: Structure deals to capture capital subsidies and combine local concessional finance with supplier credit. Include service contracts to create annuity-like revenue for financiers and to increase bankability.
-
Embed compliance and certification into product development: Anticipate regulatory coverage tied to industrial effluent and product standards by designing quality assurance and traceability protocols upfront.
-
Explore M&A and partnership targets: Look at regional consolidators with feedstock aggregation, small-scale machine builders, and service networks that can accelerate market entry and shore up logistics.
Risks, regulation, and near-term disruptors
-
Regulatory scope expansion: Recent regulatory notices explicitly bring briquetting-related operations under industrial effluent frameworks in certain sectors. This raises compliance costs and monitoring requirements for metallurgical and heavy-industrial briquetting applications—factors that should be in any O&M budget and permitting timeline.
-
Subsidy uncertainty: While generous capital incentives have supported uptake, policy cycles can change quickly. Treat subsidies as upside in base-case models and build break-even cases without full subsidy reliance.
-
Feedstock seasonality and quality: Variability in biomass availability affects throughput, product consistency, and margins. Investments in drying, storage, and preprocessing pay dividends by stabilizing yield and calorific value.
-
Standards and market access: National product standards that set moisture, density, and calorific thresholds will influence market share for different briquette types. Certification and testing capacity should be part of market-entry planning.
How PW Consulting’s study supports your 2026 plan
-
Decision-ready outputs: Customized financial models, supplier negotiation scripts, and regulatory checklists aligned to the 2026 procurement calendar.
-
Benchmarking intelligence: Comparative equipment performance and total-cost-of-ownership analyses that feed directly into vendor selection and tender specifications.
-
Execution playbooks: Step-by-step project plans—from feedstock sourcing to commissioning—tailored to different scale points (distributed, SME, industrial).
PW Consulting’s Briquette Market report is intentionally crafted as a strategic bridge between market intelligence and execution. The full study contains the granular regional and application breakdowns, cost matrices, and interactive data tables that executives and investors need to finalize go/no-go decisions in 2026. This introduction outlines the strategic imperatives—download the full report to access the detailed datasets, vendor scorecards, and plant-level economics that will operationalize your next moves in this dynamic sector.
For detailed analysis of this topic, please visit the official page: Briquette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: L-Alanine Market to Reach USD 236.82M by 2032, Growing at 5.69% CAGR
By pmarketresearch, 2026-07-09
L‑Alanine Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision‑centric preview of the L‑Alanine market designed to inform executive choices in 2026. This briefing synthesizes observed market momentum, regulatory inflection points, supply‑chain dynamics, and the competitive posture of incumbent producers. It highlights the strategic value of our full market study while intentionally withholding the granular subsegment tables and detailed numeric splits — a deliberate “trailer” approach to motivate access to the complete report for transaction‑level and operational planning.
L-Alanine Market
Why this matters for 2026 decision cycles
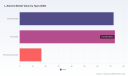
Between 2020 and 2025 the global L‑Alanine market moved from an established base to a materially larger, more diversified demand pool. Our base‑year sizing (2025) and the forecast through 2032 show a clear expansionary trajectory, supported by a compound annual growth rate of 5.69% across the 2026–2032 forecast window. To put the scale of change into context: the market grew steadily through the early 2020s and continues to scale through the end of the forecast horizon, reflecting structural demand shifts in nutrition, clinical/medical applications, and select industrial uses.
L-Alanine Market
For corporate leaders, procurement heads, product managers, and M&A teams, this trajectory translates into actionable implications in 2026: decisions taken this year on capacity, qualification of alternative feedstocks, regulatory risk mitigation, and partner selection will determine cost of goods, time to market, and pricing power well into the next decade.
L-Alanine Market
What our full PW Consulting L‑Alanine study delivers
- Robust market sizing and forward projections (2026–2032) built on bottom‑up demand modeling and supply capacity mapping, including scenario stress tests under alternative raw material and regulatory assumptions.
- Practical go‑to‑market playbooks for producers and formulators — covering qualification timelines for medical and food applications, pricing tier strategies, and commercialization roadmaps for new grades (e.g., high‑optical purity, pharmaceutical grades).
- Supply‑chain heatmaps that identify one‑to‑two step substitution pathways, raw material exposure, and logistics choke points relevant for contracting and inventory strategy.
- Competitive benchmarking with capabilities matrices (fermentation vs chemical synthesis, certification footprints, geographic production, and product grade portfolios), and a prioritized list of acquisition/investment targets.
- Regulatory risk matrix and mitigation playbook tailored to EP/USP/JP monographs, medical nutrition approvals, and GMP/quality assurance regimes.
- Practical capital allocation guidance covering greenfield vs brownfield expansion, estimated payback horizons under conservative demand scenarios, and sensitivity analysis for raw‑material price shocks.
Note: while this preview summarizes the nature of the granular analysis, the detailed split tables by region, application, and grade (which inform procurement-level decisions and valuations) are intentionally not reproduced here and are available in the full report.
Market dynamics: drivers, constraints and near‑term inflection points
- Structural demand drivers: The convergence of clinical nutrition growth, rising demand for specialized food and beverage formulations, and incremental use in specialty industrial formulations is sustaining above‑average growth. These drivers are durable and supported by both demographic trends and formulation innovation.
- Production economics: Fermentation‑based manufacturing using renewable sugar feedstocks continues to lower cost per unit versus some chemical synthesis routes. This dynamic is reshaping cost curves and is a decisive factor for new capacity investment and supplier selection.
- Regulatory enablers and scrutiny: L‑Alanine’s inclusion in major pharmacopeias and its status as an approved non‑animal‑derived amino acid for medical and enteral nutrition open higher value routes to market. At the same time, regulatory scrutiny remains material — firms must maintain rigorous compliance and quality systems to avoid operational disruptions.
- Market concentration and competition: The market displays moderate concentration among leading producers. That concentration creates both opportunities for niche entrants (by focusing on high‑purity grades or differentiated service models) and risk for buyers relying on limited qualified sources.
- Sustainability and ESG: Credible sustainability credentials are becoming a procurement prerequisite. Recent supplier certifications and public sustainability disclosures materially influence contract outcomes and price premia.
Competitive landscape: profile, posture and near‑term moves
The competitive set comprises established fermentation specialists, diversified chemical and ingredient players, and regional synthetic‑biology manufacturers. Below is a synthesis of the strategic positioning of five representative companies, distilled for readers evaluating partners, acquisition targets, or competitive threats.
- Ajinomoto Co., Inc. (Japan) — A global fermentation leader with deep expertise in both pharmaceutical and food‑grade amino acids. Strengths include global supply chains, brand trust in nutrition and clinical markets, and an integrated approach to R&D and process optimization. Strategic implication: Ajinomoto is a natural partner or acquiror for firms seeking rapid geographic scale and validated quality footprints.
- Evonik Industries AG (Germany) — Positions itself as a supplier of non‑animal‑derived grades compliant with EP/USP/JP, servicing medical nutrition, infant formula, and biopharma segments. Strengths include regulatory alignment and portfolio breadth. Strategic implication: buyers targeting institutional or clinical channels should prioritize qualification of Evonik and similar, pharmacopeia‑compliant suppliers.
- Kyowa Hakko Bio Co., Ltd. (Japan) — A fermentation specialist focused on high‑purity amino acids for pharmaceutical and nutritional markets. While a respected player, prior regulatory interactions underscore the importance of compliance transparency when engaging with the company. Strategic implication: deep due diligence is recommended where regulatory histories affect qualification timeframes.
- Anhui Huaheng Biotechnology Co., Ltd. (China) — A synthetic‑biology oriented producer active across animal and human nutrition, personal care, and intermediates. Recent product communications on related feed solutions and an EcoVadis Silver recognition reflect an aggressive product and sustainability messaging strategy. Strategic implication: AHB represents a competitive, cost‑competitive alternative, especially for regional buyers and specialty feed applications; its sustainability credentials make it a more attractive counterparty for ESG‑minded procurement teams.
- SINOGEL Amino Acid Co., Ltd. (China) — A specialist manufacturer offering multiple grades (technical, high‑optical purity, food). Strategic implication: SINOGEL is well positioned to serve downstream formulators seeking multiple grade options and flexible commercial terms, particularly where speed to market is critical.
Collectively, these players demonstrate differentiated routes to market: global integrated suppliers capture institutional clinical demand; regional synthetic‑biology specialists compete on price, flexibility and niche innovation; and companies with strong certification narratives extract pricing premium and faster qualification in regulated channels.
Recent operational and regulatory signals to watch in 2026
- New product communications and application notes from synthetic‑biology producers are expanding use cases (e.g., aquaculture feed formulations and amino acid health information). These moves are classic demand‑creation plays that precede volume adoption and should prompt procurement to trial offshore alternatives early.
- Third‑party sustainability certifications (e.g., EcoVadis Silver) are emerging as commercial differentiators in supplier selection; companies without a credible sustainability narrative will face longer tender cycles and potential price concessions.
- Regulatory interactions — including any close‑out communications or warning letters related to amino acids manufacturing — materially affect supplier qualification lead times. Buyers and investors should flag such histories as a non‑trivial part of counterparty risk assessments.
Practical strategic playbook for 2026
- Prioritize supplier qualification for at least two pharmacopeia‑aligned producers if entering medical or infant nutrition channels; expect multi‑quarter timelines.
- Hedge raw‑material exposure by locking multi‑year sugar or carbohydrate feedstock agreements where fermentation pathways dominate your cost base.
- Pursue targeted capex in fermentation optimization (yield, titer, downstream recovery) rather than broad capacity expansion; small efficiency gains are highly accretive given the projected CAGR.
- Embed regulatory diligence early in M&A and sourcing processes — public regulatory notices materially change valuation and timeline assumptions.
- Make sustainability credentials (third‑party audits, carbon intensity reporting) a gating criterion for strategic suppliers; this reduces tender friction and preserves pricing leverage.
- Run three scenario‑based models for any investment decision: conservative (lower adoption), central (market CAGR reflected), and aggressive (accelerated specialization adoption); use these to stress test NPV and payback assumptions.
Final takeaways — the strategic value of the full report
For 2026 strategic planning, the L‑Alanine market presents a balanced opportunity set: predictable, mid‑single‑digit CAGR growth with clear pathways to higher‑value segments via regulatory compliance, grade differentiation, and sustainability positioning. The tactical decisions you make this year — which suppliers to qualify, what production technologies to invest in, how to structure long‑term feedstock contracts, and which potential targets to pursue — will compound over the forecast window.
PW Consulting’s full market study contains the detailed segmentation tables, supplier scorecards, unit‑cost models, and contract templates that convert the insights above into executable programs. To maintain the integrity of commercial planning and to encourage a fact‑based procurement process, we have withheld the granular numeric splits from this preview. Access the complete intelligence on our report page to obtain the subsegment allocations, regional flows, and downloadable financial models that support transaction execution and operational planning.
Should you wish to discuss how these insights translate to a bespoke readiness assessment, supplier due‑diligence program, or acquisition screening tailored to your organization, PW Consulting stands ready to convert market clarity into measurable decisions.
For detailed analysis of this topic, please visit the official page: L-Alanine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Food Leavening Agents: Asia Pacific Tops at $360.17M, Market to Reach $998.41M by 2032 (3.8% CAGR)
By pmarketresearch, 2026-07-09
Food Leavening Agent Market — Strategic Preview for 2026 Decision-Makers
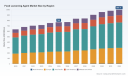
As the global food industry recalibrates for the post‑pandemic recovery and rising consumer demand for convenience and premium baked goods, the food leavening agent market is transitioning from steady commodity dynamics to an innovation‑led, channel‑sensitive growth phase. PW Consulting’s latest research (base year 2025) tracks a clear macro trajectory: the market expanded from an estimated USD 638.17 Million in 2020 to roughly USD 769.0 Million in 2025 and is forecast to approach approximately USD 998.4 Million by 2032, driven by a projected compound annual growth rate (CAGR) of 3.8% across the 2026–2032 forecast window.
Food Leavening Agent Market
Why this study matters for 2026 strategy
-
Decision clarity in a crowded field: With mid‑single‑digit CAGR and uneven growth pockets across product types and channels, executives must choose between efficiency plays (scale and commodity sourcing) and differentiation (clean‑label, specialty yeasts, premixes).
Food Leavening Agent Market -
Timing investments: 2026 is a tipping point year for capacity and product investments. Our report aligns operational timing with demand inflection points and regulatory timelines so capital deployments are synchronized with market uptake.
Food Leavening Agent Market -
Regulatory and raw‑material shocks: The interplay of organic standards, GRAS classifications, and sourcing constraints for bicarbonates and ammonium salts requires integrated risk mitigation across procurement, formulation, and labeling.
Market trajectory and structural signals
The market’s steady baseline growth is underpinned by two parallel forces. First, volume growth in industrial and in‑store bakery channels is being supplemented by premiumization — demand for clean‑label premixes, specialty yeasts, and formulation innovations that improve shelf quality and texture. Second, supply‑side consolidation and scale advantages are generating a concentrated landscape: the top three firms capture a materially high share of the market, with the top five firms commanding an even larger portion—an important structural consideration for entrants and mid‑tier suppliers contemplating M&A, distribution partnerships, or co‑manufacturing agreements.
These structural signals mean that price competition will remain intense in commodity segments (standard bicarbonates and basic chemical leaveners), while margin expansion opportunities will exist in proprietary blends, instant dry yeasts, and specialty premixes serving artisanal and foodservice customers.
Segmentation lens (selective—high level)
-
Type dynamics: The market comprises chemical, biological (yeast‑based), and physical leavening solutions. Chemical leaveners continue to dominate volumes due to broad utility and low cost, while biological solutions are the fastest area for product innovation and clean‑label marketing.
-
Application pathways: Core applications include traditional bakery categories such as bread, biscuits/cookies, cakes/pastries, and rolls/pies. Each application reflects distinct formulation needs, procurement cadences, and shelf‑life considerations—factors we map precisely in the full report.
-
Regional implications: Growth pockets vary by cluster—mature markets emphasize process efficiency and clean labeling, while developing markets are driven by rising retail penetration and industrialization of baking. For confidentiality of competitive segmentation, the report’s granular regional and channel splits are reserved for subscribers.
Competitive landscape — who matters and why
The leavening agent ecosystem mixes global ingredient majors, specialized yeast houses, and regional brand incumbents. Market concentration metrics indicate a high share held by the leading players, making strategic positioning around channel control, brand reputation, and formulation IP critical.
-
Large agribusiness and ingredient players (e.g., major processors of sodium and ammonium bicarbonate) provide scale, strong logistics, and cost advantage for commodity leaveners. These firms are natural suppliers to industrial bakers and premix producers.
-
Specialized yeast manufacturers and baking ingredient houses emphasize technical collaboration with bakers, R&D for premixes, and service models (product training, formulation support). These firms are where the market’s highest margin innovation typically originates.
-
Regional brands and legacy names continue to capture retail trust and home‑baker demand; their brand equity enables price premiums in specific channels.
Key companies profiled in our landscape include leading global yeast and baking ingredient suppliers, household baking brands, and diversified ingredient processors. Each profile includes strategic positioning, product portfolios, route‑to‑market analysis, recent corporate developments, and likely next‑move scenarios for 2026–2028. Noteworthy recent developments captured in the study include the commissioning of new specialty yeast capacity by a major yeast producer in 2026 and targeted product launches in selected markets in 2025—both of which have immediate ramifications for supply, pricing and innovation cycles.
Regulatory and raw‑material dynamics — actionable risk factors
-
Raw materials: Ammonium bicarbonate and sodium bicarbonate remain foundational to formulations across pancakes, biscuits and muffin categories. Their availability, quality specifications and handling requirements are assessed in the report’s procurement risk module.
-
Regulatory guardrails: Several leavening agents and supporting substances have explicit regulatory treatments that affect labeling eligibility in organic and processed organic claims. For example, certain ammonium salts are permitted only under specific organic program provisions until regulatory reassessment dates; parallel GRAS affirmations and allowed uses exist for bicarbonates.
-
Packaging and shelf‑life: Commodity storage practices and packaging decisions (e.g., baking soda shelf life under standard handling) materially affect inventory turns and obsolescence risk for manufacturers and distributors.
Our regulatory module cross‑maps these constraints to product portfolios and go‑to‑market claims, enabling legal and regulatory teams to prioritize reformulation or labeling changes before market or compliance breaches occur.
What the full report delivers (practical, executable content)
-
Market forecast model: Scenario‑based projections to 2032 with sensitivity levers for raw‑material shocks, regulatory changes, and adoption rates of clean‑label alternatives.
-
Demand segmentation toolkit: Channel and application demand drivers, buyer personas, and unit economics for industrial vs. artisan segments (note: our publicly circulated preview omits granular regional and application revenue splits—these are available in the subscriber dataset).
-
Supplier scoring and sourcing playbook: Comparative supplier heatmaps, cost benchmarking, and negotiation tactics to secure bicarbonates and specialty yeast supply under variable lead times.
-
Product and innovation roadmap: Priority product concepts, estimated development timelines, and go‑to‑market positioning for clean‑label premixes and high‑purity leavening blends.
-
M&A and partnership playbook: Acquisition targets, valuation heuristics, and integration checklists for buyers seeking to consolidate mid‑market manufacturing or to enter high‑growth specialty segments.
-
Regulatory watchlist and contingency plans: A rolling calendar of regulatory review dates, labeling risks, and recommended compliance actions mapped to product lines.
Strategic priorities for 2026 — an executive playbook
-
Prioritize margin expansion in specialty products: Shift R&D and commercial resources toward yeast‑based and clean‑label premixes where technical support and brand partnerships can protect margins.
-
Secure upstream inputs with flexible contracts: Hedge exposure to bicarbonate availability by diversifying suppliers and incorporating volume‑based pricing triggers; consider strategic inventory for peak seasons.
-
Pursue targeted capacity moves: Use selective capex or tolling arrangements to accelerate time‑to‑market for specialty blends—especially where regulatory labeling windows create temporary market access advantages.
-
Deploy channel segmentation: Separate commercial strategies and KPIs for industrial bakers, artisan/professional bakers, and home‑use retail channels. Tailored packaging, logistics, and training programs improve uptake and stickiness.
-
Prepare for regulatory shifts: Assign cross‑functional owners to monitor organic labeling windows and GRAS‑related updates that could affect product eligibility and marketing claims.
-
Evaluate consolidation opportunities: Given the market concentration of leading players, mid‑tier firms should consider bolt‑on acquisitions or exclusive distribution partnerships to build scale quickly.
How to use this intelligence
Leaders in procurement, R&D, corporate development and commercial functions will find immediate value in the report’s intersectional insights—combining demand forecasts, supplier risk mapping, and innovation roadmaps into executable quarter‑by‑quarter plans. We designed the deliverables so that a CPG product lead can move from insight to pilot in 90 days, and a corporate development team can prepare an acquisition thesis within 60 days.
Note on data scope: this preview purposely surfaces strategic conclusions and macro metrics (including market size trajectory and concentration indices) while withholding detailed revenue splits across regions, product sub‑types and applications. These granular datasets and interactive models are available in the full report package and are essential for granular investment decisions, pricing models, and go‑to‑market allocation.
Next steps
-
Request the full dataset and interactive forecast model to run custom scenarios for your portfolio.
-
Schedule a strategy workshop with PW Consulting to translate findings into a 12‑month action plan tailored to your position in the value chain.
-
Engage our M&A advisory team to explore consolidation targets and valuation frameworks aligned with the market’s concentration dynamics.
For access to the complete Food Leavening Agent Market study—including the subscriber‑only regional and application revenue matrices, supplier scorecards, and an editable scenario model—visit the PW Consulting report page or contact our industry team to arrange a confidential briefing.
For detailed analysis of this topic, please visit the official page: Food Leavening Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: Polymer-Based TIM Market at USD 793.9M in 2025
By pmarketresearch, 2026-07-09
Polymer-Based Thermal Interface Materials (TIM) Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
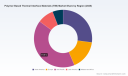
As thermal management requirements tighten across electronics, automotive electrification and heavy infrastructure, polymer-based thermal interface materials (TIMs) are at the intersection of materials science, supply‑chain risk and regulatory change. Our PW Consulting study — grounded in audited historicals (2020–2025) and forward-looking scenarios (2026–2032) — shows a market that expanded from USD 688.15 Million in 2020 to USD 793.9 Million in 2025 and is forecast to grow at a modest compound annual growth rate (CAGR) of 2.27% through the 2026–2032 window, reaching roughly USD 932.8 Million by 2032. This measured growth masks considerable complexity: concentrated supplier positions, raw‑material volatility, accelerating regulation on recyclability and emissions, and shifting end‑market dynamics that will define winners and losers in 2026 and beyond.
Polymer Based Thermal Interface Materials (TIM) Market
Why this report matters for 2026 strategic choices
-
Investment and capacity planning: A low-to-moderate aggregate growth rate forces a choice between pursuing share through differentiation or competing on cost. Capex and capacity decisions must be informed by granular demand scenarios rather than headline growth alone.
Polymer Based Thermal Interface Materials (TIM) Market -
Margin protection vs. market share: Stable revenue growth conceals episodic cost shocks (notably in silicone feedstocks). Procurement and product-pricing strategies designed for volatility will be discriminating advantages.
Polymer Based Thermal Interface Materials (TIM) Market -
Regulatory timetables will re‑shape product roadmaps. New EU rules on recyclability and restrictions accelerating adoption of halogen‑free and low‑VOC formulations create both compliance risk and first‑mover opportunities for suppliers who can reformulate quickly.
-
Competitive consolidation and partner plays: The market structure is concentrated — the top three suppliers account for roughly 62.4% of industry revenues and the top five about 74.2% — creating a landscape where strategic partnerships, co‑development agreements and selective M&A can materially change competitive trajectories.
Report contents — practical intelligence we provide
-
Validated market sizing and multi‑scenario forecasts (2026–2032) with demand drivers and downside/upside sensitivity analyses calibrated to component lead times and end‑market cycles.
-
End‑to‑end supply‑chain mapping and cost‑to‑serve models that translate raw‑material price moves into impact on gross margin by product family and customer segment.
-
Regulatory impact matrix and compliance roadmaps for EU and major markets, including product reformulation windows and estimated compliance cost ranges.
-
Competitive benchmarking: capability heatmaps, technology positioning, commercial footprints and an M&A playbook prioritizing targets by strategic fit and integration risk.
-
Commercial playbooks and procurement negotiation templates, designed for OEMs, contract manufacturers and TIM suppliers to optimize contract length, price escalators and pass‑through clauses under volatile raw‑material regimes.
-
Technology and product roadmaps that align performance (thermal resistance, compressibility, outgassing, lifetime) with regulatory constraints and manufacturing cost levers.
Market dynamics shaping 2026 decisions
-
Raw‑material volatility: Early 2026 saw a sharp uptick in silicone prices (approximately +28%) and a roughly +15% increase in silicon metal feedstock costs (Semitech Insights, March 2026). These spikes materially alter cost curves for silicone‑based TIMs and compress legacy margins for producers that lack hedging strategies or flexible formulations.
-
Regulatory acceleration: New EU requirements on recyclability and tighter restrictions on halogen content and VOC emissions are not distant possibilities — they are active drivers forcing reformulation timelines and supply‑chain audits (IDTechEx TIM Report, 2026). Suppliers who front‑load compliance testing will avoid retrofit costs and access preference in automotive and hyperscale data center procurement.
-
Customer expectations: OEMs increasingly bundle thermal management specifications with sustainability KPIs and lifecycle cost models. The purchasing decision is shifting from unit price to validated TCO and circularity credentials.
-
Concentration and bargaining power: High concentration amplifies the commercial leverage of tier‑one suppliers but also increases procurement vulnerability for customers that lack alternative validated sources or reformulation capability.
Competitive landscape — strategic profiles
-
Henkel AG & Co. KGaA (Düsseldorf, Germany — https://www.henkel.com) : With established brands and an integrated portfolio spanning gap fillers, phase‑change materials and elastomeric pads, Henkel’s strength is breadth and customer co‑development. Strategic moves to watch: accelerated automotive validation programs and deeper OEM partnerships emphasizing recyclability.
-
3M Company (St. Paul, MN — https://www.3m.com) : A major presence on thermally conductive pads and tapes, 3M leverages scale, adhesive technology and global distribution. Competitive edge lies in application engineering and rapid prototyping for consumer electronics. Vulnerability: cost exposure to polymer feedstocks if hedging is insufficient.
-
Dow Inc. (Midland, MI — https://www.dow.com) : Supplier of advanced silicone‑based TIMs targeting high‑performance electronics, EVs and data centers. Dow’s strengths are materials innovation and vertical integration potential; expect initiatives around silicone performance enhancement and sustainability claims.
-
Parker Hannifin / Chomerics (Cleveland, OH — https://www.parker.com) : Focused on elastomeric pads and gap fillers for aerospace, defense and industrial segments. Parker’s domain expertise in ruggedized applications and qualification cycles is an entry barrier for new suppliers eyeing specialized markets.
-
Shin‑Etsu Chemical (Tokyo — https://www.shinetsu.co.jp) : High‑purity silicone and polymer compound supplier with strengths in semiconductor and electronics applications. Shin‑Etsu’s capabilities support customers requiring tight material specifications and long lifecycle stability.
-
Momentive Performance Materials (Niskayuna, NY — https://www.momentive.com) : Advanced polymer composites and silicone TIMs, competitive in industrial and electronics thermal management; watch for co‑development with OEMs on data‑center thermal solutions.
-
Wacker Chemie AG (Munich — https://www.wacker.com) : Specialist in silicone polymer chemistries, positioned to capitalize on demand for low‑VOC and high‑performance formulations. Strategic focus likely on automotive EV validations.
-
Elkem ASA (Oslo — https://www.elkem.com) : Supplies silicone and polymer TIMs for electronics and industrial apps; strategic advantages include feedstock integration and European supply footprints.
-
Polymer Science, Inc. (Monticello, IN — https://polymerscience.com) : Niche and custom‑focused, serving medical and specialized electronics markets. Their agility for custom formulations can attract clients seeking rapid validation and small‑batch innovation.
Strategic implications and recommended actions for 2026
-
Immediate procurement playbook: Negotiate flexible contracts with price collars and longer‑term volume commitments where appropriate; use our cost‑to‑serve models to determine acceptability thresholds for passing through raw material surcharges.
-
Formulation and R&D priorities: Fast‑track low‑VOC and halogen‑free reformulations targeted at automotive and data centers; invest in recyclability testing to claim early compliance and secure OEM qualification windows.
-
Supply‑chain resilience: Diversify critical feedstock sources, evaluate regional manufacturing to reduce lead times and consider strategic inventory buffers for key silicone intermediates during peak volatility.
-
Commercial differentiation: Build validated sustainability narratives (verified recyclability, lower lifecycle emissions) into product value propositions — customers are increasingly awarding preference to verified circular solutions.
-
M&A and partnerships: Prioritize targets that close capability gaps (e.g., low‑VOC chemistries, validation labs, regional manufacturing) and offer rapid route‑to‑market in regulated segments.
-
Scenario planning: Use the report’s sensitivity modules to stress‑test P&L under alternate raw‑material, regulatory and demand curves; incorporate these outputs into 2026 budgeting and capital allocation decisions.
How to use the study
-
For strategy teams: Translate scenario outputs into a 24‑month roadmap for product, regulatory and capacity investment.
-
For procurement: Leverage supplier benchmarking and cost models to re‑shape sourcing strategies and renegotiate contracts.
-
For R&D and product management: Use the technology roadmaps and test‑matrix templates to sequence reformulation and validation activities aligned to regulatory deadlines.
-
For corporate development: Apply the M&A playbook and target screen to prioritize inorganic growth that accelerates compliance and performance differentiation.
Next steps (teaser)
PW Consulting’s full report contains the granular datasets, validated segmentations by region, type and application, supplier scorecards and downloadable financial models necessary to operationalize the actions above. This briefing has highlighted the strategic signals and recommended plays for 2026 without disclosing proprietary segment‑level figures — for access to the detailed tables, scenario files and supplier heatmaps, consult the full report on our source webpage or contact our advisory team to schedule a bespoke briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Polymer Based Thermal Interface Materials (TIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Residential Portable Generators Market at USD 5.51B in 2025; 7% CAGR through 2032
By pmarketresearch, 2026-07-09
Residential Portable Generators Market: Strategic Preview for 2026 Decision-Making
Executive snapshot
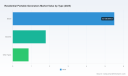
As utilities, homeowners and regulators adapt to a more volatile climate and changing air-quality expectations, the residential portable generators market is entering a phase of steady growth and regulatory re‑sculpting. PW Consulting’s forthcoming market study, grounded on a 2025 base year and a 2026–2032 forecast horizon, quantifies that pathway: after expanding steadily from 2020, the total market continues a compound annual growth trajectory near 7.0% and is projected to move meaningfully higher through 2032. For executives planning product portfolios, channel investments or M&A in 2026, the core value of this research lies in translating that topline momentum into defensible, executable choices under heightened safety and emissions scrutiny.
Residential Portable Generators Market
Why this matters for 2026 strategies
- Timing of regulatory inflections: 2025–2026 is a crystallization point. New safety standards and state-level certification requirements that came into effect or were clarified in 2025 are materially reshaping which SKUs can be commercialized and where. Decisions made in 2026 about certifications, model rationalization, and inventory allocation will determine near‑term market access and long‑term brand positioning.
- Predictable topline, disruptive tail risks: The market’s baseline growth provides a reliable backdrop for investment planning. However, episodic shocks—severe weather events prompting surges in replacement demand, or accelerated policy actions on emissions and CO mitigation—create asymmetric upside and downside that must be scenario‑modeled into 2026 budgets.
- Investment prioritization under limited capital: With product and compliance investments competing for the same capital, 2026 will be the year to prioritize certified models, CO‑sensing technologies, and inverter efficiencies that unlock premium pricing and broader market access.
Industry dynamics shaping 2026 choices
Several interlocking trends are influencing demand, supply and strategic posture:
Residential Portable Generators Market
- Safety and emissions standards are shifting from guidance to gatekeepers. The ANSI/PGMA G300 revision that took force in 2025 tightened CO‑shutoff expectations and performance testing for residential models. At the same time, state enforcement of emissions certification—most notably in California—has been clarified and, in some cases, temporarily adjusted in response to supply constraints. These regulatory dynamics convert what were previously market‑access niceties into hard prerequisites in many sales channels.
- Product differentiation is consolidating around multi‑fuel flexibility and intelligent safety systems. Tri‑fuel and dual‑fuel capabilities, advanced CO‑sensing/shutoff, and inverter architectures that deliver cleaner power and quieter operation are now central to competitive differentiation. Firms that delay integrating these features risk margin pressure as consumers and channel partners increasingly prefer certified, safer models.
- Supply‑side frictions create tactical opportunities. Temporary policy adjustments aimed at mitigating shortages have demonstrated that manufacturers who maintain flexible production and certification pipelines capture transient demand spikes. However, these are stopgaps—persistent compliance and certification will be the differentiator for full market participation over the medium term.
Competitive landscape: what the leaders are doing
The market exhibits concentrated leadership: a handful of incumbents set technology, channel and safety benchmarks. Our full report offers in‑depth profiles and strategic scorecards; below are high‑level observations that should inform 2026 playbooks.
Residential Portable Generators Market
- Generac Power Systems, Inc. — Strategy centers on a broad portable and inverter portfolio that spans homeowner to contractor use. Their investment in CO‑sensing safety features and multi‑fuel models has positioned them to defend premium channels. For rivals, Generac’s scale in distribution and brand equity means that any premium technological leap must be coupled with compelling channel incentives to shift shelf space.
- DuroMax Power Equipment — DuroMax competes by combining fuel flexibility with aggressive channel pricing and a focus on residential backup compliance. Their certified dual‑fuel offerings make them a natural competitor in markets where regulatory clarity favors certified SKUs; incumbents should expect focused competition in value channels and DIY retail.
- Champion Power Equipment — Champion’s emphasis on safety technologies such as CO mitigation and its product breadth across dual/tri‑fuel space make it a resilient challenger in both emergency backup and recreational segments. Their playbook demonstrates how consistent safety messaging plus selective product innovation can win shelf position without scale parity.
- Westinghouse Electric Corporation — Westinghouse’s approach contrasts with pure portable specialists through brand leverage and competitive inverter offerings for residential and leisure applications. For strategic planners, Westinghouse’s moves underscore the importance of cross‑category branding and distribution partnerships when pursuing rapid share gains.
Recent regulatory and standardization developments you must factor into 2026 plans
- ANSI/PGMA G300 (revised, effective 2025) established tighter CO‑shutoff and performance testing—manufacturers should assume this is the baseline for residential acceptance and for demonstrating due diligence to regulators and retailers.
- California’s emergency policy in mid‑2025 temporarily allowed continued sale/import of EPA‑certified units to relieve supply constraints; however, state certification remains the durable requirement for long‑term access. Firms must treat temporary waivers as tactical relief, not strategic pathways.
- Industry association inputs to consumer safety agencies in 2025 demonstrate active regulatory engagement; companies that proactively engage standards bodies will have a voice in shaping implementable requirements and in managing compliance costs.
What the PW Consulting report provides (practical deliverables)
The full study is structured to convert market intelligence into immediate decision tools for 2026:
- Topline market sizing and a transparent forecasting model (2026–2032) with scenario toggles for regulatory tightening, accelerated electrification and extreme-weather demand shocks.
- Regulatory impact matrix that quantifies time‑to‑market and cost implications of ANSI/PGMA and state certification pathways, with prioritized certification roadmaps for North America and export markets.
- Product strategy playbooks—feature prioritization (CO safety, inverter tech, fuel flexibility), price‑to‑feature benchmarking, and SKU rationalization templates optimized for retail and e‑commerce channels.
- Competitive scorecards and acquisition target screens—financial proxies, technology fit, and integration risk measures to accelerate inorganic growth decisions.
- Channel and inventory playbooks that align certification timing, production cadence and trade promotions to minimize out‑of‑stock exposure during demand surges.
- Hands‑on M&A and partnership scenarios that show when to buy product‑technology vs. buy distribution, with modeled payback periods under the report’s baseline growth assumption.
- Operational risk heatmap and mitigation playbook covering emissions compliance, recalls, CO‑safety incidents and supply chain disruption.
Actionable recommendations for 2026 planning
- Prioritize certification spend by market value and access risk. Allocate certification budgets to secure access in high‑value jurisdictions first; use temporary policy relaxations only to smooth short‑term revenue, not to replace long‑term compliance.
- Defend and extend safety leadership. Embed CO‑shutoff and tamper‑resistant testing in next‑generation SKUs; safety leadership reduces channel resistance and supports pricing power.
- Product rationalization and SKU simplification. Reduce complexity by focusing on modular platforms that support both inverter and conventional variants; this shortens lead times to certify and reduces inventory burdens.
- Channel segmentation and dynamic inventory allocation. Implement differentiated assortments for certified vs. non‑certified channels and use predictive analytics to allocate certified stock to the most enforcement‑sensitive markets.
- Strategic collaboration with industry bodies. Engage with standards associations and consumer safety agencies to both influence the timing of new requirements and to earn recognition for voluntary compliance efforts.
- Scenario testing and liquidity planning. Build financial plans that stress test 2026 P&Ls under sudden spikes in demand and sudden tightening of state requirements to ensure resilient working capital and production flexibility.
Where this preview leaves you—and what to do next
The residential portable generators market offers a mix of predictable growth and regulatory inflection points. For leaders making 2026 choices, the strategic imperative is clear: move quickly to align product roadmaps and certifications with emerging standards, optimize SKU footprints to reduce compliance and inventory costs, and position brand and channel strategies to monetize safety and multi‑fuel differentiation.
PW Consulting’s complete report provides the empirical backbone—detailed forecast models, competitive benchmarking, certification cost estimates and playbooks—to convert these strategic priorities into executable 2026 plans. This preview illustrates our approach and the types of decisions you will need to take; for the full data tables, granular segmentation, and the operational templates that enable immediate action, consult the full study on our website.
For detailed analysis of this topic, please visit the official page: Residential Portable Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultra-Fine PCC Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-09
Ultra Fine Precipitated Calcium Carbonate (PCC): Strategic Landscape and Actionable Intelligence for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our Ultra Fine Precipitated Calcium Carbonate (PCC) market study. This briefing synthesizes the high-level market trajectory, regulatory and input-cost dynamics, competitive posture, and strategic implications that matter for executive decisions in 2026. The purpose is to demonstrate the analytical depth and operational value of our full report while preserving the proprietary segmentation and granular datasets that executives rely on—those are available in the complete study.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Market trajectory at a glance: what leadership needs to internalize
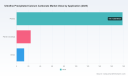
The ultrafine PCC market has moved from niche specialty feedstock toward a broader industrial relevance over the last half-decade. PW Consulting’s base-year analysis (2025) positions the global market at roughly USD 215 million, reflecting consistent expansion since 2020. Our modelling—built on five years of historical market behavior and updated industry inputs—projects a compound annual growth rate (CAGR) of approximately 6.98% across the 2026–2032 forecast window. By the end of that horizon, the market is expected to be meaningfully larger, driven by rising demand in higher-performance plastics, advanced coatings, and specialty formulations where particle size and surface chemistry materially affect product performance.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
For leadership teams contemplating 2026 investment cycles, the implication is straightforward: the market is not only growing, it is maturing toward differentiated, value-added offerings. Tactical moves that merely chase volume without upgrading product capability or go-to-market differentiation are unlikely to capture the margin upside that ultrafine PCC increasingly commands.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Why this study matters for 2026 strategic choices
- Timing for CapEx and capacity planning: Our historical-to-forecast series indicates clear inflection points where incremental capacity or retrofits to produce ultrafine and coated grades generate outsized returns. The report maps these inflection windows to realistic lead times for plant projects and regulatory permitting.
- Pricing and margin preservation: Input volatility—especially in calcium carbonate feed prices and energy—has become a structural consideration. We quantify elasticity scenarios so procurement and commercial teams can model pass-through, hedging, and contract strategies that preserve margin.
- Regulatory compliance and operational risk: Stricter chemical safety and occupational exposure regimes are shifting the cost posture of production in mature geographies. The study provides a compliance playbook and cost uplift estimates tied to key jurisdictions.
- Go-to-market and product roadmap alignment: As customers in plastics and coatings demand tighter particle distributions and functional surface treatments, the report lays out prioritized R&D and SKU strategies that connect technical differentiation to profitable end-use segments.
Contents and practical deliverables in the full PW Consulting report
The full report is designed as a decision-support toolkit, not an academic summary. It contains:
- Concise market sizing and trend analysis (historical 2020–2025 and forecast 2026–2032) with scenario-based pathways and sensitivity to key input variables.
- End-user demand maps and value-chain economics that translate product attributes into margin impact for suppliers and converters.
- Regulatory impact assessments tailored to major production hubs, with quantified cost-of-compliance for different operational footprints.
- Raw material price modeling and stress tests (including short-term spikes and sustained inflation scenarios), plus procurement playbooks for hedging and supplier diversification.
- Operational benchmarks and best-practice guidance for producing ultrafine and coated PCC grades, including quality metrics, yields, and CAPEX ranges for line upgrades.
- Vendor and customer engagement frameworks designed to accelerate adoption of specialty grades—practical templates for technical trials, co-development agreements, and commercial pilots.
- A highly actionable M&A heat map that highlights consolidation candidates, strategic rationales, and synergies—sized and ranked by viability and impact.
Note: the segmented regional and application-level breakdowns, unit economics by grade, and confidential company-level pricing matrices are withheld in this preview and are accessible only through the full report package.
Competitive landscape: an informed synthesis
The ultrafine PCC industry presents a mixed picture of technological specialization and geographic dispersion. Market concentration metrics show a fragmented supplier base: the top three players hold less than a quarter of market revenue, and the top five only slightly more. This dispersion creates room for nimble suppliers to capture pockets of premium performance demand while also leaving the door open for consolidation—particularly among firms that can industrialize niche, high-value grades.
- Calcite GmbH (Germany) — European technology and application engineering remain a core strength. Their presence underlines the premium that localized technical service and industrial partnerships command in regulated markets.
- 20 Microns Nano Minerals Limited (India) — A rising, product-driven supplier focusing on specialty PCC grades. Notably, in December 2025 they launched 'Micron PCC 500', an ultrafine grade designed for high-performance sealants with targeted improvements in reinforcement, rheology, surface finish, and durability. This launch exemplifies how SKU-level innovation is being leveraged to access higher-margin end-use segments.
- Guangdong Qiangda New Materials Technology Co., Ltd. (China) — A strong supply-side contender with scale and cost-competitive manufacturing. Their footprint reflects the advantage of integrated upstream sourcing and proximity to major Asian converters.
- Fujian Sanmu Nano Calcium Carbonate Co., Ltd. (China) and EZ Chemicals Inc. (China) — Both demonstrate the local R&D-to-commercialization pathway that many Asian firms follow: rapid product iteration, aggressive pricing for penetration, and expanding technical partnerships with polymer and coatings formulators.
Collectively, these profiles highlight a competitive playbook focused on three levers: (1) product differentiation through particle engineering and coatings, (2) technical service and co-development agreements, and (3) cost leadership via scale and feedstock integration. For potential acquirers or partners, the tactical choice is whether to buy technology, capacity, or routes-to-market—each has distinct return profiles and integration risks.
Regulatory, supply chain and input-cost dynamics to monitor
- Regulatory tightening: Recent enforcement of chemical safety frameworks in major trade blocs has accelerated the adoption of cleaner production processes. Similarly, updates to occupational exposure limits for airborne particulates have forced operational upgrades and new worker-safety investments.
- Input-price volatility: Raw-material and energy cost movements are increasingly material. For example, North American calcium carbonate price indices recorded upward pressure in mid‑2026, reflecting tightness and short-term supply disruption risk. Procurement strategies that ignore these dynamics will experience margin erosion.
- Environmental and permitting constraints: Stricter controls on dust emissions, water discharge, and mining operations are raising structural costs and limiting capacity expansion in mature regions—pushing suppliers to consider brownfield upgrades, alternative feedstocks, or geographic diversification.
- Geopolitical and FX risk: Tariff uncertainty and currency volatility are non-trivial for suppliers operating across major trade corridors. These risks should factor into sourcing, pricing, and contractual terms.
Practical strategic recommendations for 2026
- Prioritize product and application co-development: Target technical partnerships with key converters in high-growth specialty segments (e.g., high-performance plastics and advanced coatings). Co-development reduces adoption barriers and creates sticky revenue streams.
- Defensive procurement and pricing architecture: Implement dynamic tariff- and currency-aware pricing models, coupled with a layered hedging approach for calcium carbonate feed and energy exposure. Adopt index-linked contracts only after modeling pass-through limits.
- Invest selectively in quality and surface-engineering capability: Upgrading lab-to-line transformation capability—especially for coating technologies and surface treatments—yields outsized returns where customers pay for performance rather than bulk volume.
- Embed compliance into capital planning: Allocate capital for particulate control, worker-safety upgrades, and REACH/OSHA-aligned monitoring systems. Early investment reduces regulatory friction and accelerates market access.
- Evaluate M&A for capability gaps: Given the fragmented market, acquisition of niche players that bring proprietary surface treatments or customer footholds can deliver rapid access to margin-rich segments. Use the report’s M&A heat map to prioritize targets by synergy and execution risk.
Closing note — what to expect from the full PW Consulting report
This preview highlights the directional insights executives need for 2026 planning: a growing ultrafine PCC market, a fast-evolving regulatory and cost environment, and a competitive landscape that rewards technical differentiation and disciplined commercial models. The full PW Consulting study provides the proprietary segmentation, price matrices, regional and application-level demand curves, and the granular scenario analyses that operational teams use to build budgets, R&D roadmaps, and M&A decisions.
For procurement directors, operations leaders, and corporate strategy teams preparing 2026 plans, the full report turns market direction into executable initiatives—supported by templates, KPI targets, and risk mitigations. PW Consulting’s readiness to support implementation (from workshop facilitation to due-diligence support) is available as an advisory add-on to the report.
To access the complete dataset, proprietary segmentation, and the operational toolkits referenced here, please consult the PW Consulting report page for Ultra Fine Precipitated Calcium Carbonate (PCC) Market—where the full intelligence package and advisory engagement options are available.
For detailed analysis of this topic, please visit the official page: Ultra Fine Precipitated Calcium Carbonate Pcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com