

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Food Leavening Agents: Asia Pacific Tops at $360.17M, Market to Reach $998.41M by 2032 (3.8% CAGR)

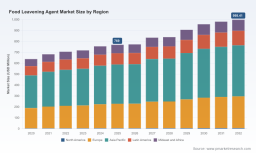
Food Leavening Agent Market — Strategic Preview for 2026 Decision-Makers
As the global food industry recalibrates for the post‑pandemic recovery and rising consumer demand for convenience and premium baked goods, the food leavening agent market is transitioning from steady commodity dynamics to an innovation‑led, channel‑sensitive growth phase. PW Consulting’s latest research (base year 2025) tracks a clear macro trajectory: the market expanded from an estimated USD 638.17 Million in 2020 to roughly USD 769.0 Million in 2025 and is forecast to approach approximately USD 998.4 Million by 2032, driven by a projected compound annual growth rate (CAGR) of 3.8% across the 2026–2032 forecast window.
Food Leavening Agent Market
Why this study matters for 2026 strategy
-
Decision clarity in a crowded field: With mid‑single‑digit CAGR and uneven growth pockets across product types and channels, executives must choose between efficiency plays (scale and commodity sourcing) and differentiation (clean‑label, specialty yeasts, premixes).
Food Leavening Agent Market -
Timing investments: 2026 is a tipping point year for capacity and product investments. Our report aligns operational timing with demand inflection points and regulatory timelines so capital deployments are synchronized with market uptake.
Food Leavening Agent Market -
Regulatory and raw‑material shocks: The interplay of organic standards, GRAS classifications, and sourcing constraints for bicarbonates and ammonium salts requires integrated risk mitigation across procurement, formulation, and labeling.
Market trajectory and structural signals
The market’s steady baseline growth is underpinned by two parallel forces. First, volume growth in industrial and in‑store bakery channels is being supplemented by premiumization — demand for clean‑label premixes, specialty yeasts, and formulation innovations that improve shelf quality and texture. Second, supply‑side consolidation and scale advantages are generating a concentrated landscape: the top three firms capture a materially high share of the market, with the top five firms commanding an even larger portion—an important structural consideration for entrants and mid‑tier suppliers contemplating M&A, distribution partnerships, or co‑manufacturing agreements.
These structural signals mean that price competition will remain intense in commodity segments (standard bicarbonates and basic chemical leaveners), while margin expansion opportunities will exist in proprietary blends, instant dry yeasts, and specialty premixes serving artisanal and foodservice customers.
Segmentation lens (selective—high level)
-
Type dynamics: The market comprises chemical, biological (yeast‑based), and physical leavening solutions. Chemical leaveners continue to dominate volumes due to broad utility and low cost, while biological solutions are the fastest area for product innovation and clean‑label marketing.
-
Application pathways: Core applications include traditional bakery categories such as bread, biscuits/cookies, cakes/pastries, and rolls/pies. Each application reflects distinct formulation needs, procurement cadences, and shelf‑life considerations—factors we map precisely in the full report.
-
Regional implications: Growth pockets vary by cluster—mature markets emphasize process efficiency and clean labeling, while developing markets are driven by rising retail penetration and industrialization of baking. For confidentiality of competitive segmentation, the report’s granular regional and channel splits are reserved for subscribers.
Competitive landscape — who matters and why
The leavening agent ecosystem mixes global ingredient majors, specialized yeast houses, and regional brand incumbents. Market concentration metrics indicate a high share held by the leading players, making strategic positioning around channel control, brand reputation, and formulation IP critical.
-
Large agribusiness and ingredient players (e.g., major processors of sodium and ammonium bicarbonate) provide scale, strong logistics, and cost advantage for commodity leaveners. These firms are natural suppliers to industrial bakers and premix producers.
-
Specialized yeast manufacturers and baking ingredient houses emphasize technical collaboration with bakers, R&D for premixes, and service models (product training, formulation support). These firms are where the market’s highest margin innovation typically originates.
-
Regional brands and legacy names continue to capture retail trust and home‑baker demand; their brand equity enables price premiums in specific channels.
Key companies profiled in our landscape include leading global yeast and baking ingredient suppliers, household baking brands, and diversified ingredient processors. Each profile includes strategic positioning, product portfolios, route‑to‑market analysis, recent corporate developments, and likely next‑move scenarios for 2026–2028. Noteworthy recent developments captured in the study include the commissioning of new specialty yeast capacity by a major yeast producer in 2026 and targeted product launches in selected markets in 2025—both of which have immediate ramifications for supply, pricing and innovation cycles.
Regulatory and raw‑material dynamics — actionable risk factors
-
Raw materials: Ammonium bicarbonate and sodium bicarbonate remain foundational to formulations across pancakes, biscuits and muffin categories. Their availability, quality specifications and handling requirements are assessed in the report’s procurement risk module.
-
Regulatory guardrails: Several leavening agents and supporting substances have explicit regulatory treatments that affect labeling eligibility in organic and processed organic claims. For example, certain ammonium salts are permitted only under specific organic program provisions until regulatory reassessment dates; parallel GRAS affirmations and allowed uses exist for bicarbonates.
-
Packaging and shelf‑life: Commodity storage practices and packaging decisions (e.g., baking soda shelf life under standard handling) materially affect inventory turns and obsolescence risk for manufacturers and distributors.
Our regulatory module cross‑maps these constraints to product portfolios and go‑to‑market claims, enabling legal and regulatory teams to prioritize reformulation or labeling changes before market or compliance breaches occur.
What the full report delivers (practical, executable content)
-
Market forecast model: Scenario‑based projections to 2032 with sensitivity levers for raw‑material shocks, regulatory changes, and adoption rates of clean‑label alternatives.
-
Demand segmentation toolkit: Channel and application demand drivers, buyer personas, and unit economics for industrial vs. artisan segments (note: our publicly circulated preview omits granular regional and application revenue splits—these are available in the subscriber dataset).
-
Supplier scoring and sourcing playbook: Comparative supplier heatmaps, cost benchmarking, and negotiation tactics to secure bicarbonates and specialty yeast supply under variable lead times.
-
Product and innovation roadmap: Priority product concepts, estimated development timelines, and go‑to‑market positioning for clean‑label premixes and high‑purity leavening blends.
-
M&A and partnership playbook: Acquisition targets, valuation heuristics, and integration checklists for buyers seeking to consolidate mid‑market manufacturing or to enter high‑growth specialty segments.
-
Regulatory watchlist and contingency plans: A rolling calendar of regulatory review dates, labeling risks, and recommended compliance actions mapped to product lines.
Strategic priorities for 2026 — an executive playbook
-
Prioritize margin expansion in specialty products: Shift R&D and commercial resources toward yeast‑based and clean‑label premixes where technical support and brand partnerships can protect margins.
-
Secure upstream inputs with flexible contracts: Hedge exposure to bicarbonate availability by diversifying suppliers and incorporating volume‑based pricing triggers; consider strategic inventory for peak seasons.
-
Pursue targeted capacity moves: Use selective capex or tolling arrangements to accelerate time‑to‑market for specialty blends—especially where regulatory labeling windows create temporary market access advantages.
-
Deploy channel segmentation: Separate commercial strategies and KPIs for industrial bakers, artisan/professional bakers, and home‑use retail channels. Tailored packaging, logistics, and training programs improve uptake and stickiness.
-
Prepare for regulatory shifts: Assign cross‑functional owners to monitor organic labeling windows and GRAS‑related updates that could affect product eligibility and marketing claims.
-
Evaluate consolidation opportunities: Given the market concentration of leading players, mid‑tier firms should consider bolt‑on acquisitions or exclusive distribution partnerships to build scale quickly.
How to use this intelligence
Leaders in procurement, R&D, corporate development and commercial functions will find immediate value in the report’s intersectional insights—combining demand forecasts, supplier risk mapping, and innovation roadmaps into executable quarter‑by‑quarter plans. We designed the deliverables so that a CPG product lead can move from insight to pilot in 90 days, and a corporate development team can prepare an acquisition thesis within 60 days.
Note on data scope: this preview purposely surfaces strategic conclusions and macro metrics (including market size trajectory and concentration indices) while withholding detailed revenue splits across regions, product sub‑types and applications. These granular datasets and interactive models are available in the full report package and are essential for granular investment decisions, pricing models, and go‑to‑market allocation.
Next steps
-
Request the full dataset and interactive forecast model to run custom scenarios for your portfolio.
-
Schedule a strategy workshop with PW Consulting to translate findings into a 12‑month action plan tailored to your position in the value chain.
-
Engage our M&A advisory team to explore consolidation targets and valuation frameworks aligned with the market’s concentration dynamics.
For access to the complete Food Leavening Agent Market study—including the subscriber‑only regional and application revenue matrices, supplier scorecards, and an editable scenario model—visit the PW Consulting report page or contact our industry team to arrange a confidential briefing.
For detailed analysis of this topic, please visit the official page: Food Leavening Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com