

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Release Agent Market to Reach USD 3,410 Million by 2032 at 7.17% CAGR

Release Agent Market — Strategic Outlook for 2026: Why this PW Consulting Study Matters
As companies finalize their 2026 strategic plans, one seemingly specialized input is emerging as a cross-industry lever for both risk mitigation and growth: release agents. PW Consulting’s new Release Agent Market study — calibrated to a 2025 base year and projecting through 2032 — translates commodity dynamics, regulatory shockwaves, and supplier positioning into an actionable decision framework. This introduction sketches the decision-grade insights you can expect from the full report, while deliberately withholding the granular segmentation tables and proprietary scorecards that we reserve for subscribers. Think of this narrative as the trailer: it demonstrates depth, frames strategic choices, and points you to the full dossier for execution-level detail.
Release Agent Market
Macro trajectory and what it means for 2026 planning
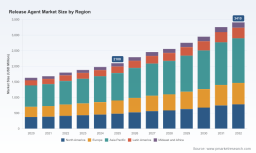
Our updated market model shows a steady enlargement of the global release agent market from an estimated USD 1,631.5 Million in 2020 to USD 2,100.0 Million in 2025. Under our base forecast, the market expands further to roughly USD 3,410.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 7.17% across the projection window. That trajectory is meaningful: it signals robust, sustained demand across food processing, plastics and rubber molding, construction, composites, and specialty industrial applications.
Release Agent Market
For corporate planners, a few implications follow immediately. First, modest-to-strong market growth justifies targeted capacity investments and product development budgets in water-based, bio-based, and carrier-free chemistries. Second, pricing levers will have to accommodate upstream volatility (see raw-material dynamics), while commercial teams should prepare segmented pricing and value-capture frameworks for customers that face their own regulatory headwinds.
Release Agent Market
Regulatory inflection points: the non-negotiable risk
-
European policy is re-shaping product eligibility. Recent EU measures impose higher documentation and migration-testing requirements for food-contact materials and have moved to ban or tightly restrict substances such as certain bisphenols. These changes are not theoretical: they mandate reformulation timelines and create first-mover advantages for suppliers with validated, high-purity technologies.
-
U.S. environmental guidance and state-level restrictions are accelerating adoption of biodegradable formulations in infrastructure applications; we observe double-digit annual growth in some niche biodegradable segments. Firms that ignore this trajectory risk market access problems and reputational costs.
-
Our full report maps the regulatory timelines that matter and translates them into product-compliance deadlines by application. We model enforcement phasing and propose practical remediation roadmaps for product lines that fail to meet upcoming migration and documentation tests.
Raw-material and cost dynamics: tactical playbook for procurement
Commodity pressure is an undercurrent that will determine whether margin expansion accompanies volume growth. Through 2025 we observed a 15–20% rise in oil-indexed costs relative to traditional solvent formulations. That movement is accelerating customer interest in lower-solvent, water-based systems and in substitution with vegetable oils, wax esters, and polymeric carriers where application-appropriate.
Procurement implications are straightforward: hedge raw-material exposure, prioritize dual-sourcing for critical intermediates (siloxanes, specialty esters, food-grade carriers), and push for supplier partnerships that include formula-stability guarantees and raw-material pass-through mechanisms. Our report includes a procurement playbook with supplier negotiation tactics and a sensitivity model that quantifies margin at different oil-price scenarios.
Competitive structure: consolidation with opportunity pockets
The release agent market displays a concentrated competitive structure. The top three players command a substantial share of the market, and the top five occupy an even larger combined footprint — a fact that creates both defensive and offensive imperatives for mid-tier manufacturers and newcomers. High concentration delivers predictable channel dynamics but also increases the strategic value of niche differentiation: food-grade traceability, fast regulatory-compliant reformulations, and application-specific performance claims.
Key supplier profiles covered in the study include established multinationals and specialty players. Highlights:
-
Chem-Trend L.P.: Known for diverse delivery formats, including water-based, solvent-based, and carrier-free systems; recent launches focus on high-pressure aluminum casting solutions with improved operational efficiency.
-
Miller-Stephenson Chemical Co.: Specialist offerings for concrete, rotational molding, and high-temperature applications; strong reputation in industrial-grade specialty chemistries.
-
Henkel AG & Co. KGaA: A global systems provider with a strong foothold in automotive and aerospace applications through established brands and integrated customer programs.
-
Wacker Chemie AG and Shin-Etsu Chemical: Silicon-focused portfolios and an increasing emphasis on food-grade and eco-friendly formulations that align with regulatory trends.
-
Dow Inc. and BASF SE: Broad platform players pushing performance- and sustainability-oriented innovations, including biodegradable and bio-based options for construction and industrial uses.
-
Synova (Bundy Baking Solutions), Marbocote, and Mallet & Company: Niche specialists in bakery/foodservice and precision engineering who are leveraging focused portfolios to win category-specific share.
We analyze these firms across seven strategic dimensions — technology leadership, regulatory readiness, scale advantage, go-to-market capability, pricing power, innovation pipeline, and M&A appetite — and translate that analysis into prioritized engagement strategies for OEMs, distributors, and private equity sponsors.
Innovation vectors and product architecture
Three innovation themes will shape winners in 2026 and beyond: 1) high-purity, traceable chemistries that satisfy tighter food-contact regimes; 2) carrier-free and low-VOC systems that reduce lifecycle environmental impact; and 3) formulation modularity that enables rapid, cost-effective customization for specialty applications (e.g., high-temperature composites, high-throughput bakery lines, and asphalt release agents).
The study provides a technology roadmap that connects R&D investment to near-term commercial outcomes, enabling R&D leaders to prioritize projects with the highest IRR and shortest regulatory-compliance runway.
Actionable content in the full report (what you’ll get)
-
Proprietary market-sizing model (historical 2020–2025, base 2025; forecasts 2026–2032) with scenario toggles for regulatory and raw-material shocks.
-
Supplier scorecards and benchmarking dashboards that quantify competitive positioning across the seven strategic dimensions noted above.
-
Regulatory impact matrix and compliance timetable tailored to food-contact applications and infrastructure segments.
-
Go-to-market playbooks for manufacturers and distributors (pricing strategies, channel segmentation, co-development agreements).
-
M&A target list and diligence checklist for private equity and corporate development teams, including integration risk scoring.
-
Operational playbooks: SKU rationalization guidance, formulation transition blueprints, and plant retrofit costing for water-based production lines.
-
Excel-based sensitivity models and downloadable datasets to integrate into your internal financial planning systems.
Strategic recommendations for 2026 decision cycles
-
Prioritize compliance-driven reformulation programs for food-contact lines. Treat migration testing and documentation as a product feature, not a compliance tax.
-
Accelerate capital allocation toward modular, water-based production capacity where customer demand and regulatory imperatives overlap.
-
Secure strategic raw-material supply through long-term contracts and selective equity or JV arrangements upstream in ester and carrier supply chains.
-
Explore bolt-on acquisitions of niche players with validated food-grade or biodegradable portfolios — these assets create rapid market access and regulatory credence.
-
Deploy scenario planning: run base, regulatory-tight, and raw-material-shock scenarios during Q1 budget reviews and stress-test commercial commitments under each.
Recent developments and what they reveal
-
Product portfolio expansions and new product launches in 2025 reflect vendor responses to both technical demand and regulatory timelines. For example, a leading bakery-focused supplier expanded its Integra portfolio in August 2025 to capture foodservice demand, and Chem-Trend launched a high-pressure casting-specific release agent earlier in 2025. These moves underscore how suppliers are bifurcating investments between performance differentiation and compliance-ready offerings.
-
Market concentration increases the strategic value of partnerships: smaller suppliers can accelerate growth by partnering with or being acquired by scale players that provide distribution breadth and global compliance infrastructure.
Why PW Consulting’s study is decision-grade for 2026
This study is built to connect board-level imperatives to plant-floor actions. It quantifies the market opportunity, models regulatory impact, and provides the tactical playbooks necessary to convert compliance pressure into competitive advantage. Importantly, while this introduction highlights the themes and the implications, the full study contains the granular segmentation, financial tables, supplier scorecards, and downloadable models that operational teams will need to execute through 2026 and beyond.
To preserve the strategic value of our research and to protect the proprietary segmentation and supplier scoring methodology, we intentionally withhold the detailed tables and split-level metrics in this public overview. If you are planning product portfolio moves, plant investments, or M&A activity in 2026, access the full report to obtain the complete datasets, scenario models, and the supplier playbooks necessary to act with confidence.
PW Consulting stands ready to brief executive teams, run customized scenario workshops, and support diligence and integration planning for transactions originating from insights in this study. Contact our Release Agent Market practice to schedule a private walkthrough of the full dataset and to license the modeling tools that power our recommendations.
For detailed analysis of this topic, please visit the official page: Release Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com