

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ultra-Fine PCC Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Ultra Fine Precipitated Calcium Carbonate (PCC): Strategic Landscape and Actionable Intelligence for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our Ultra Fine Precipitated Calcium Carbonate (PCC) market study. This briefing synthesizes the high-level market trajectory, regulatory and input-cost dynamics, competitive posture, and strategic implications that matter for executive decisions in 2026. The purpose is to demonstrate the analytical depth and operational value of our full report while preserving the proprietary segmentation and granular datasets that executives rely on—those are available in the complete study.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Market trajectory at a glance: what leadership needs to internalize
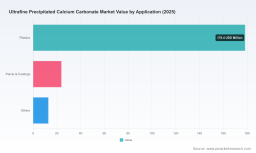
The ultrafine PCC market has moved from niche specialty feedstock toward a broader industrial relevance over the last half-decade. PW Consulting’s base-year analysis (2025) positions the global market at roughly USD 215 million, reflecting consistent expansion since 2020. Our modelling—built on five years of historical market behavior and updated industry inputs—projects a compound annual growth rate (CAGR) of approximately 6.98% across the 2026–2032 forecast window. By the end of that horizon, the market is expected to be meaningfully larger, driven by rising demand in higher-performance plastics, advanced coatings, and specialty formulations where particle size and surface chemistry materially affect product performance.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
For leadership teams contemplating 2026 investment cycles, the implication is straightforward: the market is not only growing, it is maturing toward differentiated, value-added offerings. Tactical moves that merely chase volume without upgrading product capability or go-to-market differentiation are unlikely to capture the margin upside that ultrafine PCC increasingly commands.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Why this study matters for 2026 strategic choices
- Timing for CapEx and capacity planning: Our historical-to-forecast series indicates clear inflection points where incremental capacity or retrofits to produce ultrafine and coated grades generate outsized returns. The report maps these inflection windows to realistic lead times for plant projects and regulatory permitting.
- Pricing and margin preservation: Input volatility—especially in calcium carbonate feed prices and energy—has become a structural consideration. We quantify elasticity scenarios so procurement and commercial teams can model pass-through, hedging, and contract strategies that preserve margin.
- Regulatory compliance and operational risk: Stricter chemical safety and occupational exposure regimes are shifting the cost posture of production in mature geographies. The study provides a compliance playbook and cost uplift estimates tied to key jurisdictions.
- Go-to-market and product roadmap alignment: As customers in plastics and coatings demand tighter particle distributions and functional surface treatments, the report lays out prioritized R&D and SKU strategies that connect technical differentiation to profitable end-use segments.
Contents and practical deliverables in the full PW Consulting report
The full report is designed as a decision-support toolkit, not an academic summary. It contains:
- Concise market sizing and trend analysis (historical 2020–2025 and forecast 2026–2032) with scenario-based pathways and sensitivity to key input variables.
- End-user demand maps and value-chain economics that translate product attributes into margin impact for suppliers and converters.
- Regulatory impact assessments tailored to major production hubs, with quantified cost-of-compliance for different operational footprints.
- Raw material price modeling and stress tests (including short-term spikes and sustained inflation scenarios), plus procurement playbooks for hedging and supplier diversification.
- Operational benchmarks and best-practice guidance for producing ultrafine and coated PCC grades, including quality metrics, yields, and CAPEX ranges for line upgrades.
- Vendor and customer engagement frameworks designed to accelerate adoption of specialty grades—practical templates for technical trials, co-development agreements, and commercial pilots.
- A highly actionable M&A heat map that highlights consolidation candidates, strategic rationales, and synergies—sized and ranked by viability and impact.
Note: the segmented regional and application-level breakdowns, unit economics by grade, and confidential company-level pricing matrices are withheld in this preview and are accessible only through the full report package.
Competitive landscape: an informed synthesis
The ultrafine PCC industry presents a mixed picture of technological specialization and geographic dispersion. Market concentration metrics show a fragmented supplier base: the top three players hold less than a quarter of market revenue, and the top five only slightly more. This dispersion creates room for nimble suppliers to capture pockets of premium performance demand while also leaving the door open for consolidation—particularly among firms that can industrialize niche, high-value grades.
- Calcite GmbH (Germany) — European technology and application engineering remain a core strength. Their presence underlines the premium that localized technical service and industrial partnerships command in regulated markets.
- 20 Microns Nano Minerals Limited (India) — A rising, product-driven supplier focusing on specialty PCC grades. Notably, in December 2025 they launched 'Micron PCC 500', an ultrafine grade designed for high-performance sealants with targeted improvements in reinforcement, rheology, surface finish, and durability. This launch exemplifies how SKU-level innovation is being leveraged to access higher-margin end-use segments.
- Guangdong Qiangda New Materials Technology Co., Ltd. (China) — A strong supply-side contender with scale and cost-competitive manufacturing. Their footprint reflects the advantage of integrated upstream sourcing and proximity to major Asian converters.
- Fujian Sanmu Nano Calcium Carbonate Co., Ltd. (China) and EZ Chemicals Inc. (China) — Both demonstrate the local R&D-to-commercialization pathway that many Asian firms follow: rapid product iteration, aggressive pricing for penetration, and expanding technical partnerships with polymer and coatings formulators.
Collectively, these profiles highlight a competitive playbook focused on three levers: (1) product differentiation through particle engineering and coatings, (2) technical service and co-development agreements, and (3) cost leadership via scale and feedstock integration. For potential acquirers or partners, the tactical choice is whether to buy technology, capacity, or routes-to-market—each has distinct return profiles and integration risks.
Regulatory, supply chain and input-cost dynamics to monitor
- Regulatory tightening: Recent enforcement of chemical safety frameworks in major trade blocs has accelerated the adoption of cleaner production processes. Similarly, updates to occupational exposure limits for airborne particulates have forced operational upgrades and new worker-safety investments.
- Input-price volatility: Raw-material and energy cost movements are increasingly material. For example, North American calcium carbonate price indices recorded upward pressure in mid‑2026, reflecting tightness and short-term supply disruption risk. Procurement strategies that ignore these dynamics will experience margin erosion.
- Environmental and permitting constraints: Stricter controls on dust emissions, water discharge, and mining operations are raising structural costs and limiting capacity expansion in mature regions—pushing suppliers to consider brownfield upgrades, alternative feedstocks, or geographic diversification.
- Geopolitical and FX risk: Tariff uncertainty and currency volatility are non-trivial for suppliers operating across major trade corridors. These risks should factor into sourcing, pricing, and contractual terms.
Practical strategic recommendations for 2026
- Prioritize product and application co-development: Target technical partnerships with key converters in high-growth specialty segments (e.g., high-performance plastics and advanced coatings). Co-development reduces adoption barriers and creates sticky revenue streams.
- Defensive procurement and pricing architecture: Implement dynamic tariff- and currency-aware pricing models, coupled with a layered hedging approach for calcium carbonate feed and energy exposure. Adopt index-linked contracts only after modeling pass-through limits.
- Invest selectively in quality and surface-engineering capability: Upgrading lab-to-line transformation capability—especially for coating technologies and surface treatments—yields outsized returns where customers pay for performance rather than bulk volume.
- Embed compliance into capital planning: Allocate capital for particulate control, worker-safety upgrades, and REACH/OSHA-aligned monitoring systems. Early investment reduces regulatory friction and accelerates market access.
- Evaluate M&A for capability gaps: Given the fragmented market, acquisition of niche players that bring proprietary surface treatments or customer footholds can deliver rapid access to margin-rich segments. Use the report’s M&A heat map to prioritize targets by synergy and execution risk.
Closing note — what to expect from the full PW Consulting report
This preview highlights the directional insights executives need for 2026 planning: a growing ultrafine PCC market, a fast-evolving regulatory and cost environment, and a competitive landscape that rewards technical differentiation and disciplined commercial models. The full PW Consulting study provides the proprietary segmentation, price matrices, regional and application-level demand curves, and the granular scenario analyses that operational teams use to build budgets, R&D roadmaps, and M&A decisions.
For procurement directors, operations leaders, and corporate strategy teams preparing 2026 plans, the full report turns market direction into executable initiatives—supported by templates, KPI targets, and risk mitigations. PW Consulting’s readiness to support implementation (from workshop facilitation to due-diligence support) is available as an advisory add-on to the report.
To access the complete dataset, proprietary segmentation, and the operational toolkits referenced here, please consult the PW Consulting report page for Ultra Fine Precipitated Calcium Carbonate (PCC) Market—where the full intelligence package and advisory engagement options are available.
For detailed analysis of this topic, please visit the official page: Ultra Fine Precipitated Calcium Carbonate Pcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com