

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: L-Alanine Market to Reach USD 236.82M by 2032, Growing at 5.69% CAGR

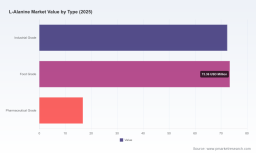
L‑Alanine Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision‑centric preview of the L‑Alanine market designed to inform executive choices in 2026. This briefing synthesizes observed market momentum, regulatory inflection points, supply‑chain dynamics, and the competitive posture of incumbent producers. It highlights the strategic value of our full market study while intentionally withholding the granular subsegment tables and detailed numeric splits — a deliberate “trailer” approach to motivate access to the complete report for transaction‑level and operational planning.
L-Alanine Market
Why this matters for 2026 decision cycles
Between 2020 and 2025 the global L‑Alanine market moved from an established base to a materially larger, more diversified demand pool. Our base‑year sizing (2025) and the forecast through 2032 show a clear expansionary trajectory, supported by a compound annual growth rate of 5.69% across the 2026–2032 forecast window. To put the scale of change into context: the market grew steadily through the early 2020s and continues to scale through the end of the forecast horizon, reflecting structural demand shifts in nutrition, clinical/medical applications, and select industrial uses.
L-Alanine Market
For corporate leaders, procurement heads, product managers, and M&A teams, this trajectory translates into actionable implications in 2026: decisions taken this year on capacity, qualification of alternative feedstocks, regulatory risk mitigation, and partner selection will determine cost of goods, time to market, and pricing power well into the next decade.
L-Alanine Market
What our full PW Consulting L‑Alanine study delivers
- Robust market sizing and forward projections (2026–2032) built on bottom‑up demand modeling and supply capacity mapping, including scenario stress tests under alternative raw material and regulatory assumptions.
- Practical go‑to‑market playbooks for producers and formulators — covering qualification timelines for medical and food applications, pricing tier strategies, and commercialization roadmaps for new grades (e.g., high‑optical purity, pharmaceutical grades).
- Supply‑chain heatmaps that identify one‑to‑two step substitution pathways, raw material exposure, and logistics choke points relevant for contracting and inventory strategy.
- Competitive benchmarking with capabilities matrices (fermentation vs chemical synthesis, certification footprints, geographic production, and product grade portfolios), and a prioritized list of acquisition/investment targets.
- Regulatory risk matrix and mitigation playbook tailored to EP/USP/JP monographs, medical nutrition approvals, and GMP/quality assurance regimes.
- Practical capital allocation guidance covering greenfield vs brownfield expansion, estimated payback horizons under conservative demand scenarios, and sensitivity analysis for raw‑material price shocks.
Note: while this preview summarizes the nature of the granular analysis, the detailed split tables by region, application, and grade (which inform procurement-level decisions and valuations) are intentionally not reproduced here and are available in the full report.
Market dynamics: drivers, constraints and near‑term inflection points
- Structural demand drivers: The convergence of clinical nutrition growth, rising demand for specialized food and beverage formulations, and incremental use in specialty industrial formulations is sustaining above‑average growth. These drivers are durable and supported by both demographic trends and formulation innovation.
- Production economics: Fermentation‑based manufacturing using renewable sugar feedstocks continues to lower cost per unit versus some chemical synthesis routes. This dynamic is reshaping cost curves and is a decisive factor for new capacity investment and supplier selection.
- Regulatory enablers and scrutiny: L‑Alanine’s inclusion in major pharmacopeias and its status as an approved non‑animal‑derived amino acid for medical and enteral nutrition open higher value routes to market. At the same time, regulatory scrutiny remains material — firms must maintain rigorous compliance and quality systems to avoid operational disruptions.
- Market concentration and competition: The market displays moderate concentration among leading producers. That concentration creates both opportunities for niche entrants (by focusing on high‑purity grades or differentiated service models) and risk for buyers relying on limited qualified sources.
- Sustainability and ESG: Credible sustainability credentials are becoming a procurement prerequisite. Recent supplier certifications and public sustainability disclosures materially influence contract outcomes and price premia.
Competitive landscape: profile, posture and near‑term moves
The competitive set comprises established fermentation specialists, diversified chemical and ingredient players, and regional synthetic‑biology manufacturers. Below is a synthesis of the strategic positioning of five representative companies, distilled for readers evaluating partners, acquisition targets, or competitive threats.
- Ajinomoto Co., Inc. (Japan) — A global fermentation leader with deep expertise in both pharmaceutical and food‑grade amino acids. Strengths include global supply chains, brand trust in nutrition and clinical markets, and an integrated approach to R&D and process optimization. Strategic implication: Ajinomoto is a natural partner or acquiror for firms seeking rapid geographic scale and validated quality footprints.
- Evonik Industries AG (Germany) — Positions itself as a supplier of non‑animal‑derived grades compliant with EP/USP/JP, servicing medical nutrition, infant formula, and biopharma segments. Strengths include regulatory alignment and portfolio breadth. Strategic implication: buyers targeting institutional or clinical channels should prioritize qualification of Evonik and similar, pharmacopeia‑compliant suppliers.
- Kyowa Hakko Bio Co., Ltd. (Japan) — A fermentation specialist focused on high‑purity amino acids for pharmaceutical and nutritional markets. While a respected player, prior regulatory interactions underscore the importance of compliance transparency when engaging with the company. Strategic implication: deep due diligence is recommended where regulatory histories affect qualification timeframes.
- Anhui Huaheng Biotechnology Co., Ltd. (China) — A synthetic‑biology oriented producer active across animal and human nutrition, personal care, and intermediates. Recent product communications on related feed solutions and an EcoVadis Silver recognition reflect an aggressive product and sustainability messaging strategy. Strategic implication: AHB represents a competitive, cost‑competitive alternative, especially for regional buyers and specialty feed applications; its sustainability credentials make it a more attractive counterparty for ESG‑minded procurement teams.
- SINOGEL Amino Acid Co., Ltd. (China) — A specialist manufacturer offering multiple grades (technical, high‑optical purity, food). Strategic implication: SINOGEL is well positioned to serve downstream formulators seeking multiple grade options and flexible commercial terms, particularly where speed to market is critical.
Collectively, these players demonstrate differentiated routes to market: global integrated suppliers capture institutional clinical demand; regional synthetic‑biology specialists compete on price, flexibility and niche innovation; and companies with strong certification narratives extract pricing premium and faster qualification in regulated channels.
Recent operational and regulatory signals to watch in 2026
- New product communications and application notes from synthetic‑biology producers are expanding use cases (e.g., aquaculture feed formulations and amino acid health information). These moves are classic demand‑creation plays that precede volume adoption and should prompt procurement to trial offshore alternatives early.
- Third‑party sustainability certifications (e.g., EcoVadis Silver) are emerging as commercial differentiators in supplier selection; companies without a credible sustainability narrative will face longer tender cycles and potential price concessions.
- Regulatory interactions — including any close‑out communications or warning letters related to amino acids manufacturing — materially affect supplier qualification lead times. Buyers and investors should flag such histories as a non‑trivial part of counterparty risk assessments.
Practical strategic playbook for 2026
- Prioritize supplier qualification for at least two pharmacopeia‑aligned producers if entering medical or infant nutrition channels; expect multi‑quarter timelines.
- Hedge raw‑material exposure by locking multi‑year sugar or carbohydrate feedstock agreements where fermentation pathways dominate your cost base.
- Pursue targeted capex in fermentation optimization (yield, titer, downstream recovery) rather than broad capacity expansion; small efficiency gains are highly accretive given the projected CAGR.
- Embed regulatory diligence early in M&A and sourcing processes — public regulatory notices materially change valuation and timeline assumptions.
- Make sustainability credentials (third‑party audits, carbon intensity reporting) a gating criterion for strategic suppliers; this reduces tender friction and preserves pricing leverage.
- Run three scenario‑based models for any investment decision: conservative (lower adoption), central (market CAGR reflected), and aggressive (accelerated specialization adoption); use these to stress test NPV and payback assumptions.
Final takeaways — the strategic value of the full report
For 2026 strategic planning, the L‑Alanine market presents a balanced opportunity set: predictable, mid‑single‑digit CAGR growth with clear pathways to higher‑value segments via regulatory compliance, grade differentiation, and sustainability positioning. The tactical decisions you make this year — which suppliers to qualify, what production technologies to invest in, how to structure long‑term feedstock contracts, and which potential targets to pursue — will compound over the forecast window.
PW Consulting’s full market study contains the detailed segmentation tables, supplier scorecards, unit‑cost models, and contract templates that convert the insights above into executable programs. To maintain the integrity of commercial planning and to encourage a fact‑based procurement process, we have withheld the granular numeric splits from this preview. Access the complete intelligence on our report page to obtain the subsegment allocations, regional flows, and downloadable financial models that support transaction execution and operational planning.
Should you wish to discuss how these insights translate to a bespoke readiness assessment, supplier due‑diligence program, or acquisition screening tailored to your organization, PW Consulting stands ready to convert market clarity into measurable decisions.
For detailed analysis of this topic, please visit the official page: L-Alanine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com