

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Enclosed Belt Conveyor Market to Hit USD 344.8M by 2032 at 7.1% CAGR

Enclosed Belt Conveyor Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present a focused, decision‑centric preview of our Enclosed Belt Conveyor Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This briefing synthesizes the macro trajectory, competitive posture, and the operational dynamics that will matter to procurement, engineering leadership, OEM strategy teams, and investors planning actions in 2026. It intentionally demonstrates analytical rigor while withholding detailed segment-level allocations — a tactical “trailer” to motivate full report access for execution‑level intelligence.
Enclosed Belt Conveyor Market
Market snapshot: Where the market stands and where it is headed
Between 2020 and 2025 the global enclosed belt conveyor market recorded steady expansion, reflecting resilient demand from bulk handling sectors. The market grew from an aggregate that we track in 2020 to a larger consolidated size by 2025 (base year). Under our central projection, the market is expected to expand at a compound annual growth rate (CAGR) of 7.1% over the 2026–2032 forecast horizon, moving from the 2026 opening point through to a materially larger market by 2032. This pace reflects both recovery tailwinds in industrial CAPEX and structural tailwinds driven by automation, stricter dust‑containment regulation, and product innovation.
Enclosed Belt Conveyor Market
Why this matters for 2026 decision cycles
- Procurement and capex timing: A predictable mid‑single‑digit CAGR allows buyers to stage replacement and retrofit programs around multi‑year maintenance budgets rather than rush into spot procurements.
- Supplier selection and risk: The market remains relatively fragmented compared with heavy industrial equipment categories. Buyers that rely on a narrow supplier set will face availability and lead‑time risk if they don't diversify across vendors with different design philosophies (e.g., molded belts vs. steel enclosures).
- Product development prioritisation: R&D and product roadmaps should prioritize belting materials, dust‑containment seals, and low‑maintenance idler systems — features that buyers will pay a premium for as regulatory and operational pressures mount.
- Investment thesis clarity: Investors evaluating OEMs should weigh the stable CAGR against commodity exposure (raw steel, polymers) and the extent to which firms demonstrate differentiated IP or channel reach into high‑growth verticals.
Market dynamics driving growth and risk
- Regulatory acceleration: Recent industry standards and government mandates increasingly require near‑complete dust containment (approaching 99% in sensitive sectors such as food, cement, and fertilizer). This regulatory tightening converts into a purchasing imperative for enclosed solutions and premium designs that can demonstrably meet compliance tests.
- Raw material cost exposure: Production of enclosed belt conveyors is materially influenced by inputs such as galvanized steel (notably higher grades like G140) and engineering polymers (UHMW). These inputs can constitute a substantial proportion of unit cost, creating margin sensitivity for OEMs that lack hedging or sourcing strategies.
- Labor and automation pressures: Global labor shortages in industrial operations are accelerating adoption of enclosed conveyors which reduce operator requirements through safer, dust‑free continuous handling. Buyers value systems that reduce routine maintenance labor through proven low‑wear components.
- Technology and product innovation: Recent product introductions demonstrate a clear vendor focus on belting technology (high‑durability molded belts), higher capacity drive trains, and modular designs for rapid deployment. These innovations are changing procurement evaluation criteria from purely capital cost to total cost of ownership (TCO) and uptime metrics.
- Commodity cycle and project phasing: The market’s growth profile smooths the impact of cyclical end markets (mining, agriculture, ports), but project‑driven spikes remain a feature. Strategic purchasers should integrate supplier capacity and lead‑time forecasts into multi‑year capital plans.
Segmentation — what we analyse (and why we don’t publish every split here)
The full study contains rigorous segmentation by type, application, and geography across historical and forecast periods. We model demand drivers, replacement cycles, unit pricing dynamics, and supply‑chain cost stacks at the segment level. To preserve the utility of this preview and to comply with our “trailer” approach, we intentionally do not publish segment allocations or regional shares here; those actionable splits are reserved for the full report.
Enclosed Belt Conveyor Market
That said, readers should know we examine:
- Type choices (roller, spool, air‑cushion and hybrids) and their implications for incline capability, maintenance cadence, and TCO.
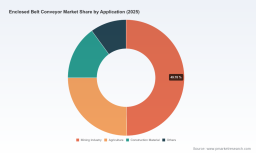
- End‑use applications (mining, agriculture, construction materials, and others) with differentiated replacement timelines and procurement drivers.
- Geographic demand patterns and project pipelines, contextualized with capex momentum across industrial subsectors.
Competitive landscape — profiles and positioning
The market is served by a mix of specialized OEMs and larger material‑handling firms. The competitive picture is characterized by niche engineering differentiation rather than dominance by a handful of global mega‑players. Key firms exemplify distinct value propositions:
- Ag Growth International (AGI) — Mokena, IL: AGI emphasizes both high‑capacity and dust‑tight designs with product lines tailored for grain handling. Their strength is channel presence in agricultural terminals and a focus on lifecycle performance for grain handlers.
- Cambelt International — Salt Lake City, UT: Cambelt’s proprietary one‑piece molded belting and high‑incline transloaders are positioned for installations where delamination risk and steep conveying profiles are deciding factors. Their IP around belting construction gives them a technical edge in certain bulk handling use cases.
- Bulk Conveyors, Inc. (BCI) — Wichita, KS: BCI competes on low‑maintenance, dust‑tight modules with proven serviceability. Their portfolio is attractive to industrial buyers prioritizing predictable uptime and minimal on‑site intervention.
- Kase Conveyors — Whitney, TX: Kase positions itself on customization — delivering bespoke enclosed conveyor systems for complex industrial layouts, which is valuable for retrofit projects and constrained plant footprints.
- Sweet Manufacturing — Spruce Hill, OH: With an emphasis on galvanized structural designs and robust construction, Sweet targets agricultural and industrial operators seeking long‑life, corrosion‑resistant systems.
- Warrior Mfg. — Hutchinson, MN: Warrior focuses on heavy‑duty idlers and UHMW liners for high throughput applications, appealing to mining and aggregate operations where abrasion resistance is central.
Across vendors, differentiation clusters around belting technology, enclosure metallurgy, idler and liner designs, and aftermarket service networks. Our concentration analysis shows that the top suppliers together do not overwhelmingly dominate the market, leaving room for regional champions and technology specialists to capture niche segments — an important fact for procurement teams seeking alternative sources or partners for co‑development.
Recent industry moves that signal near‑term shifts
- Major suppliers are pushing higher‑capacity and “smarter” conveyors that integrate durability improvements and condition monitoring — examples include product updates and launches across established OEMs in 2025–2026.
- Belting manufacturers have released belting optimized specifically for enclosed systems, reducing wear and improving incline performance — a trend that will reshape retrofit specifications and spare‑parts strategies.
- These product steps, coupled with ongoing regulation, are steadily moving buyer evaluation criteria from upfront price toward demonstrable TCO and regulatory compliance credentials.
What the full PW Consulting report delivers (practical, executable outputs)
- Quantified market sizing and growth scenarios (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity testing against commodity and regulatory shocks.
- Segment‑level demand models and unit pricing curves to support capital budgeting and sourcing decisions.
- Supplier scorecards and comparative matrices emphasizing product features, aftermarket footprint, lead times, and financial health.
- Investment and M&A playbooks highlighting target profiles and integration risks for strategic buyers.
- Procurement templates and TCO calculators designed to convert technical spec choices into cash‑flow impacts over typical project horizons.
Strategic implications & recommended 2026 actions
- For OEMs: Prioritise belting R&D, modular enclosure systems, and expanded aftermarket coverage. Hedge raw material exposure through diversified sourcing or pass‑through contracts to protect margins during commodity volatility.
- For asset owners/operators: Reassess replacement vs. retrofit decisions through a TCO lens that incorporates regulatory compliance costs and labor savings. Consider multi‑year supplier partnerships to secure capacity and reduce lead‑time risk.
- For investors: Seek firms with proprietary belting or sealing IP, strong service networks, and demonstrable cost‑control mechanisms for steel/polymer procurement; these attributes materially de‑risk earnings against commodity cycles.
Conclusion — why access the full study
Our market preview contextualizes a growth story driven by regulation, automation, and targeted product innovation. The headline trajectory — a stable CAGR through the forecast horizon — sets the backdrop, but the real strategic value lies in the segment‑level demand drivers, supplier scorecards, and executable procurement and M&A playbooks contained in the full report. For teams preparing budgets, negotiating vendor contracts, or evaluating investments in 2026, those operating‑level insights will be decisive.
PW Consulting’s full Enclosed Belt Conveyor Market study contains the empirical detail and proprietary frameworks you will need to convert the market’s structural trends into boardroom decisions. Contact PW Consulting to unlock the full dataset, models, and supplier matrices required to act with conviction in 2026.
For detailed analysis of this topic, please visit the official page: Enclosed Belt Conveyor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com