

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Auto Power Window Motors to hit USD 344.8M by 2032 (5.07% CAGR)

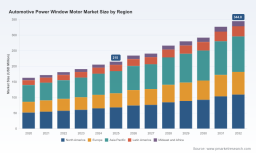
Automotive Power Window Motor Market — Strategic Intelligence for 2026 Decision-Makers
Executive preview
As automotive OEMs and tier suppliers map product roadmaps and procurement strategies for 2026, the Automotive Power Window Motor market presents a clear, measurable growth story — but one that conceals important tactical inflection points beneath an otherwise steady headline. PW Consulting’s market model shows a market that grew from roughly USD 163 million in 2020 to about USD 215 million in 2025, and is forecast to continue expanding at a compound annual growth rate of c.5.07% into the 2026–2032 horizon, reaching roughly USD 345 million by 2032. For executives evaluating manufacturing investments, supplier partnerships, or M&A opportunities in 2026, the opportunity is sizable — and the competitive and regulatory terrain requires deliberate, early action.
Automotive Power Window Motor Market
Why this study matters for 2026 planning
- It translates macro momentum (vehicle content growth, safety regulation, and incremental feature adoption) into discrete opportunities for product, procurement, and R&D roadmaps.
- It combines a forward-looking quantitative model with pragmatic playbooks for supplier evaluation, cost sensitivity testing, and compliance readiness — the tactical inputs that accelerate boardroom decisions into executable programs.
- It surfaces mid-cycle risks — from material cost volatility to regulation-driven requalification — that can shift 2026 budgets and supplier strategies if not anticipated.
Market trajectory and practical inflection points
The market’s historical arc (USD ~163M in 2020 to USD ~215M in 2025) reflects steady demand for powered convenience and safety functions in passenger vehicles. The near-term step to approximately USD 234M in 2026 embedded in our base-case model is driven primarily by continued refresh cycles in light vehicle platforms, incremental electronic content per vehicle (anti-pinch sensors, integrated control electronics), and rising adoption of brushless motor architectures in mid- and premium segments.
Automotive Power Window Motor Market
From a strategic planning perspective, the c.5.07% CAGR projected across 2026–2032 is meaningful: it signals an expanding addressable market large enough to justify targeted capacity additions, but not so concentrated that scale alone delivers guaranteed margin. Decision-makers must therefore balance investments in differentiated technology (electronics, sensors, lightweighting) with disciplined cost management and a focused go-to-market strategy.
Automotive Power Window Motor Market
Structural dynamics: fragmentation, profit pools and product migration
The market’s competitive structure is not a classic winner-takes-most oligopoly. Measured concentration metrics show that the top three and top five suppliers capture modest shares of the total market, which implies a fragmented vendor landscape and multiple viable partners for OEMs and tier-one customers. For investors and corporate development teams, that fragmentation creates two parallel strategies: (1) consolidation and capability roll-ups to capture supplier economics, or (2) targeted partnerships to access specific technology modules (e.g., encoderless anti-pinch, ultra-lightweight motors).
Product migration remains a central theme. Brushless motor architectures, integrated electronics, and embedded obstruction-detection algorithms are progressively displacing legacy brushed units in new platforms — creating differentiated value propositions on reliability, NVH, and energy efficiency. Niche architectures (such as stepper-based solutions) retain relevance in specific applications where positional control matters, but the headline trend is toward fewer, higher-value modules per door system combined with smarter software-driven diagnostics.
Technology, regulations and supply-side shocks — what 2026 leaders must prioritize
- Regulatory compliance is non-negotiable. Recent technical bulletins and regulatory mandates from major jurisdictions emphasize anti-pinch and intelligent obstruction detection. These requirements influence design validation cycles, supplier qualification timelines, and warranty exposure. Expect certification and functional safety audits (ISO 26262, FMVSS/region-specific equivalents) to form a gating item for OEM approval lists.
- Electronics-enabled architectures are accelerating. Silicon and MCU suppliers are releasing application-focused motor-driver evaluation platforms that shorten development cycles for encoderless anti-pinch implementations. These enablers materially reduce integration time — but they also raise the bar for software verification and cybersecurity considerations.
- Raw material volatility is an ongoing constraint. The price of rare-earth elements used in high-efficiency motors has experienced significant upward pressure in recent periods; procurement teams must plan for input-cost sensitivity and validate alternative magnet and motor designs where feasible.
Competitive landscape — capability mapping and strategic implications
The market is populated by established global component specialists and regional champions. Each competitor brings a different mix of scale, product depth, and OEM relationships. High-level capability positions — synthesized from supplier profiles, product announcements, and recent field bulletins — shape actionable choices for 2026:
- Robert Bosch GmbH (Gerlingen, Germany): Deep systems integration capability with proven DC and brushless motor platforms and robust anti-pinch implementations — a preferred partner for OEMs seeking end-to-end regulator assemblies and global support.
- DENSO Corporation (Kariya, Japan): Focus on compact, efficiency-optimized motors with integrated electronics; strong for platforms prioritizing packaging and thermal management.
- Valeo SA (Paris, France): Early mover on brushless, modular regulator designs and anti-trap detection; well positioned for platform modularization strategies.
- Brose Fahrzeugteile SE & Co. KG (Coburg, Germany): Strength in weight-optimized drives and door-architecture integration — attractive for OEMs seeking light-weighting without sacrificing functionality.
- Mitsuba Corporation (Tokyo, Japan) & Mabuchi Motor (Matsudo, Japan): Specialists in ultra-light and high-torque motor chemistries respectively — compelling options for cost- and weight-sensitive platforms.
- Johnson Electric (Hong Kong) & Continental AG (Hannover, Germany): Offerings range from compact gearmotors to full lift lines; useful where compatibility with broader vehicle electrical architectures matters.
- Aisin Seiki (Nagoya), Lucas TVS (Chennai) and Hi-Lex (Osaka): Regional strengths, proven volume manufacturing and price-competitive assemblies — important in regionally differentiated sourcing strategies.
Recent field activity — including regulator replacement bulletins from safety agencies — underscores the commercial impact of reliability and serviceability. For 2026 sourcing strategies, suppliers with fast aftermarket response capability and clear traceability will be advantaged.
Five strategic imperatives for 2026
- Embed functional-safety and anti-pinch compliance into the earliest design gates. Treat regulation-driven features as drivers of product architecture, not add-ons.
- Prioritize brushless motor and integrated-electronics roadmaps where lifecycle cost and NVH improvements materially affect competitive win rates.
- De-risk rare-earth exposure through dual-sourcing, alternative materials R&D, and long-term purchase agreements tied to indexed pricing clauses.
- Evaluate bolt-on consolidation opportunities selectively — target suppliers that close capability gaps (electronics, software, aftermarket logistics) rather than generic scale acquisitions.
- Shorten supplier qualification cycles by leveraging vendor evaluation platforms and pre-certified subsystems; incorporate supplier performance KPIs linked to failure-mode incidence and field-service metrics.
What the full PW Consulting study delivers (practical, executable assets)
We designed the full report to be a working toolkit for 2026: not just insight, but materials you can operationalize immediately. Highlights include:
- A calibrated market model and forecast engine (2026–2032) with scenario toggles for material cost shocks, regulatory acceleration, and EV penetration — delivered as editable financial templates.
- Vendor scorecards and a capability matrix benchmarking mechanical, electrical, software, and aftermarket strengths — intended for supplier selection and RFP shortlists.
- A regulatory and test-spec matrix cross-mapped to design requirements and supplier audit checklists — to compress approval timelines.
- Supply-chain maps with pinch-point identification and hedging playbooks for magnet and semiconductor exposure.
- Go-to-market playbooks for OEMs and suppliers: product positioning, pricing levers, and aftermarket monetization strategies.
- Acquisition target screening criteria and valuation heuristics to support M&A decisions in a fragmented landscape.
Note: in keeping with the “trailer” approach here, detailed segment tables and the granular regional and application splits — which are crucial for platform-specific sourcing decisions — are reserved for the full report and the downloadable model package.
How to use this intelligence in your 2026 planning cycle
- Short-term (0–6 months): Lock regulatory and functional-safety requirements into component RFQs; qualify at least two suppliers per platform for redundancy.
- Medium-term (6–18 months): Execute targeted R&D pilots on brushless and encoderless anti-pinch solutions; validate cost trade-offs under a range of material-price scenarios.
- Long-term (18–36 months): Consider strategic partnerships or M&A to acquire embedded electronics capability or aftermarket service networks that will sustain margins as content per vehicle increases.
Final note — why PW Consulting’s market study is a strategic instrument, not just analysis
For 2026 decision-makers, the difference between a timely, profitable initiative and a stranded program is rarely about headline growth — it’s about anticipating regulatory shifts, pre-qualifying suppliers who can meet functional-safety and serviceability demands, and hardening supply contracts against material volatility. Our study turns market growth projections (from current-year baselines through 2032) into executable options: which suppliers to pilot, which technologies to prioritize, and how to structure contracts that protect margins without stalling product launch timelines.
To access the full dataset, interactive model, and supplier scorecards — including the detailed regional and application splits that underpin targeted sourcing and product decisions — visit the PW Consulting report page and request the Automotive Power Window Motor Market full report and model package.
For detailed analysis of this topic, please visit the official page: Automotive Power Window Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com