

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Desktop/Benchtop (Tabletop) SEM Market to Reach USD 270M by 2032
By pmarketresearch, 2026-07-13
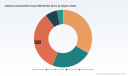
Tabletop (Desktop/Benchtop) Scanning Electron Microscope (SEM) Market — Strategic Preview for 2026 Decision-Making
This preview distills the most consequential, decision-ready insights from PW Consulting’s forthcoming Tabletop SEM Market study. It is written for executives, product leaders, investors, and procurement heads who must make high-stakes choices in 2026 — about capital investment, product roadmaps, channel strategy, and M&A — under accelerating technological change and evolving end‑user expectations. The full study contains the granular data, segment-level forecasts, and proprietary models that underpin the conclusions summarized here; this article demonstrates our analytical depth while intentionally withholding detailed segment tables and company market shares to preserve the value of the complete report.
Tabletop (Desktop/Benchtop) SEM Market
Why 2026 Matters: Inflection, Not Continuation
Through 2025 the tabletop SEM market has shown steady, resilient growth, driven by expanding adoption in R&D labs, quality control in high-value manufacturing, and growing demand where footprint, speed, and ease-of-use trump ultra-high vacuum capabilities. Using 2025 as the base year and a historical window of 2020–2025, our demand modeling projects a compound annual growth rate (CAGR) of 6.3% across the 2026–2032 forecast horizon. In dollar terms, the total market grows from a 2025 base into a market that approaches roughly USD 270.0 Million by 2032. That trajectory signals a market large enough to support new entrants and adjacent-product strategies, but small enough that differentiated go‑to‑market execution and service economics determine winners.
Tabletop (Desktop/Benchtop) SEM Market
High-Level Market Character
-
Moderate concentration: the three largest firms control a meaningful share of installed base and channel relationships, while five firms account for a clear majority of industry revenues. This dynamic creates both scale advantages for incumbents and local opportunity windows for focused challengers.
Tabletop (Desktop/Benchtop) SEM Market -
Technology as table stakes: improvements in resolution, integrated elemental analysis, and user-centered automation are now the baseline. Vendors are competing on analytics ecosystems, service models, and workflow integration more than raw imaging specs.
-
Purchasing behavior: buyers increasingly favor total cost of ownership (TCO), predictable uptime, and analytics-enabled workflows over lowest upfront cost. Financing, leasing, and subscription-style service bundles are changing procurement cadences.
What the Full Report Provides (Practical, Actionable, and Modeled)
-
Market sizing and a calibrated forecast model (2026–2032) built from a bottom-up approach that synthesizes shipment data, ASP trajectories, replacement cycles, and primary interviews with OEMs, distributors, and end users.
-
Segment analysis by region, product type (magnification/performance tiers), and application (life sciences, materials, quality control, etc.), with sensitivity runs and scenario-based outlooks for adoption curves.
-
Vendor profiling and competitive benchmarking that goes beyond public statements — assessing installed base, service depth, channel strength, product roadmaps, and software ecosystems.
-
Commercial playbooks: pricing ladders, service-package designs, distributor compensation models, and channel conflict matrices tailored for 2026 procurement cycles.
-
Go-to-market and M&A decision support: target screens, valuation considerations, synergy estimates, and integration risk checklists for strategic buyers and financial sponsors.
-
Operational risk and supply-chain heatmaps: key suppliers, component lead-time exposures, and mitigation strategies for OEMs and integrators.
-
Use-case financials and TCO calculators for lab managers and corporate procurement teams to justify CAPEX vs. OPEX paths.
Competitive Landscape — Current Players and Strategic Positions
The market features a mix of legacy microscopy firms and specialized tabletop providers. Leading incumbents have leveraged decades of brand equity, service networks, and R&D to move into the desktop form factor. Key strategic archetypes we identify include:
-
Full-spectrum incumbents with deep service footprints and advanced product lines — they play to enterprise labs that demand integration and global support.
-
Focused tabletop specialists offering highly cost-effective, compact systems with modular analytics — they target teaching labs, small R&D groups, and price-sensitive manufacturing QA teams.
-
Analytical innovators prioritizing software, AI-enhanced imaging, and correlative workflows — they aim to differentiate on outcomes rather than hardware alone.
Representative firms discussed in the report are long-standing names in the microscopy and analytical instruments space as well as agile specialists. Each is profiled on technology attributes (automation, analytical add-ons), commercial strengths (channel reach, service SLAs), and strategic priorities (platform play vs. hardware optimization). Our public preview deliberately avoids publishing granular market share tables here; the full profiles and comparative matrices are in the report.
Key Strategic Themes for 2026 Decisions
-
Prioritize TCO over headline price. Buyers are placing more value on uptime guarantees, consumable economics, and software-driven productivity. Vendors that repackage offerings into predictable recurring revenue (service + analytics subscriptions) will win share.
-
Differentiate through workflows, not hardware specs. Integrations with correlative microscopy, sample handling automation, and turnkey analytical apps lower adoption friction more effectively than incremental resolution gains.
-
Local service and rapid spare part availability matter. For nascent adopters in high-mix manufacturing environments, proximity of trained technicians is decisive in procurement evaluations.
-
Channel sophistication is a force-multiplier. Distributor training, co-marketing playbooks, and transparent lead routing unlock markets that raw product improvements cannot.
-
Supply-chain resilience is now strategic. OEMs must map single-source component risks and qualify dual suppliers for mission-critical subsystems to avoid shipment and service disruptions.
Actionable Recommendations — Tailored for Stakeholders
-
For OEM product leaders: Accelerate investment in software ecosystems (AI image analysis, standardized APIs) that enable third-party apps and service monetization. Reassess SKU complexity to improve margins and speed-to-market.
-
For channel partners and distributors: Build turnkey packages (instrument + training + consumables + SLA) and adopt value-based pricing. Develop local demo capabilities and virtual trial experiences to shorten sales cycles.
-
For lab directors and procurement: Use TCO and uptime scenarios to evaluate procurement between capital purchase and service/subscription models. Incorporate lifecycle support and data integration needs into procurement templates.
-
For investors and private equity: Look for targets that combine a differentiated analytical software stack with recurring revenues, or smaller OEMs with service networks that can be consolidated into regional platforms.
Risk & Sensitivity — What Could Move the Market
-
Macro shocks to R&D budgets or capital expenditure cycles can compress near-term orders; our forecast includes downside and upside scenarios to quantify impact on ASPs and shipment volumes.
-
Rapid advances in alternative imaging techniques or disruptive price-pressure entrants could accelerate commoditization in certain performance tiers; vendor differentiation via software and service reduces this risk.
-
Component shortages or geopolitical issues affecting supply lines will disproportionately penalize OEMs with single-source dependencies; our report maps the most sensitive components and offers mitigation playbooks.
How to Use This Research in 2026 Planning
Executives should treat the report as both a forecasting tool and a playbook. It is designed to be operationalized into quarterly planning cycles:
-
Translate market and scenario forecasts into discrete revenue and backlog targets by product line.
-
Use competitive benchmarking to set product feature priorities and R&D investment levels.
-
Deploy the commercial playbooks to redesign distributor incentives and service bundles in time for 2026 trade shows and procurement windows.
Why PW Consulting’s Approach Matters
Our modeling combines a bottoms-up build (shipments × ASP by offering class), primary interviews across the value chain, and validation against public financials and procurement cycles. We present not only point forecasts but also scenario stress-tests and decision support artifacts: pricing ladders, channel conflict matrices, M&A target screens, and TCO calculators that procurement teams can deploy immediately. These deliverables are purpose-built to inform 2026 budgets and strategic moves — from launching a new desktop SEM SKU to executing an acquisition that accelerates service coverage.
Next Steps — Accessing the Full Intelligence
This article is intentionally selective: we demonstrate analytical rigor while withholding the detailed segment tables, regional and application-level splits, company market shares, and pricing matrices that are central to executable strategies. For leaders who require the granular numbers, vendor-level market share analysis, downloadable financial models, and implementation playbooks to inform 2026 decision cycles, the complete PW Consulting Tabletop SEM Market report contains those assets and the underlying data files.
Contact PW Consulting to obtain the full study and accompanying toolset — including editable forecast models and executable commercial playbooks — and prepare your organization to act with clarity and confidence in 2026.
For detailed analysis of this topic, please visit the official page: Tabletop (Desktop/Benchtop) SEM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flyash Market to Reach USD 23.78 Billion by 2032 at 6.6% CAGR
By pmarketresearch, 2026-07-13
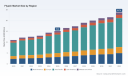
Flyash Market 2026 Strategic Brief: Turning Ash into Advantage
As companies finalize strategic plans for 2026, the Flyash Market is rapidly evolving from a commodity-byproduct into a strategic lever for construction decarbonization, supply-chain resilience, and value-creating M&A. PW Consulting’s Flyash Market study — built on a 2025 base year and covering historical trends (2020–2025) and a forecast window to 2032 — synthesizes macro trajectories, supplier economics, regulatory scenarios, and commercial playbooks so executives can convert uncertainty into action.
Flyash Market
Why this study matters for 2026 decisions
-
Clear macro momentum: After a resilient recovery from 2020–2025, the global flyash market reached an estimated USD 15.2 Billion in 2025 and is projected to grow at a 6.6% CAGR through 2032 — reaching roughly USD 23.8 Billion by the end of the forecast period. That growth reflects the combined effects of construction demand, higher utilization rates, and strategic repositioning of ash value chains.
Flyash Market -
Strategy windows are narrow: Supply-side shifts, evolving regulations, and an increasingly concentrated competitive landscape mean decisions taken in 2026 will disproportionately determine market share, margin pools, and access to low-carbon product premiums over the next five years.
Flyash Market -
From compliance to commerce: The flyash story is no longer only about waste management. It now intersects ESG reporting, low-carbon product development, infrastructure procurement policies, and regional industrial strategy. Firms that treat flyash as a strategic raw material — not an externality — will capture asymmetric benefits.
Five strategic implications for 2026
-
Supply tightening requires supply-side strategies. Reduced coal-fired generation in major producing markets and plant retirements have tightened fresh ash availability, supporting price levels and motivating beneficiation and reclamation investments. Companies should stress-test procurement under both tight- and loose-supply scenarios and evaluate near-term vertical integration vs. long-term offtake.
-
Regulatory signals are accelerating productization. Recent regulatory movements — from national ash-utilization mandates to changes proposed in 2026 that affect reuse and monitoring requirements — will change the economics of reuse vs. disposal. Organizations must run policy-sensitivity analyses to prioritize investments in processing technologies that unlock higher-value cementitious grades.
-
Concentration creates opportunities for challengers. The market exhibits moderate concentration at the top; incumbents enjoy scale, but gaps exist for specialized beneficiation, regional logistics, and low-carbon branding. New entrants and asset recyclers can win by combining localized logistics with differentiated product warranties.
-
Decarbonization is a revenue driver, not just a compliance cost. Low-carbon flyash blends and certified beneficiated products command a growing place in sustainable construction specifications. Corporates should quantify margin uplift from certified low-carbon offerings and map product development roadmaps against procurement cycles for major infrastructure programs.
-
Data and traceability will be table stakes. Procurement teams and public agencies increasingly demand chain-of-custody documentation and performance data. Investing in digital traceability and performance verification yields higher offtake rates and reduces commercial friction in tender processes.
Competitive landscape — who matters and why
-
Eco Material Technologies (US) — As a long-standing North American leader, this company leverages scale, logistics, and sustainable cement alternatives to defend premium positions. Their playbook underscores the value of integrated beneficiation and long-term supply agreements; competitors should evaluate whether to compete on scale, specialization, or service-led differentiation.
-
Charah Solutions Inc. (US) — A distributed network model provides reach into ready-mix and infrastructure markets. Charah’s strength is execution across multi-source supply and pond remediation — a template for companies that want to monetize legacy ash assets through services combined with materials sales.
-
Holcim Group (Switzerland) — Multinational scale plus a branded low-carbon product line demonstrates how legacy cement players are integrating flyash into decarbonization portfolios. Their approach signals the premium potential for certified, branded flyash products in developed-market procurement.
-
NTPC and BALCO (India) — State-linked and industrial producers in India show how policy alignment and utilization mandates can convert large volumes of ash into feedstock for cement, roads, and mineral composites. India’s high utilization trajectory offers a lesson in policy-driven market transformation.
-
Titan America LLC (US) — A materials-focused supplier with depth in cementitious markets; their strategy highlights the value of integrating flyash supply into broader cement and concrete value chains.
Collectively, the leading firms illustrate three repeatable routes to value: scale and logistics, product-certification and branding, and vertically integrated waste-to-material platforms. PW Consulting’s competitive chapter maps these archetypes and identifies subsegments where challengers can capture disproportionate returns.
Recent signals and market dynamics
-
Utilization is rising: Industry reporting through late 2025 indicates materially higher recycling rates in mature markets, reflecting both commercial demand and policy pressure. For example, recent association data shows a substantial share of coal ash being recycled, with concrete use a major destination.
-
India’s utilization push is real: Publicly reported national programs have driven near-complete utilization rates in some reporting periods, showing how directive policy can rapidly alter material flows and create industrial-scale markets for ash-derived products.
-
Price signals vary by source and geography: Reduced ash production in key producing countries has pulled prices upward in constrained markets, while beneficiation and logistics costs drive spreads across grades and geographies. These price dynamics create arbitrage opportunities for firms that can blend sourcing flexibility with beneficiation capability.
-
Regulatory divergence is a planning risk: Amendments proposed in 2026 in some jurisdictions aim to lower monitoring stringency and facilitate reuse; elsewhere, stricter stewardship and performance criteria are being adopted. Firms must prepare for divergent compliance regimes and build adaptive regulatory playbooks.
Risk heatmap and operational playbook
-
Top risks: feedstock scarcity, regulatory reversals, logistics bottlenecks, product-performance failures, and reputational incidents tied to contamination claims.
-
Mitigations we recommend in 2026: a) diversify feedstock and secure strategic offtake or tolling agreements; b) prioritize beneficiation investments that convert lower-grade ash into standardized cementitious inputs; c) deploy traceability and third-party certification to de-risk procurement; d) build modular processing assets to move quickly on local demand spikes.
-
KPIs and triggers: track usable-ash inventories, certified product throughput, long-term contract cover, NOM (net operating margin) by product grade, and regulatory-change lead indicators. PW’s report supplies a configurable KPI dashboard with trigger thresholds tailored to corporate risk tolerance.
What PW Consulting’s Flyash Market report delivers (practical contents)
-
An executive dashboard with the market’s macro trajectory (historical series and the 2026–2032 forecast at a 6.6% CAGR).
-
Supply-demand balances and price decks under three policy and supply scenarios, plus stress-tested sensitivity tables for key inputs.
-
Supplier and asset maps with facility-level intelligence, commercial scorecards, and a quantified concentration analysis (top-tier firms and share dynamics).
-
Operational playbooks: beneficiation economics, logistics optimization templates, quality control protocols, and product-specification guides for infrastructure tenders.
-
M&A and partnership shortlist with valuation principles, integration risk checklists, and quick-win synergies for buyers or JV partners.
-
ESG and compliance module: traceability frameworks, certification pathways, and stakeholder engagement templates for public procurement influence.
-
Interactive appendices: downloadable datasets, primary-interview excerpts, and scenario modelling tools to run bespoke what‑if analyses.
How to use the report in 2026 — a quick start agenda
-
Procurement teams: Use the price-deck scenarios and supplier scorecards to renegotiate long-term contracts and introduce performance-based indexing tied to certified low‑carbon blends.
-
Product and R&D: Prioritize certified beneficiation pathways that unlock premium positioning in sustainable construction specs and set up pilot programs with targeted offtakers.
-
Corporate development: Screen acquisition targets against the report’s M&A shortlist and run integration stress tests focused on logistics synergies and certification transferability.
-
Policy and government affairs: Deploy the policy-sensitivity analyses to shape constructive engagement with policymakers where utilization mandates and monitoring requirements are in flux.
PW Consulting’s Flyash Market study is purpose-built to be both strategic and operational: it equips boards with scenario-level insight while giving procurement, engineering, and M&A teams the calculators and playbooks they need to act. To preserve the competitive advantage for subscribers, the dossier intentionally omits minute public disclosure here — including granular region- and application-level splits and proprietary price curves — and instead houses those datasets, facility lists, and model templates within the full report package.
If your 2026 plan must reconcile decarbonization ambitions with margin preservation and secure access to industrial-grade inputs, treat flyash as a strategic portfolio item. The decisions you make this year — on sourcing architecture, beneficiation, long-term contracting, and selective M&A — will determine whether flyash is a constraint or a competitive differentiator for the next decade.
Access the full PW Consulting Flyash Market report to unlock the detailed segmentation tables, downloadable scenario models, supplier-level intelligence, and the action checklists you need to convert market signals into measurable advantage.
For detailed analysis of this topic, please visit the official page: Flyash Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thermal Infrared Imagers Market Poised for 11.11% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
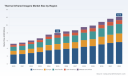
Thermal Infrared Imagers Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our new Thermal Infrared Imagers Market study. This briefing synthesizes the structural trends and executive-grade implications executives must factor into their 2026 planning cycles. The global market has expanded materially over the past half-decade — rising from a modest multi-billion-dollar base in 2020 to a 2025 baseline that anchors our forward view — and is projected to continue growing through the 2026–2032 forecast window at a compound annual growth rate of roughly 11.11%. That growth trajectory fundamentally changes how suppliers, system integrators, OEMs, and end users should allocate capital, secure supply, and design go-to-market strategies in 2026.
Thermal Infrared Imagers Market
Why this market matters for 2026 decisions
- Acceleration of application diversity. Thermal imagers are no longer niche instruments for defense and specialist industrial inspection — they are moving into mainstream safety (firefighting, industrial safety), security and perimeter surveillance, automotive ADAS/AV platforms, and medical/diagnostic applications. Each of these end-markets imposes distinct performance, certification, and service expectations.
- Technology bifurcation: cooled vs. uncooled. Advances in sensor fabrication and system integration are expanding the practical envelope for both cooled, high-sensitivity systems and compact, cost-effective uncooled modules. Product strategies that ignore either axis risk ceding either premium or volume segments.
- Vertical integration and scale matter. Manufacturers that combine optics, detectors, module production and software stacks are achieving meaningful cost and time-to-market advantages — a dynamic that will intensify as module-level demand from automotive and uncrewed platforms ramps in 2026.
- Regulation and safety standards influence product roadmaps. Automotive functional-safety standards and public-safety procurement frameworks are shaping which modules qualify for critical programs — compliance is a table-stakes capability for any supplier targeting ADAS/AV or first-responder contracts.
- Supply resilience and capacity expansion. Recent announcements of capacity increases and new product rollouts show that both supply constraints and strategic capacity plays will be central to competitive positioning this year.
What our research delivers — practical, executable content
The full PW Consulting report translates market momentum into tools executives can use immediately. Key deliverables include:
Thermal Infrared Imagers Market
- Market sizing and trend maps with a 2025 base year and granular forecasts across the 2026–2032 horizon, enabling capital planning and revenue-target setting.
- Segment frameworks by region, product type (cooled/uncooled and module vs. complete systems), and application — presented as strategic opportunity matrices rather than raw numbers, to support prioritization without overloading tactical teams.
- Technology readiness and roadmaps: sensor architectures, detector types, optics, and software stacks — and how each maps to end-use requirements.
- Supply-chain heatmaps and risk assessments, highlighting single-source dependencies, critical materials, and actionable mitigation levers.
- Competitor benchmarking and vendor scorecards that go beyond product lists to evaluate manufacturability, vertical integration, route-to-market, and services capability.
- Commercial playbooks: pricing archetypes, channel strategies, procurement recommendations for large buyers, and aftermarket/service models to drive recurring revenue.
- M&A and partnership scouting: prioritized targets and alliance structures to fast-track capability gaps.
- Scenario-driven investment cases and a 24-month activation plan with KPI dashboards tailored for board-level oversight.
Competitive landscape — strategic takeaways
The market remains contested: a handful of established players retain leadership through technology breadth and scale, while specialized vendors exploit niches with narrow, high-value propositions. Our analysis highlights several archetypes worth noting for 2026 strategy:
Thermal Infrared Imagers Market
- Integrated leader: Global incumbents who combine detector manufacturing, module production and systems integration are leveraging vertical scale to address both professional and emerging automotive demand. Their investments in module-level quality and software stacks create high barriers for late entrants.
- Volume disruptor: Firms focused on compact, cost-engineered sensors are forcing price-performance trade-offs, opening consumer and cost-sensitive industrial segments while nudging incumbents to rethink cost structures.
- High-end specialist: Companies that focus on cooled, high-resolution imagers retain advantages in demanding industrial inspection, scientific, and long-range defense applications where sensitivity and image fidelity command premium pricing and long product lifecycles.
- System integrators and safety OEMs: Producers of explosion-proof and firefighter-grade devices, and suppliers of networked security cameras, are turning thermal modules into complete propositions, emphasizing certification, ruggedization and serviceability.
Market concentration is moderate: the top three vendors do not dominate the entire space, and the top-five aggregate indicates meaningful headroom for differentiation and new entrants who combine technology and channels effectively.
Recent competitive moves that matter in 2026
- Automotive-grade module launches are reshaping supplier evaluations — OEMs and Tier-1s now demand module suppliers with functional-safety credentials and automotive-grade validation programs.
- Defense and ISR-focused product rollouts demonstrate renewed program spending and integration opportunities for long-range and missionized systems.
- Capacity expansions for cooled cameras signal supplier confidence in long-term demand for premium systems and highlight potential bottlenecks for buyers without secured supply arrangements.
- Industry events and knowledge campaigns continue to educate buyers on thermography use-cases in automation and predictive maintenance, broadening the TAM for thermal imaging beyond traditional buyers.
Six priority moves for executives in 2026
- Define a clear product-positioning bifurcation: Decide whether to pursue premium cooled systems, high-volume uncooled modules, or a hybrid portfolio. Positioning determines required capital intensity and channel choices.
- Pursue functional-safety and procurement compliance early if targeting automotive or public-safety segments. Certification timelines and validation programs should be built into 2026 roadmaps to avoid market exclusion.
- Secure strategic supply and manufacturing capacity. Where possible, negotiate multi-year offtake or co-investment agreements to de-risk ramp periods and lock-in attractive lead-times.
- Invest in software and edge analytics. Hardware commoditization is real — differentiation through image processing, AI-enabled analytics, cloud services and lifecycle management will sustain higher margins.
- Rework commercial models to capture aftermarket and services revenue. Field upgrades, calibration services, and subscription analytics convert single sales into annuity streams.
- Use M&A selectively to close capability gaps — target high-value IP, sensor fabrication access, or channel reach rather than broad consolidation which can dilute focus.
Decision framework & KPIs for 2026 planning
We recommend a concise evaluation framework executives can adopt immediately:
- Market alignment: Does the target segment map to a core strength (technology, channel, or service)?
- Time to compliance: How many quarters to achieve necessary functional-safety or procurement certifications?
- Supply robustness: What percentage of supply is single-source and what mitigation levers exist?
- Unit economics: Projected margin after software and service uplift at target volumes.
- Revenue mix targets: Share of product vs services and projected ARR build in a three-year horizon.
Establishing these KPIs in Q1–Q2 of 2026 will enable leadership teams to make go/no-go decisions before budget lock-in cycles later in the year.
How to use the full PW Consulting report
This preview is deliberately strategic and selective. The complete report supplies the granular intelligence procurement, R&D, commercial and corporate-development teams need to act with precision: detailed regional and application splits, product-level pricing benchmarks, vendor scorecards with comparative technical matrices, supply-chain maps with single-source risk flags, and financial models to populate board-level investment cases.
For teams running parallel pilots, our scenario models quantify outcomes across conservative, aggressive-growth, and disruption scenarios — enabling you to size investment, forecast breakeven horizons, and stress-test partner strategies under realistic supply and regulatory contingencies.
In closing, the thermal infrared imaging market in 2026 represents both opportunity and complexity: the market is expanding at a double-digit CAGR from a solid 2025 base, incumbents are consolidating advantages through integration, and new entrants are accelerating adoption through affordable sensing and smarter software. For executives, the immediate task is not merely to recognize growth, but to design repeatable commercial models that convert technological capability into sustainable margin and platform value. PW Consulting’s full study provides the playbook and the tactical instruments to do exactly that.
To access the full dataset, vendor benchmarks, and executable 24-month activation plan, please visit the PW Consulting report page or contact our advisory team for a bespoke briefing.
For detailed analysis of this topic, please visit the official page: Thermal Infrared Imagers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CT Systems Market to Hit USD 344.8 Million by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
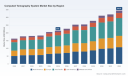
Computed Tomography System Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Consultant and Chief Industry Analyst, I present a focused preview of our Computed Tomography (CT) System Market study that will serve as a strategic primer for executive teams planning capital, product, and M&A decisions in 2026. This synopsis synthesizes the study’s most consequential, data‑driven signals — demonstrating our analytical depth — while intentionally withholding the full, granular segmentation tables and price schedules that clients access on the report landing page.
Computed Tomography System Market
Why this research matters for 2026
-
Macro trajectory clarity: The CT market exhibits a clear, multi‑year recovery and expansion. Our base year analysis (2025) captures a market that rose materially through the 2020–2025 period and enters 2026 on an upward growth path. Under the study’s forecast assumptions, the market expands at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 horizon, reaching materially higher levels by the end of the forecast window.
Computed Tomography System Market -
Decision timing: Hospitals, imaging service providers, and device OEMs face a near‑term inflection driven by new clinical protocols, reimbursement coding updates, and a wave of AI and photon‑counting introductions. The window to gain purchasing advantage and deployment lead times is narrow — 2026 is the year to convert strategy into action.
Computed Tomography System Market -
Practical, executable outputs: Our full report is oriented to move leaders from insight to execution with investment models, procurement playbooks, technology adoption curves, vendor scorecards, and regulatory pathway roadmaps.
High‑level market performance (concise, actionable)
PW Consulting’s topline assessment shows that the CT market grew steadily in the 2020–2025 historical window, reflecting technology refresh cycles, rising diagnostic demand, and incremental adoption of advanced imaging modalities. The study captures the market size at the 2025 base year and forecasts a continuation of growth into 2026 and beyond. Specifically, our forecasts show a material uplift in 2026 and sustained expansion through 2032, underpinned by a 6.98% CAGR for the forecast period.
These macro figures matter for three classes of decisions: capital expenditure timing for health systems, R&D and portfolio prioritization for OEMs, and value‑creation timing for financial sponsors. Because the expansion is broad‑based, organizations that align procurement windows and product roadmaps to the 2026–2028 inflection can capture outsized returns on both clinical outcomes and financial performance.
What the full report contains (practical depth)
-
Market sizing and scenario forecasts: Base‑year and historical tracking, plus low/most‑likely/high scenarios through 2032 that model capacity, reimbursement, and macroeconomic sensitivity.
-
Technology roadmap and clinical adoption curves: Detailed assessment of CT technological tiers (including photon‑counting and multi‑slice advances), AI integration patterns, and typical hospital upgrade cycles.
-
Buyer economics and TCO models: Total cost of ownership templates for new purchases, retrofit/upgrade economics, operating cost break‑evens, and utilization thresholds required to justify advanced modalities.
-
Competitive playbooks: Vendor scorecards that benchmark product capabilities, installed base strength, service footprint, and partnership ecosystems — designed to inform sourcing and alliance strategies.
-
Regulatory & reimbursement roadmaps: Step‑by‑step guides to navigate accreditation requirements, CPT/DRG coding updates, and payer engagement strategies to accelerate reimbursement for emergent CT technologies.
-
M&A and partnership scenarios: A prioritized list of capability gaps, target archetypes, and deal structures (JV, asset purchase, bundled services) most likely to create differentiated value in a consolidating market.
Market structure and concentration — implications
The competitive structure is characterized by a moderate concentration among the leading vendors. Our competitive concentration metrics indicate that the top three vendors account for a substantial portion of global revenue, and the top five command an even larger share. This creates a marketplace where incumbents set technical and commercial standards, but where nimble challengers can capture share by pairing local access, cost competitiveness, and targeted feature differentiation.
For buyers, this means two simultaneous imperatives: negotiate not only on price but on service level agreements, upgrade pathways, and AI/software roadmaps; and design procurement frameworks that allow technology substitution as new clinical evidence and reimbursement codes emerge.
Competitive landscape — current movers and patterns
-
GE HealthCare — Strengths: breadth of CT platforms, focus on cardiac and one‑beat imaging, and investments in AI workflow orchestration. Strategy implication: GE’s portfolio depth supports enterprise‑scale service contracts; counter‑strategies include modular upgrade pricing and outcome‑linked service bundles.
-
Siemens Healthineers AG — Strengths: premium single‑source systems, high‑speed scanning, and leadership in photon‑counting R&D. Strategy implication: Compete on integration and clinical differentiation; alternative vendors should emphasize cost of ownership and local service agility.
-
Koninklijke Philips N.V. — Strengths: spectral imaging, AI‑embedded workflows, and recent investments in sustainable global infrastructure. Strategy implication: Buyers will demand validated clinical workflows and interoperability assurances for spectral and AI features.
-
Canon Medical Systems — Strengths: strong CT engineering with AI enhancements and recent regulatory clearances broadening clinical applicability. Strategy implication: Canon’s regulatory momentum lowers adoption barriers for certain advanced features; procurement teams should seek demonstration projects to verify performance claims.
-
United Imaging Healthcare — Strengths: aggressive innovation cadence, AI‑based optimization, and platform mobility options with recent regulatory approvals that support US market expansion. Strategy implication: Their cost‑performance proposition will pressure incumbents on price and financing; strategic partners should evaluate interoperability and post‑sale support commitments.
-
Neusoft Medical Systems — Strengths: focus on affordable, accessible imaging for emerging markets. Strategy implication: Growth plays here are distribution‑led and price‑sensitive; OEMs targeting expansion should prioritize channel development and value‑packaging.
-
FUJIFILM Healthcare Solutions — Strengths: patient comfort and image quality with competitive mid‑tier offerings. Strategy implication: Differentiation via patient experience and workflow efficiency will be persuasive for ambulatory and outpatient imaging centers.
Recent developments that change strategy in 2026
-
Regulatory clearances: Several OEMs secured broadened clearances for AI‑enabled CT features and mobile/dual‑energy configurations over 2025–early 2026. These clearances shift the adoption calculus from experimental pilots to enterprise deployments.
-
Operational standards: Effective January 2026, new accreditation expectations require hospitals to adopt up‑to‑date CT imaging protocols. This will accelerate protocol harmonization and create demand for validated, vendor‑supported workflows.
-
Reimbursement signals: Industry guidance and payer interest in Category III CPT codes and DRG revisions for advanced CT technologies are advancing; hospitals are actively seeking CPT/DRG updates to monetize higher‑value imaging procedures.
-
Corporate footprint moves: Key vendors are investing in headquarters and facilities to strengthen R&D and sustainable operations — a signal that product roadmaps will be sufficiently funded to deliver new platform iterations.
Strategic implications and actionable recommendations for 2026
-
Prioritize technology roadmaps over single‑transaction buys. Require vendors to provide a five‑year upgrade and interoperability commitment tied to service credits.
-
Build an AI and photon‑counting readiness assessment into procurement: test datasets, clinical validation protocols, and workflow integration must be contractually defined.
-
Negotiate reimbursement support clauses. Given evolving CPT/DRG opportunities, include vendor cooperation on coding validation, outcomes data sharing, and payer engagement.
-
Consider blended financing and lifecycle procurement to match technology depreciation with clinical adoption curves — hybrid lease/purchase models will minimize stranded asset risk.
-
Adopt modular procurement pilots (clinical proof of concept, operational validation, then scale) to reduce deployment risk while capturing first‑mover advantages on advanced features.
-
Watch the competitive consolidation runway: with market concentration favoring top vendors but substantial share still available to challengers, targeted tuck‑ins and distribution partnerships remain high‑impact levers.
-
Stress‑test supply chain and service footprints. Vendor service network resilience will be a differentiator for multi‑site systems and time‑sensitive cardiac/oncology workflows.
What’s intentionally not in this preview (and why)
To preserve the investigative value and commercial integrity of our full market product, we have deliberately withheld granular regional and application splits, detailed unit pricing, and the full vendor scorecards you will find in the paid report. This summary is designed as a trailer — it demonstrates analytical rigor and strategic consequence, while directing teams to the full deliverable for procurement‑ready data tables, downloadable TCO models, and supplier comparison matrices.
Next steps
For executive teams preparing budgets, product leaders defining roadmaps, and corporate development groups sizing targets — our full Computed Tomography System Market report provides the executable intelligence to act in 2026. PW Consulting clients receive the complete dataset, step‑by‑step procurement playbooks, and facilitated workshops to translate findings into 90‑, 180‑, and 360‑day plans.
Contact PW Consulting to arrange a briefing and to obtain the full report, which includes the segmented market tables, vendor performance matrices, and customizable financial models required to operationalize the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Computed Tomography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fish Finders Market to Expand at 6.9% CAGR Through 2032
By pmarketresearch, 2026-07-13
Fish Finders Market — 2026 Strategic Preview
As PW Consulting’s lead industry analyst, I present a focused preview of our comprehensive Fish Finders Market study — designed to inform executive decisions in 2026 and beyond. This briefing demonstrates the analytical depth we bring to product planning, channel strategy, and M&A, while intentionally withholding select granular tables and segment-level datapoints to preserve the investigative value of the full report.
Fish Finders Market
Macro snapshot: where the market stands in 2026
The fish finders market has shown resilient expansion through the early 2020s, moving from a clear mid‑hundreds million USD footprint in 2020 to a base‑year total of USD 566 million in 2025. Our forecast modeling indicates a continuation of that trajectory: the global market is projected to approach roughly USD 857 million by the end of the forecast horizon, driven by a compound annual growth rate of 6.9% across the 2026–2032 period. Market concentration is meaningful — the top three vendors account for approximately 60% of industry revenues and the top five roughly 75% — underscoring a competitive landscape dominated by a small set of well‑resourced incumbents.
Fish Finders Market
Why this matters for 2026 decision-makers
Three immediate implications should shape boardroom priorities and tactical plans this year:
Fish Finders Market
- Product portfolio timing: Technological steps such as 360° scanning, forward‑facing CHIRP imaging, and castable wireless sonars are moving from novelty into buyer expectations. For firms planning 2026/2027 launch cycles, alignment with these capabilities — or clear differentiation strategies — will determine access to the fast‑growing segment of premium buyers.
- Channel and partner plays: OEM integrations with boatbuilders, and software partnerships (e.g., weather/fishing‑forecast overlays), are accelerating value capture. Channel expansion without integration roadmaps will underutilize investments in connectivity and data services.
- Regulatory and event risk management: Tournament rules that restrict forward‑facing sonar in a subset of events create both compliance obligations and marketing narratives. Firms must balance product enablement with configurable modes and firmware‑level controls to reduce exposure to event‑specific bans.
Key trends shaping demand and competitive dynamics
- Imaging evolution: Multi‑modal sonar (CHIRP, TruEcho enhancements, and high‑definition MEGA/Live imaging) is increasing the perceived utility of devices for sports and tournament anglers. This raises willingness to pay in premium segments while compressing margins for low‑end legacy devices.
- Portable & connected formats: Castable and smartphone‑integrated sonars are broadening the addressable market to shore, kayak, and ice anglers, creating an adjacent aftermarket and app‑monetization opportunities.
- Integrated navigation ecosystems: Chartplotter/sonar convergence, radar overlay integrations, and fishing‑forecast layers are shifting value toward ecosystems rather than standalone hardware, favoring vendors with software roadmaps and recurring service models.
- Consolidation and concentration: The CR3/CR5 figures indicate a market where scale matters for R&D and distribution. Expect vigorous competition for exclusive OEM deals and a steady cadence of bolt‑on acquisitions to fill capability gaps.
- Event and rules noise: Practical rules from major tournament organizers — for example, new limits on the use of forward‑facing sonar in specific events in 2026 — have introduced short‑term demand uncertainty and changed product feature priorities for tournament anglers and sponsors.
Competitive landscape — what to watch from the leaders and specialists
The market is populated by a mix of diversified electronics giants, niche innovators, and value players. Our report profiles each principal competitor and evaluates strategic posture across product platforms, channel strength, and software capabilities.
- Garmin (Olathe, KS): A clear innovation driver in integrated marine electronics — expanding its portfolio with 360° scanning solutions and motorized Spy Pole systems that combine TruEcho CHIRP performance with panoramic coverage. Garmin’s depth across consumer and pro channels makes it a baseline competitor for any premium offering.
- Lowrance (Olathe, KS): Focused on tournament‑grade imaging and side/down imaging systems. Lowrance’s product cadence is oriented toward competitive anglers and high‑performance recreational use, making it a benchmark for feature completeness in the sport segment.
- Humminbird (Eden Prairie, MN): Positioned as an innovator in forward‑facing MEGA imaging and livebait tracking; recent model introductions emphasize clarity and live‑tracking refinements that appeal to bass anglers and tournament circuits.
- Furuno (Kobe; North America ops in Vancouver, WA): Strong in both commercial and recreational applications, competing on robustness and multifunction displays with deep analog/digital sonar competence.
- Simrad Yachting (Kent, WA): Leveraging integrations with radar and fishing‑forecast overlays — recent rollouts of FishCast demonstrate how software can enhance offshore planning and create stickier user experiences.
- Raymarine (Southampton, UK): Competing on premium chartplotter/sonar combos with a focus on marine navigation and a differentiated operating system approach for user experience.
- HawkEye / NorCross (St. Louis, MO): Serving accessible portable and kayak/ice markets with value‑oriented handhelds and simple boat mounts; attractive for volume channels and mass‑market adoption strategies.
- SI‑TEX (Riverhead, NY): Focused on professional GPS/chart fishfinders, serving commercial and specialized users who prioritize durability and integration over consumer bells and whistles.
- Deeper (Vilnius, Lithuania): The castable, smartphone‑connected sonar specialist that has redefined the shore and kayak segments; represents a case study in how software UX and mobility can create new categories.
Recent market activity underscores these trajectories: Garmin’s introduction of a GT360 UHD transducer and motorized Spy Pole (March 2026) and Simrad’s deployment of FishCast forecast overlays (late 2025–early 2026) are tangible examples of hardware–software bundling and OEM partner expansion. Additionally, boatbuilders are increasingly pre‑fitting electronics suites under partnership agreements — a distribution dynamic that favors vendors with integrated system offers.
What the full PW Consulting report includes (operational value)
For executives planning product roadmaps, channel expansions, or M&A in 2026, our report provides an operational toolkit rather than a mere market narrative. Key deliverables include:
- Comprehensive market sizing and validated historical series (2020–2025) with model transparency and sensitivity testing.
- Forecast scenarios through 2032 (base, upside, downside) that incorporate technology adoption curves, regulation scenarios (including tournament rule impacts), and macroeconomic stress tests.
- Detailed competitive intelligence dossiers on leading vendors (product portfolios, go‑to‑market maps, partnership matrices, and product roadmaps) and a five‑year capability gap assessment.
- Segmentation frameworks (by product type, channel, and end‑use) with demand drivers and elasticities — note: high‑resolution segment tables are available in the full report portal.
- Component and supply‑chain analysis (key sensors, transducers, semiconductor dependencies, and cost migration forecasts) with supplier risk rankings.
- Commercial playbooks: pricing benchmarks, bundling strategies (hardware + software + services), subscription models for data overlays, and recommended channel mixes by target cohort.
- Regulatory & tournament compliance playbook to minimize product feature conflicts and to design configurable firmware that satisfies both rules and user expectations.
- M&A and partnership screening tool: candidate profiles, valuation heuristics, and integration risk checklists tailored to both strategic and financial sponsors.
Strategic recommendations for 2026
- Prioritize software ecosystems: Even modest hardware vendors should roadmap companion apps, forecast overlays, and firmware-updatable imaging algorithms to extend lifetime revenue and lock in customers.
- Design for configurability: Build feature‑level switches and competition‑mode presets to address tournament restrictions while preserving premium functionality for open events and casual anglers.
- Accelerate OEM partnerships: Target selective boatbuilders and kayak brands with bundled offers and data integrations that make the electronics suite the default purchase decision.
- Segment go‑to‑market rigorously: Separate propositions for tournament anglers, recreational buyers, and commercial/research customers — each cohort values different performance metrics and service expectations.
- Assess consolidation opportunities: Given current concentration levels, acquiring complementary imaging, app, or distribution assets can be an efficient path to scale and margin improvement.
Final note — the value of the full intelligence set
This preview highlights the structural moves and strategic choices that will define winners in 2026. The full PW Consulting Fish Finders Market report delivers the empirical foundation — including complete segment tables, price decks, and supplier mappings — required to move from strategy to execution. If your 2026 roadmap depends on accurate forecasts, scenario planning, or competitive playbooks, the full dossier provides the data and tools to act with conviction.
To access the complete study, including proprietary segment breakdowns and executable annexes, please consult the PW Consulting report portal or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Fish Finders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Pump Control Panels: PW Consulting Forecasts 5.21% CAGR Through 2032
By pmarketresearch, 2026-07-13
Industrial Pump Control Panels Market — Strategic Primer for 2026 Decision-Making
Between 2020 and 2025 the Industrial Pump Control Panels market evolved from a modest niche into a strategically important segment for industrial electrification and water/infrastructure spending. Our base-year analysis (2025) shows an industry that has grown steadily through the recent cyclical period and is projected to expand further across 2026–2032 at a compound annual growth rate of approximately 5.21%. The full-market sizing trajectory in our model — from the 2020 baseline through the 2025 reference point and across the 2026–2032 forecast window — underpins operational and capital decisions for suppliers, system integrators, OEMs, and end users planning multi-year programmes.
Industrial Pump Control Panels Market
Why this research matters for 2026 strategy
-
Timing. 2026 is a hinge year: regulatory updates, component cost volatility, and accelerating automation requirements are converging. Decisions made now on procurement strategy, product roadmaps, and partnership models will determine cost structure and addressable opportunity by 2028–2030.
Industrial Pump Control Panels Market -
Practical orientation. The study provides granular scenario analyses, supplier scorecards, and go‑to‑market playbooks that translate macro forecasts into executable initiatives — from SKU rationalisation to MRO contract renegotiation and field retrofits.
Industrial Pump Control Panels Market -
Risk-adjusted forecasting. Our model layers a base deterministic forecast with stress cases that reflect raw-material shocks and regulatory compliance costs, enabling finance and procurement teams to stress-test CAPEX and OPEX profiles prior to board approvals.
What the report delivers (practical contents)
-
Market sizing and growth scenarios — historic performance (2020–2025), a 2025 baseline, and detailed forecasts to 2032 with sensitivity bands tied to commodity and regulatory drivers.
-
Segmentation architecture — by region, panel type, and end-application — with an emphasis on demand pools that are most sensitive to digitalisation, outdoor-rated packaging, and renewable-driven architectures. (Note: detailed node-level splits are retained in the full report to preserve commercial value.)
-
Competitive benchmarking — capability maps, channel footprints, pricing anchors, and MRO/service propositions for the top global and specialist vendors.
-
Supply-chain diagnostics — BOM-level cost modelling, inventory velocity analysis, and levers for hedging or nearshoring critical components.
-
Regulatory and compliance playbook — interpretation of recent UL updates, practical certification timelines, and design implications for outdoor and hazardous‑area panels.
-
Commercial playbook — go-to-market options for OEMs, integrators, and distributors including channel economics, product modularisation, maintenance-as-a-service offers, and M&A screening criteria.
-
Implementation checklists and project-level templates — from specification to factory acceptance test (FAT) to commissioning and long-term service agreements.
Key market dynamics shaping 2026 decisions
-
Regulatory tightening and certification velocity. The 2025 revision to UL 508A — now active for industrial control panels operating below 1,000 volts — and subsequent ballots and comments have raised both documentation and testing expectations for manufacturers. For companies planning product launches or design changes in 2026, certification lead times and design-for-compliance must be built into product development roadmaps to avoid late-stage rework.
-
Raw-material volatility. Component cost input is a material driver of margins in panel manufacturing. Copper and steel price swings have introduced meaningful procurement risk: copper experienced extreme volatility in our observation window, with mid‑2025 averages substantially lower than a subsequent January 2026 spike that exceeded previous records. Steel prices also remain elevated. These movements make hedging policies, supplier diversification, and component substitution strategies essential for 2026 budgeting.
-
Shift toward intelligent, connected control. The incremental value of telemetry, predictive maintenance, and integration into enterprise systems is increasing procurement preference toward panels that bundle control hardware with monitoring and comms — often supplied via ecosystem partners rather than standalone vendors. This is creating new revenue streams (service, analytics) while changing procurement criteria for capital buyers.
-
Emerging project types. Renewables-linked pumping (e.g., solar-driven irrigation and remote water stations), urban water infrastructure renewal, and oil & gas retrofit programmes are changing specification mixes — greater demand for outdoor-rated, energy-efficient, and remotely manageable panels.
-
Market concentration and partnership opportunities. The market shows a moderate degree of fragmentation at the global level — a handful of global electrification and automation groups anchor large accounts while a number of specialist manufacturers and local integrators supply custom and municipal channels. This structure creates clear M&A and partnership opportunities for firms seeking to scale service offerings or adjacent system capabilities.
Competitive landscape: profiles and strategic takeaways
The competitive field blends global electrification and automation leaders with highly capable specialist fabricators and integrators. Key players profiled in the report include legacy multinationals and regional specialists. High-level strategic positions are summarised below to help you assess partners, competitors, and potential targets.
-
Schneider Electric — Well-established platform products (e.g., WELL‑GUARD pump panels) that cover large motor ratings and industry verticals. Strengths: global channel, integrated power products portfolio, and strong brand presence in both industrial and irrigation/oilfield segments.
-
Rockwell Automation — Focus on Allen‑Bradley NEMA pump control solutions with enclosed starter and soft-starter options. Strengths: deep automation stack, strong acceptance in process industries, and attractive integration with MES/SCADA layers.
-
Siemens — Technology-rich platforms (SIRIUS-based pump panels) with a value proposition around advanced control and global engineering services. Strengths: scalable product architectures and strong project-engineering capability for large infrastructure works.
-
Eaton — Broad industrial pump panel range as combination starters with robust enclosure options. Strengths: distribution reach and product ruggedness supporting outdoor and irrigation applications.
-
ABB — Offerings focused on full-voltage panels for outdoor installations with standard motor protection and safety features. Strengths: proven solutions for harsh environments and an installed-base service play.
-
Specialist fabricators (See Water, M‑Tech Control, Metropolitan Industries, Optimum Controls) — Custom UL-certified panels, rapid prototyping, and local service shops. Strengths: agility, deep local certifications, and strong municipal/water-sector relationships.
-
Xylem — Packaged systems combining pumps and packaged control with monitoring for water and wastewater applications. Strengths: systems integration and operational monitoring for distributed pumping assets.
Strategic implications: global OEMs compete on scale, systems integration, and breadth of offering, while specialists outperform on customisation, speed-to-delivery, and municipal channels. For 2026, alliances that blend scale with local compliance capability will unlock the fastest route to growth in regulated and retrofit-heavy markets.
Actionable recommendations for 2026 planning
-
Embed regulatory milestones in R&D roadmaps. If you are launching new panel lines or modifying designs, start certification work now — the UL 508A landscape has changed and approvals can be a gating item for bids in 2026.
-
Hedge raw-material exposure. Adopt layered procurement: negotiate fixed-price tranches for critical copper/steel inputs, qualify secondary suppliers, and model substitution scenarios for non-critical components.
-
Prioritise modular architectures and retrofittable intelligence. Design panels that allow field add-ons for monitoring and communications to capture aftermarket service revenue without re‑engineering base hardware.
-
Reassess channel economics. For OEMs and integrators, a hybrid model — direct large-account engineering plus local certified fabricator partnerships — will reduce delivery risk and improve compliance assurance for municipal and hazardous-area projects.
-
Screen M&A targets against three criteria: compliance/certification capabilities, installed-base service access, and engineering capacity for systems integration. Targets that close any one of these gaps accelerate market entry and reduce execution risk.
Next steps
This primer highlights the strategic levers and operational realities that will matter in 2026. For procurement, engineering, and corporate development leaders evaluating investments or bids this year, the full PW Consulting report provides the segment-level data, supplier scoring matrices, and downloadable tools required to execute with confidence. To access the complete dataset, node‑level splits, and the interactive financial model, please consult the source publication.
For detailed analysis of this topic, please visit the official page: Industrial Pump Control Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot Dogs & Sausages Market to Grow at a 3.01% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Hot Dogs and Sausages Market — Strategic Outlook for 2026 Corporate Decision‑Makers
PW Consulting’s Hot Dogs and Sausages Market introduction synthesizes proprietary modeling, public-sourced industry signals, and forward-looking scenario work to equip executives with the selective insights they need to act in 2026. The global market, measured on a 2025 base year, sits in the low hundreds of millions (USD, revenue unit: Million) and — under our baseline assumptions — grows at a compound annual growth rate (CAGR) of approximately 3.01% through the forecast horizon. By the end of the forecast window the model points to a material expansion in nominal market value, driven by a blend of volume resilience and premiumization.
Hot Dogs and Sausages Market
Why this study matters for decisions made in 2026
-
Timing matters: 2026 is the inflection point for several supply‑side capacity investments and integration plays that were initiated in 2024–2025. Companies that finalize sourcing, pricing and distribution choices now will be positioned to capture or defend share as new capacity and product flows come online later in the decade.
Hot Dogs and Sausages Market -
Commodity and feed volatility will shape margins. USDA projections for the 2026/27 U.S. corn crop indicate a reduction in output relative to the prior year and a projected season‑average price around USD 4.40/bushel. That dynamic tightens feed cost pass‑through opportunities and requires active hedging and procurement strategies from protein processors.
Hot Dogs and Sausages Market -
Protein supply trends matter. USDA projections to 2034 point to an overall increase in pork production during the projection period — a structural tailwind for sausage demand — but the benefit will be asymmetric across geographies and product tiers.
-
Standards and compliance create both constraints and defense mechanisms. Hot dogs are regulated under frankfurter standards of identity that specify allowable formulations and limits on mechanically separated meat; compliance is non‑negotiable and a regulatorily enforced source of brand differentiation.
-
Concentration and market dynamics. The category is meaningfully concentrated at the top: our market concentration metrics show that the top three and top five players control a majority share, creating advantages for scale but leaving tactical spaces for specialty and private‑label strategies.
-
Reputational exposure is a strategic risk. Recent recall activity in 2025 underscores how product integrity events can shift channel mix and accelerate retailer risk‑mitigation efforts, creating openings for trusted smaller brands and certified premium suppliers.
What the report contains — practical, transaction‑ready deliverables
-
Executive synthesis and investment thesis: a two‑page, board‑ready brief that maps risk/reward across the most likely 2026 strategic moves.
-
Market model and scenario engine: a dynamic forecast (2026–2032) built from bottom‑up SKU economics, trade flows and channel adoption assumptions, with three alternate macro scenarios (base, high growth, downside stress) ready for sensitivity analysis.
-
Supply‑side capacity map: plant‑level capacity, near‑term commissioning timelines and utilization scenarios (including a focused view on newly announced large builds and acquisitions).
-
Raw material risk matrix: corn and feed sensitivity, pork supply outlook, and an actionable set of procurement hedging strategies tied to likely margin outcomes.
-
Go‑to‑market and channel playbooks: retailer negotiation frameworks, prioritized tactics for foodservice and e‑commerce acceleration, and private‑label vs. branded ROI comparisons.
-
Quality and recall readiness frameworks: traceability, supplier audit protocols, and crisis communication templates informed by recent industry recalls.
-
M&A and partnership shortlists: a curated list of strategic acquisition targets and co‑packing partners prioritized by capability gaps, geographic fit and integration risk.
-
Primary research appendices and model workbook: anonymized retailer and operator interviews, consumer preference matrices, and the forecast spreadsheets used to run bespoke client scenarios.
Competitive landscape — key implications from recent corporate moves
The competitive map is actively being redrawn by capacity investments, consolidation and product differentiation. Select observations that should factor into 2026 strategy:
-
Major capacity additions will change bargaining dynamics. Recent public filings and announcements indicate that significant new processing capacity will be commissioned in the near term. One large entrant is advancing a greenfield sausage facility with multi‑annual throughput expectations; such additions tend to compress spot prices in the commissioning year before re‑balancing to differentiated product premiums.
-
M&A and plant acquisitions remain a fast route to scale. Strategic acquisitions of well‑located plants have been used to accelerate distribution reach and SKU breadth — a tactic that continues to be attractive for companies seeking rapid channel penetration without the lead time of new builds.
-
Premium and specialty players are expanding pockets of defensible margin. Brands that emphasize provenance, seasoning innovation and premium protein mixes are commanding favorable retail placement and higher velocity in select foodservice concepts.
-
Quality incidents are strategic inflection points. Large recalls disrupt category perceptions and accelerate retailer shelf rationalization. Organizations that can credibly demonstrate superior traceability and quality systems will see shortened payback on premium positioning post‑incident.
Strategic playbook — actionable options for 2026
-
Lock and layer input procurement: implement a layered hedging approach for feed commodities to smooth cost volatility through peak commissioning cycles.
-
Prioritize capacity flexibility: if building or expanding, design plants for multi‑protein capability (pork, beef, poultry) to capture shifting preference mixes and to mitigate single‑supply shocks.
-
Invest in traceability and quality automation: the marginal cost of enhanced QA is small relative to the cost of lost shelf access after a recall. Digital traceability is also a premium consumer proposition.
-
Segment your route‑to‑market: tailor products and pricing to the economics of retail, foodservice and e‑commerce rather than a one‑size approach; online channels require different pack formats and fulfillment logic.
-
Use M&A to buy speed to market: prioritize bolt‑on assets that solve distribution or margin shortages rather than trophy brands with high integration complexity.
-
Build a defensive private‑label strategy: use co‑packing partnerships to serve large retailers while protecting branded innovation at premium price points.
-
Prepare for regulatory scrutiny: understand identity standards and mechanically‑separated meat limits embedded in frankfurter regulations; design formulations and labeling practice to avoid enforcement setbacks.
2026 decision checklist for boards and operating executives
- Confirm whether your 2026 capital allocation prioritizes capacity, quality systems or brand innovation — run revised NPV under the base and downside commodity scenarios included in the full model.
- Stress‑test procurement contracts for corn and protein inputs against the USDA baseline and downside outcomes; set clear pass‑through rules for customers.
- Audit your recall readiness and supplier traceability; model the shelf‑access risk of a 30‑ to 90‑day disruption.
- Map your SKU portfolio to channel economics; identify three SKUs to expand in e‑commerce and three to rationalize in brick‑and‑mortar.
- Scan for opportunistic M&A targets that close your distribution or capability gaps within a 12–18 month integration horizon.
How to use this introduction — next steps
This introduction is designed as a concise strategic briefing: it surfaces the most consequential forces and the high‑leverage responses for 2026. The full PW Consulting Hot Dogs and Sausages Market report contains the detailed tables, plant‑level capacity maps, company scorecards, and the complete forecast workbook that decision‑makers will need to finalize capital plans, procurement contracts and commercial strategies. In keeping with the “trailer” principle, we have highlighted the directional findings and proprietary implications here while reserving the full subsegment and regional revenue matrices for the full report and the downloadable model.
If your priority is tactical readiness in 2026 — whether that is executing an acquisition, expanding capacity, or defending a retail roster — the full report provides the actionable analytics, vendor shortlists and scenario templates necessary to move from insight to decision within weeks, not months.
PW Consulting: we translate category complexity into a clear set of strategic choices and executable playbooks so you can capture value as the market reshapes over the next investment cycle.
For detailed analysis of this topic, please visit the official page: Hot Dogs and Sausages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fresh Pasta Market to Reach USD 14.1M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Fresh Pasta Market 2026: Strategic Imperatives for Winning in a Recovering and Premiumizing Category
Executive Preview
Between 2020 and 2025 the global fresh pasta market demonstrated steady expansion, growing from a modest base to reach an estimated USD 8.85 Million in 2025. Our updated market model projects continued momentum through the 2026–2032 forecast window at a compounded annual growth rate of 6.98%, arriving at roughly USD 14.1 Million by 2032. For senior executives planning 2026 strategies, these headline metrics quantify both the scale of near-term opportunity and the structural runway for premiumization, innovation, and channel reconfiguration.
Fresh Pasta Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a decisive year—many trade, regulatory and raw-material dynamics crystallize this year and will shape supply chains and margins for the rest of the decade.
Fresh Pasta Market -
Clarity: The report synthesizes five years of historical performance (2020–2025) with scenario-driven forecasts (2026–2032), converting macro growth into actionable strategic choices for product, channel, and M&A plays.
Fresh Pasta Market -
Focus: We translate market growth into commercial levers—where to invest in premium SKUs, when to scale foodservice partnerships, and how to structure hedges against volatility in durum wheat and trade policy.
What the full report delivers (practical, transaction-ready content)
-
Market architecture and demand maps: a reproducible framework that links consumer occasions (at-home dinner, premium takeout, catering) to SKU economics and margin pools.
-
Quantitative forecast model: customizable revenue and volume scenarios covering base, upside, and downside outcomes across 2026–2032—built to stress-test pricing, mix-shift, and channel reallocation decisions.
-
Supply-chain playbooks: actionable supplier scorecards, raw-material exposure matrices (including durum wheat risk indicators), and mitigation options such as dual-sourcing, mill partnerships, and onshore co-manufacturing templates.
-
Regulatory and trade impact matrix: localized impact assessments and a decision tree to evaluate tariff shocks, labeling mandates, and food-safety obligations in priority markets.
-
Commercial growth roadmaps: go-to-market playbooks for retail, foodservice, and direct-to-consumer channels that include assortment prioritization, price-pack architecture, POS merchandising, and trade promotion levers.
-
M&A and portfolio optimization guides: target screening criteria, synergy checklists, and integration templates for bolt-on acquisitions (manufacturing, gluten-free specialists, regional brands).
-
Operational KPIs & implementation trackers: monthly and quarterly dashboards for production throughput, cold-chain yield, SKU rationalization, and recall-response readiness.
Competitive landscape — what leading players reveal about market direction
The fresh pasta segment remains a hybrid of regional artisanal specialists, scale-oriented manufacturers serving large retail accounts, and niche innovators pushing fast-growing subcategories (e.g., gluten-free, buckwheat, organic). Market concentration indicates a clear top-end presence—our CR3 and CR5 metrics signal that the three largest producers account for a majority share of the market, while the five largest consolidate a meaningful incremental share. This structure produces both barriers and opportunities: scale delivers bargaining power with retailers and logistics economies, while craft and innovation capture premium margins and faster growth in affluent urban clusters.
Representative company cues:
-
Pastificio Gaetarelli (Salò, Italy) operates as an artisanal benchmark—its reported fresh pasta sales acceleration in 2024 underscores persistent consumer appetite for provenance and artisanal production techniques. Its emphasis on bronze-die extrusion and traditional recipes is emblematic of the premium differentiation strategy.
-
Mid-sized US players (e.g., Drake’s Fresh Pasta Company; Pastaio Pastas; Armanino Foods) illustrate the foodservice-retail hybrid model: broad product portfolios that include filled pastas for retail and institutional channels. Their route-to-market capabilities and private-label partnerships are critical levers for scale expansion.
-
Specialist innovators such as Lilly’s Fresh Pasta and BIORINA demonstrate the category’s product innovation frontier—refrigerated organic ranges, gluten-free lines, and alternative-flour variants (notably BIORINA’s recent 100% buckwheat fusilli launch in June 2026) appeal to allergen-conscious and health-forward consumers.
Structural dynamics shaping 2026 strategies
-
Raw-material volatility: durum wheat quality and global semolina flows remain the principal upstream risk. Recent quality downgrades in key supply origins have compressed high-spec premiums and widened input-cost variance. Firms with secured milling partnerships or vertical integration options will maintain margin resilience.
-
Trade and tariff uncertainty: policy actions announced in late 2025—particularly proposed high tariffs and antidumping measures targeting certain imported pasta—represent a near-term disruption for import-dependent channels and a structural opportunity for localization strategies and onshore co-manufacturing.
-
Regulatory modernization: tightened labeling and allergen disclosure rules under recent updates require operational changes in traceability and packaging. Companies must accelerate compliance audits, reformulate technical files, and upgrade line-side labeling systems to avoid market access friction.
-
Food safety & reputational risk: recent recall events in pre-cooked fresh pasta underline the need for enhanced environmental monitoring, cold-chain integrity, and crisis-response protocols—de-risking investments that also unlock premium contracts with foodservice customers.
-
Premiumization and health-led innovation: consumer willingness to pay for artisanal, organic, and specialty-flour pastas continues to rise—creating higher-margin opportunities that justify targeted capacity investments and brand investment.
Priority strategic moves for 2026
-
Hedge raw-material exposure: secure long-term semolina agreements with quality clauses, establish at least one alternative-origin sourcing lane, and consider partial integration with mill partners to stabilize costs and specs.
-
Localize manufacturing to mitigate tariff risk: evaluate brownfield retrofits or JV/co-packing arrangements in tariff-sensitive markets to preserve retail access and price competitiveness.
-
Product architecture to drive margin lift: concentrate SKUs into three core revenue engines—everyday retail essentials, premium artisanal lines, and innovation-led health options (gluten-free / alternative grains)—with dedicated P&Ls and separate go-to-market playbooks.
-
Scale food-safety investments: move from reactive recall management to proactive environmental surveillance and third-party validation; make food-safety certification a commercial differentiator for foodservice contracts.
-
M&A and capability buys: prioritize acquisitions that provide either (a) capacity in protected markets, (b) specialty capability (e.g., gluten-free formulations), or (c) distribution plugs into strong retail or foodservice routes.
-
Commercial economics: shift promotional spend from broad discounting to trade-funded reset programs and shopper-marketing interventions that preserve price realization while growing penetration.
Scenario thinking: three 2026 planning cases
-
Baseline continuity: steady growth aligned with the 6.98% CAGR, modest premiumization, and contained raw-material pressure. Priorities: efficiency and measured premium SKU rollout.
-
Protectionist shock: high import tariffs and protracted supply-chain disruption. Priorities: accelerate localization, renegotiate retail contracts, and deploy price-tiered SKUs to defend volume.
-
Premium-upside: rapid consumer shift to specialty diets and artisanal credentials. Priorities: capacity expansion, brand investment, and concentrated DTC/foodservice partnerships.
How to use the report in your 2026 playbook
Integrate the report’s forecast model into your 2026 budgeting cycle to stress test investment cases and set realistic sales targets by channel. Use the supplier risk dashboards to prioritize sourcing decisions in Q1. Structure M&A diligence lists and target scorecards from the report’s acquisition templates. And deploy the regulatory impact matrix to fast-track packaging and labeling changes necessary for uninterrupted market access.
Final note — the “trailer” promise
This article intentionally showcases the analytical depth and strategic frameworks embedded in our full Fresh Pasta Market study while withholding granular segment-level figures and proprietary console models. Those detailed splits—regional and application-level unit economics, SKU-level growth rates, and the full sensitivity outputs—are available exclusively in the complete report. For teams preparing 2026 decisions, the full dataset and playbooks will convert the market’s headline CAGR and projected size into executable actions that protect margins, unlock premium growth, and reduce regulatory and supply risks.
To access the full intelligence package—including interactive financial models, supplier scorecards, and deal-ready M&A screens—engage with PW Consulting’s Fresh Pasta Market report and make 2026 the year your organization converts category momentum into defensible, profitable growth.
For detailed analysis of this topic, please visit the official page: Fresh Pasta Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com