

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Desktop/Benchtop (Tabletop) SEM Market to Reach USD 270M by 2032

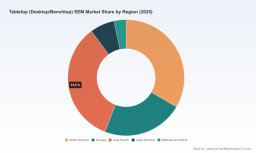
Tabletop (Desktop/Benchtop) Scanning Electron Microscope (SEM) Market — Strategic Preview for 2026 Decision-Making
This preview distills the most consequential, decision-ready insights from PW Consulting’s forthcoming Tabletop SEM Market study. It is written for executives, product leaders, investors, and procurement heads who must make high-stakes choices in 2026 — about capital investment, product roadmaps, channel strategy, and M&A — under accelerating technological change and evolving end‑user expectations. The full study contains the granular data, segment-level forecasts, and proprietary models that underpin the conclusions summarized here; this article demonstrates our analytical depth while intentionally withholding detailed segment tables and company market shares to preserve the value of the complete report.
Tabletop (Desktop/Benchtop) SEM Market
Why 2026 Matters: Inflection, Not Continuation
Through 2025 the tabletop SEM market has shown steady, resilient growth, driven by expanding adoption in R&D labs, quality control in high-value manufacturing, and growing demand where footprint, speed, and ease-of-use trump ultra-high vacuum capabilities. Using 2025 as the base year and a historical window of 2020–2025, our demand modeling projects a compound annual growth rate (CAGR) of 6.3% across the 2026–2032 forecast horizon. In dollar terms, the total market grows from a 2025 base into a market that approaches roughly USD 270.0 Million by 2032. That trajectory signals a market large enough to support new entrants and adjacent-product strategies, but small enough that differentiated go‑to‑market execution and service economics determine winners.
Tabletop (Desktop/Benchtop) SEM Market
High-Level Market Character
-
Moderate concentration: the three largest firms control a meaningful share of installed base and channel relationships, while five firms account for a clear majority of industry revenues. This dynamic creates both scale advantages for incumbents and local opportunity windows for focused challengers.
Tabletop (Desktop/Benchtop) SEM Market -
Technology as table stakes: improvements in resolution, integrated elemental analysis, and user-centered automation are now the baseline. Vendors are competing on analytics ecosystems, service models, and workflow integration more than raw imaging specs.
-
Purchasing behavior: buyers increasingly favor total cost of ownership (TCO), predictable uptime, and analytics-enabled workflows over lowest upfront cost. Financing, leasing, and subscription-style service bundles are changing procurement cadences.
What the Full Report Provides (Practical, Actionable, and Modeled)
-
Market sizing and a calibrated forecast model (2026–2032) built from a bottom-up approach that synthesizes shipment data, ASP trajectories, replacement cycles, and primary interviews with OEMs, distributors, and end users.
-
Segment analysis by region, product type (magnification/performance tiers), and application (life sciences, materials, quality control, etc.), with sensitivity runs and scenario-based outlooks for adoption curves.
-
Vendor profiling and competitive benchmarking that goes beyond public statements — assessing installed base, service depth, channel strength, product roadmaps, and software ecosystems.
-
Commercial playbooks: pricing ladders, service-package designs, distributor compensation models, and channel conflict matrices tailored for 2026 procurement cycles.
-
Go-to-market and M&A decision support: target screens, valuation considerations, synergy estimates, and integration risk checklists for strategic buyers and financial sponsors.
-
Operational risk and supply-chain heatmaps: key suppliers, component lead-time exposures, and mitigation strategies for OEMs and integrators.
-
Use-case financials and TCO calculators for lab managers and corporate procurement teams to justify CAPEX vs. OPEX paths.
Competitive Landscape — Current Players and Strategic Positions
The market features a mix of legacy microscopy firms and specialized tabletop providers. Leading incumbents have leveraged decades of brand equity, service networks, and R&D to move into the desktop form factor. Key strategic archetypes we identify include:
-
Full-spectrum incumbents with deep service footprints and advanced product lines — they play to enterprise labs that demand integration and global support.
-
Focused tabletop specialists offering highly cost-effective, compact systems with modular analytics — they target teaching labs, small R&D groups, and price-sensitive manufacturing QA teams.
-
Analytical innovators prioritizing software, AI-enhanced imaging, and correlative workflows — they aim to differentiate on outcomes rather than hardware alone.
Representative firms discussed in the report are long-standing names in the microscopy and analytical instruments space as well as agile specialists. Each is profiled on technology attributes (automation, analytical add-ons), commercial strengths (channel reach, service SLAs), and strategic priorities (platform play vs. hardware optimization). Our public preview deliberately avoids publishing granular market share tables here; the full profiles and comparative matrices are in the report.
Key Strategic Themes for 2026 Decisions
-
Prioritize TCO over headline price. Buyers are placing more value on uptime guarantees, consumable economics, and software-driven productivity. Vendors that repackage offerings into predictable recurring revenue (service + analytics subscriptions) will win share.
-
Differentiate through workflows, not hardware specs. Integrations with correlative microscopy, sample handling automation, and turnkey analytical apps lower adoption friction more effectively than incremental resolution gains.
-
Local service and rapid spare part availability matter. For nascent adopters in high-mix manufacturing environments, proximity of trained technicians is decisive in procurement evaluations.
-
Channel sophistication is a force-multiplier. Distributor training, co-marketing playbooks, and transparent lead routing unlock markets that raw product improvements cannot.
-
Supply-chain resilience is now strategic. OEMs must map single-source component risks and qualify dual suppliers for mission-critical subsystems to avoid shipment and service disruptions.
Actionable Recommendations — Tailored for Stakeholders
-
For OEM product leaders: Accelerate investment in software ecosystems (AI image analysis, standardized APIs) that enable third-party apps and service monetization. Reassess SKU complexity to improve margins and speed-to-market.
-
For channel partners and distributors: Build turnkey packages (instrument + training + consumables + SLA) and adopt value-based pricing. Develop local demo capabilities and virtual trial experiences to shorten sales cycles.
-
For lab directors and procurement: Use TCO and uptime scenarios to evaluate procurement between capital purchase and service/subscription models. Incorporate lifecycle support and data integration needs into procurement templates.
-
For investors and private equity: Look for targets that combine a differentiated analytical software stack with recurring revenues, or smaller OEMs with service networks that can be consolidated into regional platforms.
Risk & Sensitivity — What Could Move the Market
-
Macro shocks to R&D budgets or capital expenditure cycles can compress near-term orders; our forecast includes downside and upside scenarios to quantify impact on ASPs and shipment volumes.
-
Rapid advances in alternative imaging techniques or disruptive price-pressure entrants could accelerate commoditization in certain performance tiers; vendor differentiation via software and service reduces this risk.
-
Component shortages or geopolitical issues affecting supply lines will disproportionately penalize OEMs with single-source dependencies; our report maps the most sensitive components and offers mitigation playbooks.
How to Use This Research in 2026 Planning
Executives should treat the report as both a forecasting tool and a playbook. It is designed to be operationalized into quarterly planning cycles:
-
Translate market and scenario forecasts into discrete revenue and backlog targets by product line.
-
Use competitive benchmarking to set product feature priorities and R&D investment levels.
-
Deploy the commercial playbooks to redesign distributor incentives and service bundles in time for 2026 trade shows and procurement windows.
Why PW Consulting’s Approach Matters
Our modeling combines a bottoms-up build (shipments × ASP by offering class), primary interviews across the value chain, and validation against public financials and procurement cycles. We present not only point forecasts but also scenario stress-tests and decision support artifacts: pricing ladders, channel conflict matrices, M&A target screens, and TCO calculators that procurement teams can deploy immediately. These deliverables are purpose-built to inform 2026 budgets and strategic moves — from launching a new desktop SEM SKU to executing an acquisition that accelerates service coverage.
Next Steps — Accessing the Full Intelligence
This article is intentionally selective: we demonstrate analytical rigor while withholding the detailed segment tables, regional and application-level splits, company market shares, and pricing matrices that are central to executable strategies. For leaders who require the granular numbers, vendor-level market share analysis, downloadable financial models, and implementation playbooks to inform 2026 decision cycles, the complete PW Consulting Tabletop SEM Market report contains those assets and the underlying data files.
Contact PW Consulting to obtain the full study and accompanying toolset — including editable forecast models and executable commercial playbooks — and prepare your organization to act with clarity and confidence in 2026.
For detailed analysis of this topic, please visit the official page: Tabletop (Desktop/Benchtop) SEM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com