

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fresh Pasta Market to Reach USD 14.1M by 2032 at 6.98% CAGR

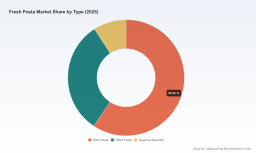
Fresh Pasta Market 2026: Strategic Imperatives for Winning in a Recovering and Premiumizing Category
Executive Preview
Between 2020 and 2025 the global fresh pasta market demonstrated steady expansion, growing from a modest base to reach an estimated USD 8.85 Million in 2025. Our updated market model projects continued momentum through the 2026–2032 forecast window at a compounded annual growth rate of 6.98%, arriving at roughly USD 14.1 Million by 2032. For senior executives planning 2026 strategies, these headline metrics quantify both the scale of near-term opportunity and the structural runway for premiumization, innovation, and channel reconfiguration.
Fresh Pasta Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a decisive year—many trade, regulatory and raw-material dynamics crystallize this year and will shape supply chains and margins for the rest of the decade.
Fresh Pasta Market -
Clarity: The report synthesizes five years of historical performance (2020–2025) with scenario-driven forecasts (2026–2032), converting macro growth into actionable strategic choices for product, channel, and M&A plays.
Fresh Pasta Market -
Focus: We translate market growth into commercial levers—where to invest in premium SKUs, when to scale foodservice partnerships, and how to structure hedges against volatility in durum wheat and trade policy.
What the full report delivers (practical, transaction-ready content)
-
Market architecture and demand maps: a reproducible framework that links consumer occasions (at-home dinner, premium takeout, catering) to SKU economics and margin pools.
-
Quantitative forecast model: customizable revenue and volume scenarios covering base, upside, and downside outcomes across 2026–2032—built to stress-test pricing, mix-shift, and channel reallocation decisions.
-
Supply-chain playbooks: actionable supplier scorecards, raw-material exposure matrices (including durum wheat risk indicators), and mitigation options such as dual-sourcing, mill partnerships, and onshore co-manufacturing templates.
-
Regulatory and trade impact matrix: localized impact assessments and a decision tree to evaluate tariff shocks, labeling mandates, and food-safety obligations in priority markets.
-
Commercial growth roadmaps: go-to-market playbooks for retail, foodservice, and direct-to-consumer channels that include assortment prioritization, price-pack architecture, POS merchandising, and trade promotion levers.
-
M&A and portfolio optimization guides: target screening criteria, synergy checklists, and integration templates for bolt-on acquisitions (manufacturing, gluten-free specialists, regional brands).
-
Operational KPIs & implementation trackers: monthly and quarterly dashboards for production throughput, cold-chain yield, SKU rationalization, and recall-response readiness.
Competitive landscape — what leading players reveal about market direction
The fresh pasta segment remains a hybrid of regional artisanal specialists, scale-oriented manufacturers serving large retail accounts, and niche innovators pushing fast-growing subcategories (e.g., gluten-free, buckwheat, organic). Market concentration indicates a clear top-end presence—our CR3 and CR5 metrics signal that the three largest producers account for a majority share of the market, while the five largest consolidate a meaningful incremental share. This structure produces both barriers and opportunities: scale delivers bargaining power with retailers and logistics economies, while craft and innovation capture premium margins and faster growth in affluent urban clusters.
Representative company cues:
-
Pastificio Gaetarelli (Salò, Italy) operates as an artisanal benchmark—its reported fresh pasta sales acceleration in 2024 underscores persistent consumer appetite for provenance and artisanal production techniques. Its emphasis on bronze-die extrusion and traditional recipes is emblematic of the premium differentiation strategy.
-
Mid-sized US players (e.g., Drake’s Fresh Pasta Company; Pastaio Pastas; Armanino Foods) illustrate the foodservice-retail hybrid model: broad product portfolios that include filled pastas for retail and institutional channels. Their route-to-market capabilities and private-label partnerships are critical levers for scale expansion.
-
Specialist innovators such as Lilly’s Fresh Pasta and BIORINA demonstrate the category’s product innovation frontier—refrigerated organic ranges, gluten-free lines, and alternative-flour variants (notably BIORINA’s recent 100% buckwheat fusilli launch in June 2026) appeal to allergen-conscious and health-forward consumers.
Structural dynamics shaping 2026 strategies
-
Raw-material volatility: durum wheat quality and global semolina flows remain the principal upstream risk. Recent quality downgrades in key supply origins have compressed high-spec premiums and widened input-cost variance. Firms with secured milling partnerships or vertical integration options will maintain margin resilience.
-
Trade and tariff uncertainty: policy actions announced in late 2025—particularly proposed high tariffs and antidumping measures targeting certain imported pasta—represent a near-term disruption for import-dependent channels and a structural opportunity for localization strategies and onshore co-manufacturing.
-
Regulatory modernization: tightened labeling and allergen disclosure rules under recent updates require operational changes in traceability and packaging. Companies must accelerate compliance audits, reformulate technical files, and upgrade line-side labeling systems to avoid market access friction.
-
Food safety & reputational risk: recent recall events in pre-cooked fresh pasta underline the need for enhanced environmental monitoring, cold-chain integrity, and crisis-response protocols—de-risking investments that also unlock premium contracts with foodservice customers.
-
Premiumization and health-led innovation: consumer willingness to pay for artisanal, organic, and specialty-flour pastas continues to rise—creating higher-margin opportunities that justify targeted capacity investments and brand investment.
Priority strategic moves for 2026
-
Hedge raw-material exposure: secure long-term semolina agreements with quality clauses, establish at least one alternative-origin sourcing lane, and consider partial integration with mill partners to stabilize costs and specs.
-
Localize manufacturing to mitigate tariff risk: evaluate brownfield retrofits or JV/co-packing arrangements in tariff-sensitive markets to preserve retail access and price competitiveness.
-
Product architecture to drive margin lift: concentrate SKUs into three core revenue engines—everyday retail essentials, premium artisanal lines, and innovation-led health options (gluten-free / alternative grains)—with dedicated P&Ls and separate go-to-market playbooks.
-
Scale food-safety investments: move from reactive recall management to proactive environmental surveillance and third-party validation; make food-safety certification a commercial differentiator for foodservice contracts.
-
M&A and capability buys: prioritize acquisitions that provide either (a) capacity in protected markets, (b) specialty capability (e.g., gluten-free formulations), or (c) distribution plugs into strong retail or foodservice routes.
-
Commercial economics: shift promotional spend from broad discounting to trade-funded reset programs and shopper-marketing interventions that preserve price realization while growing penetration.
Scenario thinking: three 2026 planning cases
-
Baseline continuity: steady growth aligned with the 6.98% CAGR, modest premiumization, and contained raw-material pressure. Priorities: efficiency and measured premium SKU rollout.
-
Protectionist shock: high import tariffs and protracted supply-chain disruption. Priorities: accelerate localization, renegotiate retail contracts, and deploy price-tiered SKUs to defend volume.
-
Premium-upside: rapid consumer shift to specialty diets and artisanal credentials. Priorities: capacity expansion, brand investment, and concentrated DTC/foodservice partnerships.
How to use the report in your 2026 playbook
Integrate the report’s forecast model into your 2026 budgeting cycle to stress test investment cases and set realistic sales targets by channel. Use the supplier risk dashboards to prioritize sourcing decisions in Q1. Structure M&A diligence lists and target scorecards from the report’s acquisition templates. And deploy the regulatory impact matrix to fast-track packaging and labeling changes necessary for uninterrupted market access.
Final note — the “trailer” promise
This article intentionally showcases the analytical depth and strategic frameworks embedded in our full Fresh Pasta Market study while withholding granular segment-level figures and proprietary console models. Those detailed splits—regional and application-level unit economics, SKU-level growth rates, and the full sensitivity outputs—are available exclusively in the complete report. For teams preparing 2026 decisions, the full dataset and playbooks will convert the market’s headline CAGR and projected size into executable actions that protect margins, unlock premium growth, and reduce regulatory and supply risks.
To access the full intelligence package—including interactive financial models, supplier scorecards, and deal-ready M&A screens—engage with PW Consulting’s Fresh Pasta Market report and make 2026 the year your organization converts category momentum into defensible, profitable growth.
For detailed analysis of this topic, please visit the official page: Fresh Pasta Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com