

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Pump Control Panels: PW Consulting Forecasts 5.21% CAGR Through 2032

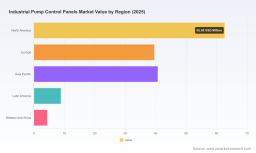
Industrial Pump Control Panels Market — Strategic Primer for 2026 Decision-Making
Between 2020 and 2025 the Industrial Pump Control Panels market evolved from a modest niche into a strategically important segment for industrial electrification and water/infrastructure spending. Our base-year analysis (2025) shows an industry that has grown steadily through the recent cyclical period and is projected to expand further across 2026–2032 at a compound annual growth rate of approximately 5.21%. The full-market sizing trajectory in our model — from the 2020 baseline through the 2025 reference point and across the 2026–2032 forecast window — underpins operational and capital decisions for suppliers, system integrators, OEMs, and end users planning multi-year programmes.
Industrial Pump Control Panels Market
Why this research matters for 2026 strategy
-
Timing. 2026 is a hinge year: regulatory updates, component cost volatility, and accelerating automation requirements are converging. Decisions made now on procurement strategy, product roadmaps, and partnership models will determine cost structure and addressable opportunity by 2028–2030.
Industrial Pump Control Panels Market -
Practical orientation. The study provides granular scenario analyses, supplier scorecards, and go‑to‑market playbooks that translate macro forecasts into executable initiatives — from SKU rationalisation to MRO contract renegotiation and field retrofits.
Industrial Pump Control Panels Market -
Risk-adjusted forecasting. Our model layers a base deterministic forecast with stress cases that reflect raw-material shocks and regulatory compliance costs, enabling finance and procurement teams to stress-test CAPEX and OPEX profiles prior to board approvals.
What the report delivers (practical contents)
-
Market sizing and growth scenarios — historic performance (2020–2025), a 2025 baseline, and detailed forecasts to 2032 with sensitivity bands tied to commodity and regulatory drivers.
-
Segmentation architecture — by region, panel type, and end-application — with an emphasis on demand pools that are most sensitive to digitalisation, outdoor-rated packaging, and renewable-driven architectures. (Note: detailed node-level splits are retained in the full report to preserve commercial value.)
-
Competitive benchmarking — capability maps, channel footprints, pricing anchors, and MRO/service propositions for the top global and specialist vendors.
-
Supply-chain diagnostics — BOM-level cost modelling, inventory velocity analysis, and levers for hedging or nearshoring critical components.
-
Regulatory and compliance playbook — interpretation of recent UL updates, practical certification timelines, and design implications for outdoor and hazardous‑area panels.
-
Commercial playbook — go-to-market options for OEMs, integrators, and distributors including channel economics, product modularisation, maintenance-as-a-service offers, and M&A screening criteria.
-
Implementation checklists and project-level templates — from specification to factory acceptance test (FAT) to commissioning and long-term service agreements.
Key market dynamics shaping 2026 decisions
-
Regulatory tightening and certification velocity. The 2025 revision to UL 508A — now active for industrial control panels operating below 1,000 volts — and subsequent ballots and comments have raised both documentation and testing expectations for manufacturers. For companies planning product launches or design changes in 2026, certification lead times and design-for-compliance must be built into product development roadmaps to avoid late-stage rework.
-
Raw-material volatility. Component cost input is a material driver of margins in panel manufacturing. Copper and steel price swings have introduced meaningful procurement risk: copper experienced extreme volatility in our observation window, with mid‑2025 averages substantially lower than a subsequent January 2026 spike that exceeded previous records. Steel prices also remain elevated. These movements make hedging policies, supplier diversification, and component substitution strategies essential for 2026 budgeting.
-
Shift toward intelligent, connected control. The incremental value of telemetry, predictive maintenance, and integration into enterprise systems is increasing procurement preference toward panels that bundle control hardware with monitoring and comms — often supplied via ecosystem partners rather than standalone vendors. This is creating new revenue streams (service, analytics) while changing procurement criteria for capital buyers.
-
Emerging project types. Renewables-linked pumping (e.g., solar-driven irrigation and remote water stations), urban water infrastructure renewal, and oil & gas retrofit programmes are changing specification mixes — greater demand for outdoor-rated, energy-efficient, and remotely manageable panels.
-
Market concentration and partnership opportunities. The market shows a moderate degree of fragmentation at the global level — a handful of global electrification and automation groups anchor large accounts while a number of specialist manufacturers and local integrators supply custom and municipal channels. This structure creates clear M&A and partnership opportunities for firms seeking to scale service offerings or adjacent system capabilities.
Competitive landscape: profiles and strategic takeaways
The competitive field blends global electrification and automation leaders with highly capable specialist fabricators and integrators. Key players profiled in the report include legacy multinationals and regional specialists. High-level strategic positions are summarised below to help you assess partners, competitors, and potential targets.
-
Schneider Electric — Well-established platform products (e.g., WELL‑GUARD pump panels) that cover large motor ratings and industry verticals. Strengths: global channel, integrated power products portfolio, and strong brand presence in both industrial and irrigation/oilfield segments.
-
Rockwell Automation — Focus on Allen‑Bradley NEMA pump control solutions with enclosed starter and soft-starter options. Strengths: deep automation stack, strong acceptance in process industries, and attractive integration with MES/SCADA layers.
-
Siemens — Technology-rich platforms (SIRIUS-based pump panels) with a value proposition around advanced control and global engineering services. Strengths: scalable product architectures and strong project-engineering capability for large infrastructure works.
-
Eaton — Broad industrial pump panel range as combination starters with robust enclosure options. Strengths: distribution reach and product ruggedness supporting outdoor and irrigation applications.
-
ABB — Offerings focused on full-voltage panels for outdoor installations with standard motor protection and safety features. Strengths: proven solutions for harsh environments and an installed-base service play.
-
Specialist fabricators (See Water, M‑Tech Control, Metropolitan Industries, Optimum Controls) — Custom UL-certified panels, rapid prototyping, and local service shops. Strengths: agility, deep local certifications, and strong municipal/water-sector relationships.
-
Xylem — Packaged systems combining pumps and packaged control with monitoring for water and wastewater applications. Strengths: systems integration and operational monitoring for distributed pumping assets.
Strategic implications: global OEMs compete on scale, systems integration, and breadth of offering, while specialists outperform on customisation, speed-to-delivery, and municipal channels. For 2026, alliances that blend scale with local compliance capability will unlock the fastest route to growth in regulated and retrofit-heavy markets.
Actionable recommendations for 2026 planning
-
Embed regulatory milestones in R&D roadmaps. If you are launching new panel lines or modifying designs, start certification work now — the UL 508A landscape has changed and approvals can be a gating item for bids in 2026.
-
Hedge raw-material exposure. Adopt layered procurement: negotiate fixed-price tranches for critical copper/steel inputs, qualify secondary suppliers, and model substitution scenarios for non-critical components.
-
Prioritise modular architectures and retrofittable intelligence. Design panels that allow field add-ons for monitoring and communications to capture aftermarket service revenue without re‑engineering base hardware.
-
Reassess channel economics. For OEMs and integrators, a hybrid model — direct large-account engineering plus local certified fabricator partnerships — will reduce delivery risk and improve compliance assurance for municipal and hazardous-area projects.
-
Screen M&A targets against three criteria: compliance/certification capabilities, installed-base service access, and engineering capacity for systems integration. Targets that close any one of these gaps accelerate market entry and reduce execution risk.
Next steps
This primer highlights the strategic levers and operational realities that will matter in 2026. For procurement, engineering, and corporate development leaders evaluating investments or bids this year, the full PW Consulting report provides the segment-level data, supplier scoring matrices, and downloadable tools required to execute with confidence. To access the complete dataset, node‑level splits, and the interactive financial model, please consult the source publication.
For detailed analysis of this topic, please visit the official page: Industrial Pump Control Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com