

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flyash Market to Reach USD 23.78 Billion by 2032 at 6.6% CAGR

Flyash Market 2026 Strategic Brief: Turning Ash into Advantage
As companies finalize strategic plans for 2026, the Flyash Market is rapidly evolving from a commodity-byproduct into a strategic lever for construction decarbonization, supply-chain resilience, and value-creating M&A. PW Consulting’s Flyash Market study — built on a 2025 base year and covering historical trends (2020–2025) and a forecast window to 2032 — synthesizes macro trajectories, supplier economics, regulatory scenarios, and commercial playbooks so executives can convert uncertainty into action.
Flyash Market
Why this study matters for 2026 decisions
-
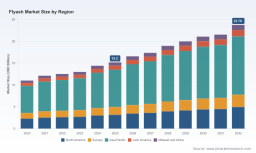
Clear macro momentum: After a resilient recovery from 2020–2025, the global flyash market reached an estimated USD 15.2 Billion in 2025 and is projected to grow at a 6.6% CAGR through 2032 — reaching roughly USD 23.8 Billion by the end of the forecast period. That growth reflects the combined effects of construction demand, higher utilization rates, and strategic repositioning of ash value chains.
Flyash Market -
Strategy windows are narrow: Supply-side shifts, evolving regulations, and an increasingly concentrated competitive landscape mean decisions taken in 2026 will disproportionately determine market share, margin pools, and access to low-carbon product premiums over the next five years.
Flyash Market -
From compliance to commerce: The flyash story is no longer only about waste management. It now intersects ESG reporting, low-carbon product development, infrastructure procurement policies, and regional industrial strategy. Firms that treat flyash as a strategic raw material — not an externality — will capture asymmetric benefits.
Five strategic implications for 2026
-
Supply tightening requires supply-side strategies. Reduced coal-fired generation in major producing markets and plant retirements have tightened fresh ash availability, supporting price levels and motivating beneficiation and reclamation investments. Companies should stress-test procurement under both tight- and loose-supply scenarios and evaluate near-term vertical integration vs. long-term offtake.
-
Regulatory signals are accelerating productization. Recent regulatory movements — from national ash-utilization mandates to changes proposed in 2026 that affect reuse and monitoring requirements — will change the economics of reuse vs. disposal. Organizations must run policy-sensitivity analyses to prioritize investments in processing technologies that unlock higher-value cementitious grades.
-
Concentration creates opportunities for challengers. The market exhibits moderate concentration at the top; incumbents enjoy scale, but gaps exist for specialized beneficiation, regional logistics, and low-carbon branding. New entrants and asset recyclers can win by combining localized logistics with differentiated product warranties.
-
Decarbonization is a revenue driver, not just a compliance cost. Low-carbon flyash blends and certified beneficiated products command a growing place in sustainable construction specifications. Corporates should quantify margin uplift from certified low-carbon offerings and map product development roadmaps against procurement cycles for major infrastructure programs.
-
Data and traceability will be table stakes. Procurement teams and public agencies increasingly demand chain-of-custody documentation and performance data. Investing in digital traceability and performance verification yields higher offtake rates and reduces commercial friction in tender processes.
Competitive landscape — who matters and why
-
Eco Material Technologies (US) — As a long-standing North American leader, this company leverages scale, logistics, and sustainable cement alternatives to defend premium positions. Their playbook underscores the value of integrated beneficiation and long-term supply agreements; competitors should evaluate whether to compete on scale, specialization, or service-led differentiation.
-
Charah Solutions Inc. (US) — A distributed network model provides reach into ready-mix and infrastructure markets. Charah’s strength is execution across multi-source supply and pond remediation — a template for companies that want to monetize legacy ash assets through services combined with materials sales.
-
Holcim Group (Switzerland) — Multinational scale plus a branded low-carbon product line demonstrates how legacy cement players are integrating flyash into decarbonization portfolios. Their approach signals the premium potential for certified, branded flyash products in developed-market procurement.
-
NTPC and BALCO (India) — State-linked and industrial producers in India show how policy alignment and utilization mandates can convert large volumes of ash into feedstock for cement, roads, and mineral composites. India’s high utilization trajectory offers a lesson in policy-driven market transformation.
-
Titan America LLC (US) — A materials-focused supplier with depth in cementitious markets; their strategy highlights the value of integrating flyash supply into broader cement and concrete value chains.
Collectively, the leading firms illustrate three repeatable routes to value: scale and logistics, product-certification and branding, and vertically integrated waste-to-material platforms. PW Consulting’s competitive chapter maps these archetypes and identifies subsegments where challengers can capture disproportionate returns.
Recent signals and market dynamics
-
Utilization is rising: Industry reporting through late 2025 indicates materially higher recycling rates in mature markets, reflecting both commercial demand and policy pressure. For example, recent association data shows a substantial share of coal ash being recycled, with concrete use a major destination.
-
India’s utilization push is real: Publicly reported national programs have driven near-complete utilization rates in some reporting periods, showing how directive policy can rapidly alter material flows and create industrial-scale markets for ash-derived products.
-
Price signals vary by source and geography: Reduced ash production in key producing countries has pulled prices upward in constrained markets, while beneficiation and logistics costs drive spreads across grades and geographies. These price dynamics create arbitrage opportunities for firms that can blend sourcing flexibility with beneficiation capability.
-
Regulatory divergence is a planning risk: Amendments proposed in 2026 in some jurisdictions aim to lower monitoring stringency and facilitate reuse; elsewhere, stricter stewardship and performance criteria are being adopted. Firms must prepare for divergent compliance regimes and build adaptive regulatory playbooks.
Risk heatmap and operational playbook
-
Top risks: feedstock scarcity, regulatory reversals, logistics bottlenecks, product-performance failures, and reputational incidents tied to contamination claims.
-
Mitigations we recommend in 2026: a) diversify feedstock and secure strategic offtake or tolling agreements; b) prioritize beneficiation investments that convert lower-grade ash into standardized cementitious inputs; c) deploy traceability and third-party certification to de-risk procurement; d) build modular processing assets to move quickly on local demand spikes.
-
KPIs and triggers: track usable-ash inventories, certified product throughput, long-term contract cover, NOM (net operating margin) by product grade, and regulatory-change lead indicators. PW’s report supplies a configurable KPI dashboard with trigger thresholds tailored to corporate risk tolerance.
What PW Consulting’s Flyash Market report delivers (practical contents)
-
An executive dashboard with the market’s macro trajectory (historical series and the 2026–2032 forecast at a 6.6% CAGR).
-
Supply-demand balances and price decks under three policy and supply scenarios, plus stress-tested sensitivity tables for key inputs.
-
Supplier and asset maps with facility-level intelligence, commercial scorecards, and a quantified concentration analysis (top-tier firms and share dynamics).
-
Operational playbooks: beneficiation economics, logistics optimization templates, quality control protocols, and product-specification guides for infrastructure tenders.
-
M&A and partnership shortlist with valuation principles, integration risk checklists, and quick-win synergies for buyers or JV partners.
-
ESG and compliance module: traceability frameworks, certification pathways, and stakeholder engagement templates for public procurement influence.
-
Interactive appendices: downloadable datasets, primary-interview excerpts, and scenario modelling tools to run bespoke what‑if analyses.
How to use the report in 2026 — a quick start agenda
-
Procurement teams: Use the price-deck scenarios and supplier scorecards to renegotiate long-term contracts and introduce performance-based indexing tied to certified low‑carbon blends.
-
Product and R&D: Prioritize certified beneficiation pathways that unlock premium positioning in sustainable construction specs and set up pilot programs with targeted offtakers.
-
Corporate development: Screen acquisition targets against the report’s M&A shortlist and run integration stress tests focused on logistics synergies and certification transferability.
-
Policy and government affairs: Deploy the policy-sensitivity analyses to shape constructive engagement with policymakers where utilization mandates and monitoring requirements are in flux.
PW Consulting’s Flyash Market study is purpose-built to be both strategic and operational: it equips boards with scenario-level insight while giving procurement, engineering, and M&A teams the calculators and playbooks they need to act. To preserve the competitive advantage for subscribers, the dossier intentionally omits minute public disclosure here — including granular region- and application-level splits and proprietary price curves — and instead houses those datasets, facility lists, and model templates within the full report package.
If your 2026 plan must reconcile decarbonization ambitions with margin preservation and secure access to industrial-grade inputs, treat flyash as a strategic portfolio item. The decisions you make this year — on sourcing architecture, beneficiation, long-term contracting, and selective M&A — will determine whether flyash is a constraint or a competitive differentiator for the next decade.
Access the full PW Consulting Flyash Market report to unlock the detailed segmentation tables, downloadable scenario models, supplier-level intelligence, and the action checklists you need to convert market signals into measurable advantage.
For detailed analysis of this topic, please visit the official page: Flyash Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com