

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CT Systems Market to Hit USD 344.8 Million by 2032 at 6.98% CAGR

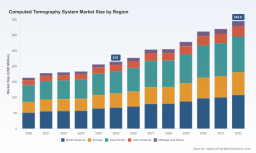
Computed Tomography System Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Consultant and Chief Industry Analyst, I present a focused preview of our Computed Tomography (CT) System Market study that will serve as a strategic primer for executive teams planning capital, product, and M&A decisions in 2026. This synopsis synthesizes the study’s most consequential, data‑driven signals — demonstrating our analytical depth — while intentionally withholding the full, granular segmentation tables and price schedules that clients access on the report landing page.
Computed Tomography System Market
Why this research matters for 2026
-
Macro trajectory clarity: The CT market exhibits a clear, multi‑year recovery and expansion. Our base year analysis (2025) captures a market that rose materially through the 2020–2025 period and enters 2026 on an upward growth path. Under the study’s forecast assumptions, the market expands at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 horizon, reaching materially higher levels by the end of the forecast window.
Computed Tomography System Market -
Decision timing: Hospitals, imaging service providers, and device OEMs face a near‑term inflection driven by new clinical protocols, reimbursement coding updates, and a wave of AI and photon‑counting introductions. The window to gain purchasing advantage and deployment lead times is narrow — 2026 is the year to convert strategy into action.
Computed Tomography System Market -
Practical, executable outputs: Our full report is oriented to move leaders from insight to execution with investment models, procurement playbooks, technology adoption curves, vendor scorecards, and regulatory pathway roadmaps.
High‑level market performance (concise, actionable)
PW Consulting’s topline assessment shows that the CT market grew steadily in the 2020–2025 historical window, reflecting technology refresh cycles, rising diagnostic demand, and incremental adoption of advanced imaging modalities. The study captures the market size at the 2025 base year and forecasts a continuation of growth into 2026 and beyond. Specifically, our forecasts show a material uplift in 2026 and sustained expansion through 2032, underpinned by a 6.98% CAGR for the forecast period.
These macro figures matter for three classes of decisions: capital expenditure timing for health systems, R&D and portfolio prioritization for OEMs, and value‑creation timing for financial sponsors. Because the expansion is broad‑based, organizations that align procurement windows and product roadmaps to the 2026–2028 inflection can capture outsized returns on both clinical outcomes and financial performance.
What the full report contains (practical depth)
-
Market sizing and scenario forecasts: Base‑year and historical tracking, plus low/most‑likely/high scenarios through 2032 that model capacity, reimbursement, and macroeconomic sensitivity.
-
Technology roadmap and clinical adoption curves: Detailed assessment of CT technological tiers (including photon‑counting and multi‑slice advances), AI integration patterns, and typical hospital upgrade cycles.
-
Buyer economics and TCO models: Total cost of ownership templates for new purchases, retrofit/upgrade economics, operating cost break‑evens, and utilization thresholds required to justify advanced modalities.
-
Competitive playbooks: Vendor scorecards that benchmark product capabilities, installed base strength, service footprint, and partnership ecosystems — designed to inform sourcing and alliance strategies.
-
Regulatory & reimbursement roadmaps: Step‑by‑step guides to navigate accreditation requirements, CPT/DRG coding updates, and payer engagement strategies to accelerate reimbursement for emergent CT technologies.
-
M&A and partnership scenarios: A prioritized list of capability gaps, target archetypes, and deal structures (JV, asset purchase, bundled services) most likely to create differentiated value in a consolidating market.
Market structure and concentration — implications
The competitive structure is characterized by a moderate concentration among the leading vendors. Our competitive concentration metrics indicate that the top three vendors account for a substantial portion of global revenue, and the top five command an even larger share. This creates a marketplace where incumbents set technical and commercial standards, but where nimble challengers can capture share by pairing local access, cost competitiveness, and targeted feature differentiation.
For buyers, this means two simultaneous imperatives: negotiate not only on price but on service level agreements, upgrade pathways, and AI/software roadmaps; and design procurement frameworks that allow technology substitution as new clinical evidence and reimbursement codes emerge.
Competitive landscape — current movers and patterns
-
GE HealthCare — Strengths: breadth of CT platforms, focus on cardiac and one‑beat imaging, and investments in AI workflow orchestration. Strategy implication: GE’s portfolio depth supports enterprise‑scale service contracts; counter‑strategies include modular upgrade pricing and outcome‑linked service bundles.
-
Siemens Healthineers AG — Strengths: premium single‑source systems, high‑speed scanning, and leadership in photon‑counting R&D. Strategy implication: Compete on integration and clinical differentiation; alternative vendors should emphasize cost of ownership and local service agility.
-
Koninklijke Philips N.V. — Strengths: spectral imaging, AI‑embedded workflows, and recent investments in sustainable global infrastructure. Strategy implication: Buyers will demand validated clinical workflows and interoperability assurances for spectral and AI features.
-
Canon Medical Systems — Strengths: strong CT engineering with AI enhancements and recent regulatory clearances broadening clinical applicability. Strategy implication: Canon’s regulatory momentum lowers adoption barriers for certain advanced features; procurement teams should seek demonstration projects to verify performance claims.
-
United Imaging Healthcare — Strengths: aggressive innovation cadence, AI‑based optimization, and platform mobility options with recent regulatory approvals that support US market expansion. Strategy implication: Their cost‑performance proposition will pressure incumbents on price and financing; strategic partners should evaluate interoperability and post‑sale support commitments.
-
Neusoft Medical Systems — Strengths: focus on affordable, accessible imaging for emerging markets. Strategy implication: Growth plays here are distribution‑led and price‑sensitive; OEMs targeting expansion should prioritize channel development and value‑packaging.
-
FUJIFILM Healthcare Solutions — Strengths: patient comfort and image quality with competitive mid‑tier offerings. Strategy implication: Differentiation via patient experience and workflow efficiency will be persuasive for ambulatory and outpatient imaging centers.
Recent developments that change strategy in 2026
-
Regulatory clearances: Several OEMs secured broadened clearances for AI‑enabled CT features and mobile/dual‑energy configurations over 2025–early 2026. These clearances shift the adoption calculus from experimental pilots to enterprise deployments.
-
Operational standards: Effective January 2026, new accreditation expectations require hospitals to adopt up‑to‑date CT imaging protocols. This will accelerate protocol harmonization and create demand for validated, vendor‑supported workflows.
-
Reimbursement signals: Industry guidance and payer interest in Category III CPT codes and DRG revisions for advanced CT technologies are advancing; hospitals are actively seeking CPT/DRG updates to monetize higher‑value imaging procedures.
-
Corporate footprint moves: Key vendors are investing in headquarters and facilities to strengthen R&D and sustainable operations — a signal that product roadmaps will be sufficiently funded to deliver new platform iterations.
Strategic implications and actionable recommendations for 2026
-
Prioritize technology roadmaps over single‑transaction buys. Require vendors to provide a five‑year upgrade and interoperability commitment tied to service credits.
-
Build an AI and photon‑counting readiness assessment into procurement: test datasets, clinical validation protocols, and workflow integration must be contractually defined.
-
Negotiate reimbursement support clauses. Given evolving CPT/DRG opportunities, include vendor cooperation on coding validation, outcomes data sharing, and payer engagement.
-
Consider blended financing and lifecycle procurement to match technology depreciation with clinical adoption curves — hybrid lease/purchase models will minimize stranded asset risk.
-
Adopt modular procurement pilots (clinical proof of concept, operational validation, then scale) to reduce deployment risk while capturing first‑mover advantages on advanced features.
-
Watch the competitive consolidation runway: with market concentration favoring top vendors but substantial share still available to challengers, targeted tuck‑ins and distribution partnerships remain high‑impact levers.
-
Stress‑test supply chain and service footprints. Vendor service network resilience will be a differentiator for multi‑site systems and time‑sensitive cardiac/oncology workflows.
What’s intentionally not in this preview (and why)
To preserve the investigative value and commercial integrity of our full market product, we have deliberately withheld granular regional and application splits, detailed unit pricing, and the full vendor scorecards you will find in the paid report. This summary is designed as a trailer — it demonstrates analytical rigor and strategic consequence, while directing teams to the full deliverable for procurement‑ready data tables, downloadable TCO models, and supplier comparison matrices.
Next steps
For executive teams preparing budgets, product leaders defining roadmaps, and corporate development groups sizing targets — our full Computed Tomography System Market report provides the executable intelligence to act in 2026. PW Consulting clients receive the complete dataset, step‑by‑step procurement playbooks, and facilitated workshops to translate findings into 90‑, 180‑, and 360‑day plans.
Contact PW Consulting to arrange a briefing and to obtain the full report, which includes the segmented market tables, vendor performance matrices, and customizable financial models required to operationalize the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Computed Tomography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com