

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Medical Micro Injection Molding Market Poised for 9.1% CAGR, USD 1,011M by 2025
By pmarketresearch, 2026-07-13
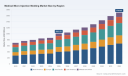
Medical Micro Injection Molding Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, action-oriented overview of our new Medical Micro Injection Molding Market study. This briefing explains why the study is a near-term strategic necessity for device OEMs, tier-1 suppliers, private equity investors, and manufacturing leaders planning capital and partnership moves in 2026. The goal here is to demonstrate our analytical depth while reserving the full segment-level detail for the complete report — a deliberate “trailer” approach to ensure you access the full intelligence package when shaping critical decisions.
Medical Micro Injection Molding Market
Market trajectory you must plan against
Medical micro injection molding has moved from niche capability to strategic manufacturing enabler across minimally invasive devices, drug delivery systems, diagnostics, and implantable components. Our market model (base year 2025, USD Million) shows the industry expanding from an observed market size in 2020 to a materially larger market in 2025, with a compound annual growth rate (CAGR) of 9.1% projected across our forecast window (2026–2032). Under our base forecast the market continues to scale through 2032 driven by device miniaturization, single-use adoption, and material innovation.
Medical Micro Injection Molding Market
Why this matters in dollars and decisions: the scale-up between the 2020 baseline and 2025 confirms an accelerating adoption curve; the 9.1% CAGR thereafter creates a multi-year runway where small differences in time-to-market, qualification speed, and supplier selection compound into material commercial advantage. Executives who lock in resilient supply chains, compliance-ready processes, and targeted technology investments in 2026 will be positioned to capture disproportionate share as the market grows.
Medical Micro Injection Molding Market
Near-term industry dynamics shaping 2026 strategy
- Regulatory tightening: The regulatory landscape has become more prescriptive for micro-manufactured medical components. The U.S. FDA’s Quality Management System Regulation (QMSR), aligned with ISO 13485 and effective in early 2026, raises expectations on cleanroom environments, process reproducibility, and documentation. Meanwhile, EU Medical Device Regulation (MDR) enforcement continues to elevate clinical-evidence and traceability requirements. These changes turn regulatory readiness into a non-negotiable operational capability for suppliers and OEMs alike.
- Clinical adoption and clearance activity: An uptick in device clearances that incorporate micro injection molded parts (notably in interventional cardiology and point-of-care diagnostics) has accelerated market adoption. Increased 510(k) activity in recent years signals both technology validation and a pipeline of near-term volume growth for qualified suppliers.
- Material and process portfolio evolution: Material choices are a strategic axis: traditional thermoplastics remain a cornerstone for disposables and sterilizable components; liquid silicone rubber (LSR) and bioabsorbables are gaining ground where elastomeric properties or resorption characteristics are required. Process innovation around micro-tolerancing, insert molding, overmolding, and optical micro-molding is reducing assembly counts and enabling product form-factor improvements.
- Market structure: The competitive landscape remains fragmented: leading specialists exist, but the top handful of suppliers do not dominate the market. This fragmentation creates opportunities for OEMs to implement multi-vendor strategies and for investors to pursue consolidation plays that generate scale advantages in regulatory compliance, cleanroom investment, and technical know-how.
What the PW Consulting report delivers — practical, executable intelligence
We designed the study to be directly actionable for 2026 decision cycles. Key deliverables include:
- Replicable market-sizing model (base year 2025, forecast to 2032) with scenario toggles for adoption rates, regulatory friction, and capital investment pace.
- Technology deep dives comparing molding approaches, inspection & metrology options, and cost-to-quality trade-offs at micron tolerances.
- Regulatory impact matrix and an operational checklist aligned to the FDA QMSR and EU MDR for supplier qualification and audit readiness.
- Procurement playbook: supplier scorecards, RFP templates, qualification timelines, and TCO models tailored to small-form factor components.
- Supply chain risk heatmap and mitigation playbooks (nearshoring, dual-source qualification, contingency inventory sizing, and CAPEX vs. outsourcing decision frameworks).
- M&A and partnership screening criteria that quantify integration synergies from regulatory compliance, cleanroom capacity, and vertical capabilities (e.g., LSR or bioabsorbables).
- Commercial negotiation levers and contract structures that preserve quality controls while enabling volume step-ups and price protection.
Competitive landscape—who does what, and strategic implications
The report profiles global suppliers and maps capability clusters so you can align sourcing strategy with product roadmaps. Representative insights include:
- Accumold / Accu-Mold: U.S.-based specialists focused on micron-level tolerances for implantables and precision components. Recent trade-show visibility and technical publications indicate aggressive marketing of advanced micro-optics and precision molding solutions.
- West Pharmaceutical Services: Deep expertise in drug delivery components with rigorous regulatory infrastructure—an attractive partner where combination of molding precision and regulatory traceability is essential.
- Phillips-Medisize: Strong in complex, integrated device assemblies where molding is one element of a broader device manufacturing proposition; their capabilities suit OEMs seeking single-stop providers for complex contract manufacturing.
- European specialists (e.g., Nolato, Röchling, Micro Systems Technologies): Offer regional proximity to EU OEMs and are proven in diagnostic and single-use device segments; their value proposition frequently centers on regulatory familiarity and supply continuity within Europe.
- U.S.-based precision houses (e.g., Sovrin Medical Plastics, Tessy Plastics, Spectrum): Compete on medical-grade processes, FDA/ISO alignment, and short lead-times for prototyping to low-volume production.
- Asia/Japan providers (e.g., SMC Ltd.): Provide scale and cost competitiveness for higher-volume, lower-complexity components, with growing investment in medical-grade capabilities.
Strategic reading: suppliers differentiate along three axes — technical tolerance & material expertise, regulatory and quality systems maturity, and contractual flexibility. Your 2026 sourcing choices should be tailored to which axis most impacts your device’s time-to-market and clinical pathway.
Actionable playbook for 2026 — five priority moves
- Immediate: Audit regulatory readiness against QMSR. If your supplier network lacks harmonized QMS documentation and cleanroom capability records, start qualification or remediation now. Regulatory audits are the pacing factor for device launches.
- Short-term: Dual-source critical components. For high-risk, single-sourced micro components, implement parallel qualification tracks to reduce single-point failure risk and preserve launch timelines.
- Mid-term: Material strategy and DfM investment. Reassess parts for consolidation through overmolding or design simplification. Prioritize materials that balance sterilization compatibility, biocompatibility, and manufacturability to avoid late-stage rework.
- Capex decision framework: Conduct make-vs-buy analysis using our TCO model — evaluate investments in micro-molding capacity only when utilization thresholds, regulatory burden savings, and IP protection justify the capital outlay.
- M&A/partnership scouting: Use the report’s screening criteria to identify targets that immediately add regulatory-ready capacity, proprietary tooling expertise, or material-specific competence (e.g., LSR or bioabsorbables).
Recent supplier signals you should watch
Supplier trade-show participation and technical publications are actionable market signals. For example, one leading precision supplier increased trade-show outreach in 2025 and published technical guidance on micro-optic molding in early 2026 — signaling both capability maturity and intent to capture higher-value device work. These public signals are useful leading indicators when selecting partners or screening acquisition targets.
Why our study is critical for 2026 decision cycles
Because the market is growing at a near-double-digit CAGR, the distance between moving early versus reacting late is not just incremental — it defines relative market share and margin outcomes for the next product generation. Our study provides the combination of quantitative market projection, regulatory impact assessment, supplier capability mapping, and executable procurement and M&A playbooks necessary for high-confidence decisions in 2026.
We intentionally withhold segment-level breakdowns and supplier revenue detail in this briefing to preserve the full strategic value of the report package. The complete study contains granular segment analyses, region-by-application scenarios, supplier benchmarking matrices, and downloadable financial models that translate the market projections into concrete revenue and cost implications for your specific product portfolio.
Next steps
- Request the full report and model to run your customized scenario (capacity investments, supplier consolidation, or M&A targeting).
- Schedule a strategy session with PW Consulting to apply the procurement playbook to your 2026 sourcing calendar and to prioritize pilot programs for capability upgrades.
Contact PW Consulting to access the full Medical Micro Injection Molding Market report and the underlying forecast model. In an environment of regulatory tightening and accelerating technical requirements, the right intelligence in 2026 will determine who captures growth and who merely participates.
For detailed analysis of this topic, please visit the official page: Medical Micro Injection Molding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Active Air Sampler Market to Hit USD 594.5M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-13
Active Air Sampler Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
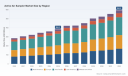
PW Consulting’s new Active Air Sampler Market study delivers a pragmatic intelligence package aimed squarely at the decisions you will make in 2026. The market for active air samplers has shown steady expansion through the recent historical window (2020–2025), rising from approximately USD 285 Million in 2020 to USD 384.3 Million in the base year 2025. Our baseline forecast (2026–2032) projects continued growth to roughly USD 594.5 Million by 2032, implying a compound annual growth rate (CAGR) of 6.5% across the forecast period.
Active Air Sampler Market
Those topline figures capture both structural tailwinds (regulatory tightening, biopharma manufacturing scale‑up, and renewed focus on food/health safety) and the tactical responses of vendors (product, service and digital integration). This preview highlights why these dynamics matter for procurement, R&D, M&A, and service strategy in 2026 — while deliberately preserving detailed subsegment data and granular regional splits to encourage access to the full study.
Active Air Sampler Market
Why this study matters for decisions made in 2026
- Regulatory inflection is real and immediate. Updates to cleanroom and aseptic processing guidance have elevated the commercial importance of validated, continuous viable monitoring and documented data integrity. Compliance timelines and validation build windows mean procurement cycles initiated in 2026 will determine equipment and service footprints for several years.
- Technology convergence reshapes value chains. The integration of active samplers with remote sampling, real‑time particle counters and digital logging platforms is changing purchase criteria from pure instrument cost to integrated solution economics.
- Service & calibration becomes a competitive moat. As buyers prioritize chain‑of‑custody, calibration integrity and 21 CFR/ISO aligned documentation, vendors with robust service networks and accredited calibration offerings capture higher lifetime value.
- Fragmentation creates both risk and opportunity. Market concentration metrics show the industry remains fragmented (CR3 ~19.8% and CR5 ~24.5%), signaling acquisition opportunities for strategic consolidators and whitespace for focused specialists.
- M&A and partnerships will accelerate. Strategic investments and technology partnerships are already visible; the next 12–24 months will separate nimble integrators from single‑product incumbents.
What the full report delivers — practical contents for immediate action
- Market sizing and validated forecasting (base year 2025, historical 2020–2025, forecast 2026–2032) with scenario and sensitivity testing to stress‑test capex plans.
- Segmentation frameworks by region, product type and application, with decision‑grade worksheets for prioritizing addressable revenue pools (note: granular split tables and proprietary subsegment figures are available only in the full report).
- Competitive landscaping and vendor scorecards assessing product portfolio breadth, regulatory fit, digital maturity, service footprint, and channel strategy.
- Regulatory mapping — line‑by‑line implications of EU GMP Annex 1 and ISO 14698‑1 for procurement specifications, validation requirements, sampling protocols, and audit readiness.
- Technology deep dives covering impactor technologies, cyclonic samplers, membrane and gelatin filtration approaches, remote sampling platforms, and real‑time microbial detection integrations.
- Go‑to‑market playbooks and procurement templates: validated RFP language, acceptance test scripts, ROI and TCO calculators, and sample service level agreements.
- Strategic recommendation engine for M&A targeting, partnership screening, and product roadmap prioritization — including a short list of capability gaps buyers and vendors should address immediately.
Competitive landscape — tactical takeaways for vendors and buyers
The vendor universe is populated by specialist instrument makers and larger life‑science players. Several archetypes are visible: engineering‑first innovators focusing on sampling technology (impactors, cyclonic samplers, membrane solutions), platform integrators pursuing digital/data integrity advantages, and service‑centric players anchoring sales through accredited calibration and support networks.
Active Air Sampler Market
- Product innovators: Companies producing cyclonic samplers and multi‑head impactors are advancing sampling efficiency and usability. These firms compete on throughput, capture efficiency and ergonomic design.
- Platform integrators: Vendors offering remote/automated sampling capable of integration with particle counters and LIMS are capturing incremental value as buyers prioritize continuous monitoring and audit trails.
- Compliance & service specialists: Firms that combine instrument sales with ISO/17025‑grade calibration, 21 CFR Part 11–aligned data management and field validation become preferred partners for large regulated customers.
Representative vendors in the market exemplify these archetypes. For example, certain U.S. and European manufacturers offer remote Annex 1‑compliant samplers designed for aseptic Grade A/B environments, while other European and Asian manufacturers focus on portable impactor devices and membrane filter solutions for traditional viable monitoring. Notable moves in the recent timeline reinforce strategic direction: a Swiss vendor launched a next‑generation active microbial air sampler in May 2026 emphasizing improved usability for cleanroom monitoring, a major French life‑science company invested in a real‑time air microbial particle counter integrator in March 2026, and a U.S. supplier received ISO 17025 accreditation for calibration services in late 2025. These events demonstrate the market’s twin emphasis on product refinement and service/accreditation as competitive levers.
Regulatory and technical dynamics shaping procurement
- EU GMP Annex 1 & ISO 14698‑1: Both documents are driving purchases toward systems that facilitate validated continuous viable monitoring, traceable sample handling and documented method performance. Buyers must embed Annex 1 and ISO requirements into technical specifications and acceptance testing.
- Data integrity and remote monitoring: Requirements such as 21 CFR Part 11 compliance and secure electronic records are elevating expectations for onboard software, audit logs, and integration capabilities.
- Validation first, features second: For regulated customers, validated performance (recovery efficiency, repeatability under cleanroom conditions) often trumps minor feature differentials; vendors must prioritize validation packages and ready‑to‑deploy protocols.
Four‑point strategic playbook for 2026
- For vendors — product & validation roadmap: Prioritize modular designs that support both portable and remote deployment, publish independent validation data aligned to ISO 14698‑1, and bundle documented Annex 1 compliance aids to reduce buyer friction.
- For service leaders — accreditation & network expansion: Invest in ISO 17025 capabilities, scale field calibration teams in key manufacturing clusters, and offer subscription‑based calibration and validation services to convert transactional sales into recurring revenue.
- For strategic buyers — procurement discipline: Convert regulatory requirements into mandatory RFP pass/fail criteria (validation artifacts, software audit trails, service SLAs). Evaluate total cost of ownership including calibration cadence, consumables, and validation labor — not just capital price.
- For consolidators — targeted M&A & partnerships: Seek targets that add either accredited calibration infrastructure or digital sampling/real‑time detection capabilities. Partnerships with specialist integrators can accelerate time‑to‑market for combined hardware/software propositions.
Why PW Consulting’s report is uniquely actionable
We combine rigorous top‑down market sizing (base year 2025; historical 2020–2025; forecast 2026–2032) with bottom‑up device, consumables and services economics to produce decision‑grade outputs. Our vendor scorecards synthesize product validation, regulatory fit, service footprint and digital maturity into a single advisory framework that procurement, product and corporate development teams can operationalize. The report also contains editable procurement templates, validation checklists, and M&A screening matrices that accelerate execution timelines for 2026 initiatives.
How to use this preview — next steps
This briefing is intended as a strategic “trailer”: it exposes the trends, vendor archetypes and regulatory drivers that will shape budgets, roadmaps and M&A moves in 2026, while intentionally withholding proprietary subsegment tables and granular regional/application splits. If you are preparing procurement cycles, launching product development initiatives, or evaluating acquisition targets this year, the full PW Consulting report provides the detailed split‑level intelligence, vendor benchmarking matrices and customizable templates that translate insight into action.
Contact PW Consulting to access the complete study and receive a tailored briefing that maps the findings directly to your organization’s product, procurement and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Active Air Sampler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Medicine Market to hit USD 24.03B by 2032 — 7.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Pet Medicine Market — Strategic Outlook and Decision Framework for 2026
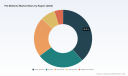
As pet ownership continues to rise and owners increasingly treat companion animals as family members, the pet medicine market is transitioning from a niche veterinary sector into a strategic growth arena for pharmaceutical and animal-health players. Our PW Consulting Pet Medicine Market study crystallizes this opportunity: the global market expanded from USD 9.5 Billion in 2020 to USD 14.8 Billion in 2025 and—driven by therapeutic innovation, channel evolution, and higher per-animal spend—is projected to grow at a compound annual growth rate (CAGR) of 7.2% to reach roughly USD 24.0 Billion by 2032. This briefing outlines why these dynamics matter for 2026 corporate decision-making and how leaders should prioritise actions without revealing the fine-grained segmentation that is reserved for the full report.
Pet Medicine Market
Why this study matters for 2026 strategic choices
- Board-level clarity: Quantifies market scale and medium-term trajectory to justify resource allocation across R&D, commercial expansion, and M&A.
- Portfolio prioritisation: Signals where to allocate development budgets between small molecules, biologics, vaccines and supplements given changing clinical and commercial return profiles.
- Go-to-market alignment: Maps the shifting balance across clinics, retail and digital channels so commercial models can be adapted to where veterinarians and owners actually transact.
- Risk-adjusted planning: Translates regulatory and supply-chain noise into actionable mitigation paths tied to probability-weighted scenarios.
Macro and clinical trends shaping 2026 strategy
The market’s steady mid-single-digit CAGR masks two important accelerants. First, therapeutic innovation—particularly targeted therapies and next-generation small molecules—has increased addressable spend per patient. Recent regulatory milestones, including the FDA’s approval pathways for novel modalities and the first oral oncology treatment for canine lymphoma, are expanding treatment options and opening higher-value clinical niches. Second, distribution and purchasing behavior are fragmenting: while veterinary clinics remain central to diagnosis and prescribing, retail and digital channels are growing rapidly, prompting new commercial models.
Pet Medicine Market
At the same time, regulators are more active and visible. The FDA Center for Veterinary Medicine’s enforcement actions and approvals are reshaping product claims, labelling strategies and promotional conduct for 2026 launches. Notable regulatory events—such as an FDA warning to a major competitor over promotional claims and subsequent approvals of new drug classes—underline the need for an integrated regulatory-commercial playbook.
Pet Medicine Market
Competitive landscape — what to watch in 2026
The competitive set is composed of a mix of global pharma incumbents and specialized animal-health companies with differentiated R&D and channel capabilities. Key firms profiled in the study include:
- Merck Animal Health (Rahway, NJ) — A leader in companion-animal therapeutics with a strong late-stage pipeline and recent product approvals for conditions such as allergic dermatitis; their regulatory momentum and broad commercial field force make them a formidable competitor for specialty franchises. ( https://www.merck-animal-health.com)
- Zoetis (Parsippany, NJ) — Deep expertise in biologics and chronic-care products for pets; strong global distribution and data-driven animal health capabilities position them well in higher-value therapeutic categories. ( https://www.zoetis.com)
- Elanco Animal Health (Indianapolis, IN) — Focused on specialty pet medicines with recent launches in pruritus indications; regulatory scrutiny over promotional practices highlights reputational and compliance risks. ( https://www.elanco.com)
- Boehringer Ingelheim (Duluth, GA) — Robust R&D in chronic and parasitic conditions, with strengths in integrated animal-health services and product portfolios. ( https://www.boehringer-ingelheim.com)
- Bayer Animal Health (Leverkusen, Germany) — Strong in preventive care and parasitic controls, with notable consumer-facing brand recognition and retail partnerships. ( https://www.bayer.com)
- Vetoquinol (Magny-Vernois, France) — Specialist producer with agility in mid-market therapeutic categories and strong ties to veterinary practitioners. ( https://www.vetoquinol.com)
Competitive implications for 2026: incumbents with deep field sales and strong regulatory teams will defend core chronic-care segments, while agile specialty players and biotech partnerships will target high-growth niches created by novel modalities. The sector’s concentration—where the top three and top five players command a material share of the market—creates both defensive moat benefits and pockets of opportunity for focused innovators.
Regulatory and supply-chain dynamics to prioritise
- Regulatory enforcement and approvals: Elevated regulator activity means product claims, clinical endpoints and post-market surveillance must be aligned early in development to avoid launch delays or reputational damage.
- API and input risk: Proposed tariffs and concentration in API sourcing can materially increase costs and create bottlenecks; dual-sourcing and regional manufacturing flexibility should be modelled as part of capital planning.
- Commercial compliance: Warning letters and promotional scrutiny underline the need for compliant digital marketing, veterinarian engagement protocols, and field-sales training.
- Reimbursement and out-of-pocket dynamics: The largely out-of-pocket nature of companion-animal medicine requires robust owner-value messaging; consider pilot pricing models tied to demonstrated outcomes.
Practical strategic playbook for 2026
Translate insights into near-term actions. The following playbook is oriented to executives preparing 2026 budgets and three-year plans:
- Re-balance R&D portfolios toward high-value modalities: Prioritise projects with clear differentiation (e.g., targeted cytokine inhibitors, monoclonal antibodies) and acceptable regulatory pathways.
- Invest in regulatory capability: Hire or partner for veterinary-specific regulatory expertise to shorten approval timelines and reduce enforcement risk.
- De-risk supply chains: Implement dual-sourcing for critical APIs and consider regional fill/finish capacity to avoid tariff and transport disruptions.
- Adapt commercial models to omnichannel: Strengthen clinic relationships for prescribing while building scalable digital retail funnels and subscription services for chronic care.
- Pursue tuck-in M&A and strategic alliances: Target capabilities (digital prescribing platforms, diagnostics, biologics manufacture) that accelerate route-to-market and margin expansion.
- Build real-world evidence (RWE) programs: Capture outcome and safety data via clinic networks to support premium pricing and payer conversations where applicable.
- Design compliance-first marketing: Update promotional materials and training to reflect recent regulatory actions and guardrails.
- Scenario test your business plan: Run upside/downside cases around regulatory delays, API cost inflation and channel displacement to set contingency budgets.
What the full PW Consulting report contains (teaser)
The published study is designed for executive teams and investment committees. Highlights include:
- A detailed market model (historical 2020–2025 and forecast 2026–2032) with transparent assumptions and sensitivity testing.
- Segment-level analysis across product types, animal types, distribution channels and regions, plus growth drivers—note that full segmentation tables and company share data are available in the paid report.
- Comprehensive company profiles and capability-mapping for leading and challenger firms, including commercial footprints and pipeline positioning.
- Regulatory timeline and impact analysis covering recent FDA actions, approvals and likely near-term guidance that will affect launch strategies.
- Supply-chain vulnerability assessment and mitigation playbook with cost-to-implement estimates.
- Actionable go-to-market playbooks tailored to large incumbents, mid-sized players and new entrants—with recommended investment horizons and ROI thresholds.
- Financial impact analyses and M&A screens identifying asset types and geographies likely to produce immediate synergies.
- An executive-ready slide pack and an editable Excel model for in-house scenario planning.
How to use these insights in your 2026 decision cycle
For CEOs and CFOs: use the market trajectory and scenario outputs to set R&D run-rate, capital allocation and M&A priorities. For Heads of R&D and Regulatory: recalibrate development roadmaps to prioritise modalities with clearer veterinary pathways and fund early regulatory engagement. For Commercial leaders: craft omnichannel models that preserve veterinarian engagement while monetising convenience-driven retail and digital channels. And for Strategy and Corporate Development teams: screen potential targets using the study’s deal filters and valuation templates to accelerate due diligence.
Our approach follows the “preview” principle: this note surfaces the strategic contours and the most consequential actions for 2026, while the full PW Consulting Pet Medicine Market report contains the granular segmentation, company share tables and model files needed to execute with confidence. For teams preparing budgets, pipelines or M&A pipelines in 2026, the report converts market trajectory into executable program roadmaps and quantifies the trade-offs inherent in each strategic choice.
To access the full dataset, scenario models, and company-level analysis that support the recommendations above, please consult the source publication. PW Consulting stands ready to run tailored workshops to translate these findings into your 2026 operating plan.
For detailed analysis of this topic, please visit the official page: Pet Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Depaneling Market Poised for 8.1% CAGR Through 2032
By pmarketresearch, 2026-07-13
Laser Depaneling Machine Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest industry insight frames laser depaneling as a maturing, consolidation-prone equipment market that is increasingly central to high-mix, high-reliability electronics manufacturing. This preview highlights the strategic value of the full study for executives planning CapEx, supply-chain repositioning, or product-line transitions in 2026. It demonstrates the depth of our analysis while intentionally withholding granular segment tables and proprietary model outputs — the full intelligence package is available in the complete report.
Laser Depaneling Machine Market
Market at a Glance — Macro Trajectory
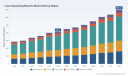
Between 2020 and 2025, the laser depaneling machine market expanded from roughly USD 287 million to approximately USD 413 million, driven by growing requirements for low-stress singulation across consumer, automotive, medical and aerospace electronics. Our forward-looking base-year is 2025 and we model an 8.1% compound annual growth rate for the 2026–2032 forecast window. Under base-case assumptions the market reaches nearly USD 700 million by 2032, with non-linear acceleration tied to high-volume automotive electrification programs and continued substitution away from mechanical routing in selected geographies.
Laser Depaneling Machine Market
Why This Research Matters for 2026 Strategy
- CapEx prioritization with precision: Buyers and OEMs can no longer treat depaneling as a commodity. The report aligns technology roadmaps with production volumes, scrap-reduction targets, and line-balancing metrics to produce actionable CapEx triggers for 2026 procurement cycles.
- Supplier selection under consolidation: The market shows meaningful concentration among a small set of global vendors. The full analysis provides a defensible procurement playbook — from preferred supplier lists to contract length and upgrade-path negotiation levers — enabling procurement teams to capture better TCO outcomes in supplier-dominant markets.
- Risk-aware automation decisions: Integrating laser depaneling into Industry 4.0 stacks reduces labor dependency while raising requirements for MES/ERP interoperability and predictive maintenance. Our scenarios quantify exposure to labor constraints and energy volatility, turning abstract operational risks into prioritized mitigation actions.
What the Full Report Contains — Practical Outputs
Clients will find the report deliberately operational. Highlights include:
Laser Depaneling Machine Market
- Top-down market sizing and a transparent reconciliation of historical shipments and installed base dynamics (2020–2025), plus a seven-year forecast with three scenario bands.
- Technology adoption roadmaps and maturity curves for UV, fiber, CO2 and hybrid approaches — assessing fit by board substrate, thermal sensitivity and line throughput targets (note: detailed share tables are withheld in this preview).
- Vendor scorecards and heatmaps across performance, automation, software, service footprint and upgradeability — practical benchmarks for RFPs and supplier development programs.
- CapEx decision frameworks that translate production KPIs (yield, takt time, changeover time) into payback periods and IRR ranges. Included are modular financial models for quick sensitivity analysis by plant, product family, and region.
- Supply-chain maps and procurement playbooks covering laser modules, optics, motion systems and vision subsystems, plus critical single-source risk flags and recommended dual-sourcing architectures.
- Regulatory and compliance implications for high-reliability markets (automotive, aerospace, medical) including quality traceability and edge integrity requirements — with implementation checklists for quality engineers.
- Implementation blueprints for automation and MES integration, including data models, SMEMA and pick-and-place interface examples, and best-practice P-FMEA items tailored to depaneling processes.
Each chapter includes prescriptive appendices (sample RFP language, test protocols, and acceptance criteria) to accelerate internal alignment between engineering, procurement, and operations teams.
Market Dynamics — Drivers and Headwinds
The market’s growth is shaped by a cluster of technology and supply-side forces:
- Technology substitution: Laser depaneling is displacing mechanical routing in many high-volume and high-mix lines because it reduces mechanical stress, lowers scrap, and supports ultra-thin and flexible substrates. This substitution is uneven by product family and geography; our report provides the decision-tree to quantify replacement economics at the product-line level.
- Automation and labor economics: Integration with MES and higher degrees of automation respond directly to labor shortages and the premium on consistent line yields. The research models labor-availability sensitivity and identifies the operational ROI thresholds at which automation investments become irreversible.
- Edge-quality and regulatory tightening: Higher-spec applications in automotive and aerospace have driven the integration of AI-assisted kerf monitoring and adaptive power modulation on recent UV platforms. These capabilities materially alter warranty exposure and product reliability economics for OEMs.
- Energy and sustainability: New system architectures that reduce carbonization and particulate generation (and thereby secondary cleaning) are delivering both energy and environmental benefits — an increasingly important procurement criterion for Tier‑1 OEMs and EMS providers.
- Consolidation and supplier power: A concentrated vendor landscape raises the importance of contractual design and lifecycle service agreements. The full report includes negotiation playbooks and a vendor-risk heatmap to protect margin and service continuity.
Competitive Landscape — Who Matters and Why
The competitive field includes established laser specialists, automation integrators, and regional OEMs. Key players we profile in depth include LPKF Laser & Electronics, ASYS Group, Genitec, Han’s Laser, IPTE, Seika Machinery, Aurotek, CMS Laser, and Photonics Systems Group. Our vendor analysis focuses on the following dimensions:
- Technology differentiation: UV platforms with CleanCut or equivalent low-HAZ technologies, and fiber systems optimized for copper- and power‑electronics-heavy boards, represent distinct value propositions. We map application-fit against these capabilities to help OEMs choose the right architecture for a given PCB family.
- Automation and software: Vendors that bundle robust vision systems, fiducial alignment, and software connectivity win in high-mix SMT lines. We profile software stack maturity and upgrade pathways for each major supplier.
- Service and aftermarket: Given the installed-base economics, spares and regional service presence are often decisive. The report grades each supplier on response times, spare-parts logistics, and retrofit options.
- Recent strategic moves: We track product launches and live demonstrations that signal technology and commercial intent — for example, the introduction of AI-assisted quality monitoring on new UV platforms and multiple live showcases at major trade events in 2026. These events are early indicators of feature adoption curves and roadmap acceleration.
How to Use This Research in 2026 Planning Cycles
- Procurement teams: Use the vendor scorecards and TCO models to create a pre‑qualified supplier roster for 2026 RFQs, and to determine optimal warranty and service-contract lengths.
- Operations and engineering: Run the included CapEx calculators against representative SKUs to determine which product families should be migrated to laser depaneling in the next 12–36 months.
- Corporate strategy and M&A: The market’s concentration and the presence of technology adjacencies create acquirable assets — from vision software to specialized motion control — that can accelerate capability buildups. The report includes acquisition candidate criteria and valuation heuristics tailored to strategic buyers.
- R&D and product management: Leverage the technology roadmaps and kerf‑quality standards to prioritize feature development and interoperability with customers’ MES ecosystems.
Methodology, Transparency and Limitations
Our approach triangulates proprietary shipment data, vendor disclosures, public financials, trade-show telemetry and OEM interviews. The report documents assumptions, growth drivers and sensitivity ranges so clients can validate and update models with their internal data. In keeping with the “trailer” principle, detailed subsegment tables and regional/application share matrices are excluded from this preview — those datasets form part of the licensed package and are essential for site‑ or product‑level decisioning.
Next Steps — Accessing the Complete Intelligence
For executives who need to convert the macro picture into executable plans in 2026 — including supplier negotiation scripts, plant-level TCO models, and migration maps for product portfolios — PW Consulting’s full Laser Depaneling Machine Market report supplies the data and tools required. The full deliverable includes editable financial models, RFP templates, and a bespoke advisory session to translate findings into a 12–24 month implementation roadmap.
Contact details and the purchase pathway are available on the report landing page. The preview presented here is designed to clarify the report’s strategic value and scope; the granular segmentation matrices, supplier scorecards and regression models are available only with the complete study.
For detailed analysis of this topic, please visit the official page: Laser Depaneling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Veterinary Drug Market to Reach USD 46.57B by 2032 at 6.2% CAGR
By pmarketresearch, 2026-07-13
Veterinary Drug Market 2026: Strategic Imperatives for Executive Decisions
As Pw Consulting’s lead industry analysis for the Veterinary Drug Market, this briefing frames the strategic value of our full 2026 market study and highlights the evidence-based actions executives must consider during the next planning cycle. The market has moved decisively from a mid‑teens billion base earlier this decade to a robust multi‑decade growth trajectory: total global veterinary drug revenues rose materially between 2020 and 2025, and our baseline forecasts (2026–2032) project a compound annual growth rate (CAGR) of approximately 6.2%, with the market expanding substantially through 2032. These macro dynamics create both expansion opportunities and execution risks for incumbent manufacturers, specialty entrants, contract manufacturers, and investors.
Veterinary Drug Market
Why this research matters for 2026 decisions
-
Investment prioritization: the report quantifies where growth is concentrated and which therapeutic classes and modalities are accelerating fastest, enabling disciplined capital allocation across R&D, M&A, and commercial rollouts.
Veterinary Drug Market -
Portfolio strategy: it maps product lifecycles against market demand and regulatory windows so you can decide where to double down on next‑generation biologics versus where to pursue lower‑margin generic plays.
Veterinary Drug Market -
Commercial design: the study provides go‑to‑market segmentation frameworks and pricing sensitivity analyses tailored to companion animal and livestock channels to optimize launch sequencing and channel economics.
-
Regulatory and supply‑chain resilience: with recent shifts in conditional approvals, EUA decisions, and biologics licensing requirements, the study gives scenario playbooks for regulatory engagement and contingency planning for production constraints.
-
M&A and partnership screening: a prioritized target list and valuation sensitivity model help deal teams size potential bolt‑on acquisitions and strategic alliances in a market where the top players remain concentrated but new entrants are rapidly introducing differentiated assets.
Market context and growth drivers
The market’s recent expansion reflects a convergence of secular trends. Rising pet ownership, the premiumization of companion animal healthcare, and increasing willingness among pet owners to fund advanced diagnostics and therapies are powerful demand multipliers for pharmaceuticals and biologics. At the same time, intensifying focus on herd health, productivity, and antimicrobial stewardship on the livestock side is supporting higher uptake of targeted therapeutics and growth‑promoting interventions where permitted by regulation.
Technological shifts—particularly the adoption of biologics, long‑acting formulations, and novel delivery systems—are reshaping product economics and channel structures. Parallel pressures on the cost base—driven by elevated pharmaceutical input prices and supply chain constraints reported by industry associations—are forcing companies to rethink sourcing, contract manufacturing, and inventory strategies.
Regulatory and policy dynamics
-
Conditional and accelerated approvals: regulators are increasingly using conditional approvals to speed innovative veterinary drugs to market while still managing safety data requirements—creating both upside for early movers and complexity for post‑market evidence commitments.
-
Biologics licensing and manufacturing standards: veterinary biologics remain subject to robust licensure pathways and manufacturing controls. Licensed production sites and compliance with national acts governing biologics are non‑negotiable for market access and product integrity.
-
Emergency authorizations and single‑use interventions: regulators have demonstrated flexibility in crises, issuing emergency use authorizations for targeted animal health threats. These measures change the risk/reward calculus for companies with contingency products or adaptable manufacturing capacity.
Competitive landscape — concentration and strategic positioning
The veterinary drug industry exhibits moderate to high concentration at the top: the leading three companies account for a meaningful majority of market share, and the top five constitute an even larger portion of revenue—a structure that rewards scale, distribution reach, and R&D depth. Against this backdrop, there is room for specialists and generics providers to pursue niche scale or cost leadership strategies.
-
Zoetis Inc. — With deep expertise across pharmaceuticals, vaccines, and diagnostics, Zoetis continues to leverage scale and a broad portfolio. Recent approvals extending growth implants and other production‑animal products reinforce its capacity to combine regulatory experience with commercial force. For competitors, Zoetis’ playbook highlights the value of integrated product and service offerings that lock in veterinarian and producer loyalty.
-
Boehringer Ingelheim Animal Health — Known for innovation across vaccines and pharmaceuticals, the company’s strategy centers on integrated smart solutions and farm‑level digital links. Their model underscores the competitive advantage of tying therapeutics to preventive and monitoring services.
-
Elanco, Merck, Ceva, and other global players — These firms balance broad therapeutic coverage with targeted investments in biologics and parasiticides. Their global networks and manufacturing footprints act as barriers to rapid scale‑up by regional players, but they also reveal acquisition and divestiture opportunities for nimble challengers.
-
Specialists and generics (e.g., Phibro, Dechra, Vetoquinol, Bimeda, Huvepharma) — These players compete on cost, speed to market for generics, and focused therapeutic expertise. Their success often depends on regulatory agility and relationships with distributors and veterinarians.
Recent regulatory approvals in early 2026—covering pain management products, extended‑release implants for beef cattle, and novel medicated feed formulas—illustrate how product introductions continue to shift competitive dynamics in both companion and production animal segments. These approvals also heighten the tactical importance of launch sequencing, post‑approval evidence plans, and supply chain readiness.
What’s in the full Pw Consulting Veterinary Drug Market report
-
Executive summary with scenario‑based market sizing and a concise implications matrix for C‑suite decision making.
-
Methodology appendix describing our base year (2025) calibration, historical series (2020–2025), and the assumptions underlying the 2026–2032 forecast path.
-
Therapeutic and modality analysis that ranks classes by growth rate, margin profile, regulatory complexity, and commercial barriers—presented as decision tools rather than raw tables.
-
Competitive benchmarking dossier profiling product portfolios, pipeline assets, manufacturing capacity, and go‑to‑market strengths for the leading firms.
-
Regulatory roadmap and compliance checklist for biologics and small‑molecule approvals, including conditional approval pathways and EUA contingency playbooks.
-
Commercial playbooks with channel economics, pricing models, veterinarian segmentation, and digital engagement strategies for companion and livestock channels.
-
Supply‑chain stress tests, supplier concentration assessments, and manufacturing expansion decision frameworks.
-
M&A screening templates, valuation sensitivity models, and a prioritized shortlist of target archetypes (technology, geographic extension, generics/commercial or manufacturing scale).
-
Appendices with slide‑ready charts, a downloadable financial model, and an evidence library of regulatory notices, approvals, and data sources used to build the forecast.
How executives should use the findings in 2026
-
Adopt a two‑track R&D funding approach: protect core revenue through life‑cycle management while allocating a defined portion of incremental R&D to high‑growth biologics and differentiated delivery systems.
-
Prioritize manufacturing investments where margin uplift and regulatory complexity overlap—especially for biologics—while outsourcing commoditized production to cost‑competitive CMOs with veterinary expertise.
-
Prepare regulatory evidence plans concurrently with development programs to shorten time‑to‑value in conditional approval regimes and to manage post‑market obligations.
-
Use the competitive concentration data to shape M&A strategy: acquire capabilities that close strategic gaps (e.g., digital services, biologics, or specific species expertise) rather than pursuing broad scale alone.
-
Institute a commercial segmentation playbook that differentiates tactics for high‑value companion animal owners versus volume‑driven livestock customers—optimizing margin capture and distribution costs.
Closing perspective and next steps
The veterinary drug market in 2026 is simultaneously stable and dynamic: steady macro growth underpinned by demographic and behavioral demand drivers, combined with episodic regulatory and supply shocks that favor adaptive organizations. The CR3/CR5 concentration profile means scale and distribution still matter, but regulatory agility, biologics capability, and targeted commercial models are decisive differentiators for the next five years.
Our full Pw Consulting report delivers the granular segmentation, competitive scorecards, and ready‑to‑use financial models that senior teams need to convert insight into action. To access the complete dataset, therapeutic splits, and downloadable scenario models that underpin the forecast and strategic playbooks, view the full study at the source page. The summary here is intentionally directional—designed to establish priorities and present the strategic logic—and the complete report contains the detailed segment numbers and annexes required for transactional diligence and operational planning.
For immediate inquiries on bespoke strategic workshops, M&A screening, or a tailored 90‑day implementation plan aligned with the report’s findings, our industry team at Pw Consulting is prepared to engage directly with executive sponsors.
For detailed analysis of this topic, please visit the official page: Veterinary Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Remote Control Radio Equipment to reach USD 344.8M by 2032 at 6.98% CAGR – PW Consulting
By pmarketresearch, 2026-07-13
Remote Control Radio Equipment Market: Strategic Imperatives for 2026 — PW Consulting Preview
As organisations recalibrate capital allocation and product roadmaps for 2026, remote control radio equipment has moved from a niche industrial input into a strategic vector for operational productivity, safety compliance, and service-led revenue. PW Consulting’s new market research, anchored to a 2025 base year, projects a continuation of steady growth through our 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.98%. By taking a systems-level view of technology, regulation, and buying behaviour, this research provides the decision support that executives and product leaders need to convert momentum into durable competitive advantage.
Remote Control Radio Equipment Market
Why this study matters for 2026 decisions
-
Timing and scale: The market has expanded consistently in the early 2020s and, on our base-year measurement, global revenue reached a material level by 2025. That scale makes strategic moves (R&D investment, channel shifts, or M&A) meaningful to firm-level P&L and industry structure.
Remote Control Radio Equipment Market -
Regulatory inflection points: Policy changes in major markets — from the FCC’s equipment authorization adjustments to strengthened EU cybersecurity mandates under the Radio Equipment Directive — materially alter product compliance burdens and time-to-market for radio-enabled systems.
Remote Control Radio Equipment Market -
Safety and efficiency as value drivers: Stricter occupational safety regulation and evolving standards (for example, updates related to machinery and material handling) convert compliance into a buying criterion, enabling premium positioning for certified solutions.
-
Fragmented competitive landscape: Market concentration metrics show a relatively open field. While established OEMs and specialised suppliers dominate certain product segments, the overall industry remains amenable to focused consolidation, platform plays, and white-label OEM partnerships.
What the macro numbers tell us (high level)
Using a transparent, repeatable modelling approach, our analysis quantifies the current market and its trajectory through 2032. From a 2025 base year, the sector is forecast to grow at a mid-single-digit CAGR across the 2026–2032 horizon. This trajectory is consistent with durable demand driven by industrial automation, replacement cycles for legacy systems, and a gradual uptake of software-enabled “smart” controls that add lifecycle revenue through telematics and services.
Two structural observations underpin the headline figures: first, product upgrades are increasingly driven by non-functional requirements — safety, cybersecurity and integration — rather than raw cost-per-unit; second, aftermarket and service models represent a fast-growing margin pool for vendors who can capture telemetry and provide lifecycle services.
Competitive landscape: Reading the players for strategy
The market comprises a mix of long-established specialist manufacturers, OEM platforms, and systems houses that deliver safety-certified, ruggedised radio controls. Key incumbents — each with distinct strengths — offer a roadmap to where value concentrates and where disruption is most likely:
-
HBC-radiomatic — German-based manufacturer known for end-to-end production and safety-forward designs. Their vertical control of manufacturing and certification sets a high bar for reliability in crane and hydraulic applications.
-
Hetronic Group — US-headquartered, with strong focus on customization and operator safety. Their capability to tailor systems for specific clients signals an attractive route for premium, project-based revenues.
-
Tele Radio and Scanreco — Scandinavian producers that combine long heritage with OEM platform offerings. Their emphasis on durability and user ergonomics highlights the premium segment’s emphasis on total cost of ownership.
-
Autec , Cattron Group , OMNEX (Eaton) — These vendors reflect complementary strategies: modular product lines, systems integration and access to broader industrial portfolios, each offering different routes to scale and cross-selling.
-
Regional and niche specialists such as NBB, Akerstroms and Ikusi show that local regulatory knowledge and domain-specific certifications remain important barriers to entry in certain verticals.
Collectively, the top three and top five suppliers capture a limited share of the market by revenue, indicating a landscape that rewards targeted consolidation and platform aggregation. For strategists, this means M&A is a viable lever — but success requires careful integration planning around standards, certification credentials, and channel overlap.
Recent commercial signals (May 2026)
-
Trade show activity has been high-profile: leading suppliers demonstrated next‑generation wireless remotes and modular platforms at global events. These vendor showcases provide early insight into capability roadmaps and the speed of productisation for industry-specific use cases.
-
Exhibitions and product launches have emphasised modularity, safety certification, and integration with process-control ecosystems — a signal that future winners will be those who can translate hardware into systems-level value.
Regulatory and standards dynamics that will shape 2026 planning
-
FCC equipment authorisation rules : Recent changes limit certain modular transmitter authorisations for affected entities — a geopolitical and supply-chain risk that buyers and suppliers must actively manage. Sourcing and component validation strategies are now part of product due diligence.
-
EU Radio Equipment Directive (RED) : The Directive’s cybersecurity requirements impose design-level obligations (risk assessment, fraud protection) that can extend development cycles and increase the cost of compliance for entrants and incumbents alike.
-
Safety and industry standards : ISO and regional machine safety standards continue to evolve. Organisations that map product roadmaps to these standards early will turn compliance into a marketable advantage rather than a reactive cost.
What the PW Consulting report delivers — practical, transaction-ready intelligence
The full PW Consulting study is deliberately operational. It is designed not only to inform, but to be put to work by executives, product leaders, sales heads and corporate development teams. Highlights include:
-
Proprietary market-sizing and scenario forecasts (2026–2032), with transparent assumptions and sensitivity tables so you can re-run scenarios against your own adoption hypotheses.
-
Competitive scorecards and supplier capability matrices that evaluate certification, hardware platforms, software ecosystems, service capabilities and channel reach — enabling rapid shortlist creation for procurement and M&A screening.
-
Regulatory impact matrix mapping FCC, EU RED, ISO and national safety standards to product requirements and time-to-market implications; includes a compliance checklist for product and supply chain owners.
-
Go-to-market playbooks for three strategic archetypes: premium OEMs, systems integrators, and aftermarket-service specialists — each with pricing levers, channel models and sales KPI templates.
-
Technology and product roadmaps summarising tradeoffs between analog, digital and “smart” control architectures, along with practical recommendations on wireless protocols, encryption approaches, and telematics integration.
-
M&A diligence templates and synergy calculators that incorporate integration costs for certification, software harmonisation and channel realignment.
-
Commercial negotiation playbooks, RFP templates and a benchmarked supplier scorecard that support rapid procurement cycles without sacrificing compliance assurance.
Actionable recommendations for 2026 (prioritised)
-
Immediate (0–9 months) : Audit existing product lines for compliance gaps (RED, FCC authorisation and relevant ISO standards). Institute secure provisioning and firmware-update processes to meet cybersecurity obligations and to reduce recall risk.
-
Near-term (9–18 months) : Accelerate product modularisation and partner with certified wireless-component suppliers to mitigate authorisation and supply-chain risk. Pilot a service bundle that leverages telematics for predictive maintenance and recurring revenue.
-
Medium-term (18–36 months) : Evaluate acquisition targets that bring either certification expertise or software/telematics IP. Use the PW Consulting supplier scorecards and synergy tools to prioritise targets that reduce time-to-compliance and increase service monetisation.
-
Strategic (36+ months) : Build a platform play — standardise a core hardware/software stack and offer it via OEM/white-label channels. Use compliance as a market-entry barrier and differentiate on lifecycle services rather than unit price alone.
How to use this preview
This preview is intended as a strategic briefing: it highlights the directional forces, competitive players and regulatory shocks that should influence board-level and product-level decision-making in 2026. For practitioners ready to act, the full PW Consulting report supplies the confidential segmentation, detailed unit economics, and vendor-level financial benchmarks that drive executable plans. We intentionally withhold granular segmentation tables and proprietary supplier revenue splits in this public summary to protect the value of the underlying primary research and to encourage a direct engagement that will deliver tailored scenario modeling for your organisation.
If your team is preparing capital decisions, product roadmaps, or M&A strategies for the remote control radio equipment space this year, PW Consulting’s full report and advisory services convert market insight into executable roadmaps — from compliance remediation to product-platform plays and disciplined roll-up strategies. Contact our strategy desk to request the complete study or to book a briefing tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Remote Control Radio Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motor Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Motor Market 2026: Strategic Outlook and Action Playbook
Executive summary
As global electrification and automation accelerate, the motor market sits at an inflection point that will define industrial competitiveness and mobility strategies for the rest of the decade. Our Motor Market study, with base year 2025 and a historical window covering 2020–2025, projects the market to expand from an estimated USD 215.0 Million in 2025 to approximately USD 344.8 Million by 2032. This trajectory implies a compound annual growth rate (CAGR) of 6.98% across the forecast period (2026–2032). For corporate leaders making 2026 investment and portfolio choices, this study translates those headline numbers into measurable strategic options — but in this introduction we intentionally surface strategic insights while withholding the granular segment tables to encourage direct engagement with the full report.
Motor Market
Why the 2026 decision window matters
2026 is not merely another year on the growth curve. It is the first year of the forecast period and a practical decision point for capital allocation, supply-chain reorientation, and R&D prioritization. Between 2020 and 2025 the market expanded materially — our baseline grew from roughly USD 163.15 Million in 2020 to USD 215.0 Million in 2025 — demonstrating both resilience and structural momentum. The step-change projected for 2026 (to about USD 231.54 Million) signals that investments initiated in 2026 will capture the earliest portion of compounding returns that drive value through 2032.
Motor Market
Key macro implications for strategy
-
Growth with concentration: Despite healthy market growth, the competitive landscape remains fragmented. The top-three and top-five firms together account for approximately mid‑20 percent market shares (CR3 ≈ 24.6%, CR5 ≈ 26.2%). That fragmentation means scale matters but so does agility — there is room both for large incumbents to consolidate value and for focused challengers to win via niche specialization.
Motor Market -
Demand mix is shifting: Electrification of mobility and rising automation in manufacturing are dominant demand drivers. While we will not disclose the full split here, electric vehicles are the single largest end-market in the base-year construct; industrial automation and other sectors represent material, differentiated growth pockets. That split should influence product roadmaps and go-to-market models.
-
Materials and policy risk are now a strategic headwind: Rare earths, copper, aluminium and other critical inputs are central to product cost, technology choice and supply security. Recent regulatory moves — notably the EU Critical Raw Materials Act and escalated export-controls on rare earths — change how companies must model sourcing and localization risk.
Market dynamics that will shape winners and losers
Understanding the interplay of raw materials, technology cycles and policy is the axis on which near-term choices will compound into long-term advantage.
-
Raw material supply geometry: Demand for rare earth elements is set to surge in Europe and globally as permanent-magnet motor content rises with electrification. Policymakers in Europe are pursuing diversification and local aggregation of critical materials, while other jurisdictions have tightened export controls — a dynamic that can inflate procurement costs, delay product launches or force redesigns.
-
Regulatory architecture: The EU requirement to limit single-country dependency and the launch of centralized material-data infrastructures (e.g., the EU Critical Raw Materials Centre scheduled for launch in 2026) create both compliance obligations and opportunities to secure preferential project pipelines for firms that can demonstrate resilient sourcing.
-
Technology substitution and product mix: Innovations in motor topologies (e.g., synchronous reluctance, hairpin and S-winding technologies, magnetless designs) change the value equation between performance and material dependency. Companies that map expected material constraints into alternate architectures will preserve margins while meeting customer performance thresholds.
-
Price and efficiency sensitivity: A 10MW synchronous motor illustrates the scale of raw-material exposure (tons of copper, hundreds of kilograms of aluminium), underscoring why procurement strategies and engineering choices must be integrated. Small percentage gains in efficiency or reductions in rare-earth intensity can produce outsized commercial returns at scale.
Competitive landscape — what the leading players are doing
The market is being actively contested along three vectors: technology leadership (motor topology and manufacturing), program wins with OEMs (especially in EV platforms), and localized production footprints. Highlights from leading companies and recent developments illuminate tactical moves to watch in 2026:
-
ABB Ltd (Zurich) — continues to place bets on high-efficiency AC and synchronous reluctance motors, amplifying capabilities through demonstration facilities (for example, a new Berlin center opened in late 2025). Their strategy emphasizes combined efficiency and sustainability narratives for industrial automation and mobility customers.
-
Siemens AG (Munich) — retains emphasis on premium AC and DC motors for industrial drives and renewable-generation applications. Expect Siemens to press into integrated drive systems and services, targeting higher gross margins per installed base.
-
Nidec (Kyoto) — focuses on precision DC, e-axles and servo solutions for automotive and robotics; they remain an innovation nucleus for compact, high-density motor designs aligned with EV architectures.
-
WEG S.A. (Brazil) — leverages robust 3-phase AC platforms for heavy industries and energy markets, where durability and low total cost of ownership are competitive differentiators.
-
Regal Rexnord and Bosch Rexroth — pursue breadth in AC/DC and motion-control suites, respectively, prioritizing integrated solutions for HVAC, industrial automation and factory modernization.
-
BorgWarner — has accelerated its automotive focus through recent product awards and program wins across Asia and Korea, including hairpin and S-winding technologies for hybrid and high-voltage EV platforms; these contracts and rolling production phases (through 2027) are exemplar of program-driven scaling strategies in the e-mobility segment.
-
Toshiba and Hyundai Electric — continue to hold positions in large industrial and medium/high-voltage motor markets where utility and heavy-industry specifications dominate procurement decisions.
What the full report delivers (practical, transaction-ready content)
Our Motor Market study is designed for executive teams, corporate development groups, and product leaders who need actionable outputs for 2026 strategy cycles. Deliverables include:
- Transparent market-sizing and growth scenarios with sensitivity testing against commodity price and policy shocks;
- Supply-chain maps and tiered supplier scorecards that quantify single-source exposure and re-shoring opportunity;
- Technology roadmaps comparing magnet-intensive vs. magnet-lean architectures, with R&D timelines and cost-per-performance curves;
- Commercial playbooks: partner archetypes, OEM engagement templates, and service-led monetization models;
- M&A and JV scouting lists with fit/gap diagnostics and prioritized integration checklists;
- Regulatory impact models tailored to regional policy regimes and export-control scenarios;
- Customizable dashboards for scenario-driven capital allocation and product launch sequencing.
Recommended 2026 actions — a concise playbook
For leadership teams preparing 2026 budgets and roadmaps, we advise a balanced set of moves that protect margins, accelerate time-to-market, and hedge material risk:
-
Prioritize program-backed product investments: Allocate incremental capex to programs with signed OEM commitments or high-probability commercial pipelines to shorten payback cycles.
-
Localize critical inputs selectively: Use a risk-weighted framework to decide where to localize rare-earth processing or copper-intensive sub-assembly, focusing on regions with favorable regulatory incentives or customer proximity.
-
Adopt flexible engineering platforms: Invest in motor architectures that allow magnet substitution or different winding technologies without full redesigns, thereby protecting product roadmaps from material supply shocks.
-
Lock strategic partnerships: Pursue joint-ventures with material refiners, coil and stator assemblers, or software integrators to capture margin and secure supply continuity.
-
Instrument scenario planning: Use Monte Carlo–style modelling for commodity and regulatory shocks to set trigger points for hedging, capex deferments or accelerated rollouts.
-
Scan for opportunistic consolidation: Given the fragmented nature of the market, target tuck‑ins that add proprietary technologies, fill geographic gaps, or accelerate time to major OEM programs.
Conclusion and next step
The market's growth trajectory through 2032 is clear and strategically meaningful: structural demand from electrification and automation, combined with material and policy pressures, creates a landscape of both risk and disproportionate opportunity. The CR3 and CR5 figures illustrate a fragmented competitive terrain where disciplined scale and focused differentiation both pay. Our full Motor Market report converts the headline growth (CAGR 6.98% for 2026–2032) into executable recommendations, prioritized deal lists, and quantified risk mitigations — including the segment-level data, regional playbooks and sensitivity matrices that we have intentionally withheld here to maintain this piece as a strategic prelude.
To access the complete dataset, granular segment breakdowns, customizable dashboards and the full set of playbooks for 2026 execution, please refer to the Motor Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RV Reducer Market to Reach USD 870M by 2032 at 6.49% CAGR
By pmarketresearch, 2026-07-13
RV Reducer Market 2026: Strategic Imperatives from PW Consulting’s Forthcoming Study
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking primer on our RV Reducer Market research — a concise, high-signal preview crafted to inform executive decision-making in 2026. This synopsis highlights the study’s methodological rigor, the critical market dynamics we uncovered, and the practical use cases for commercial, procurement, and R&D leaders. In keeping with our “trailer” principle, we surface the analytical scaffolding and strategic implications while intentionally withholding detailed segment-level figures to motivate access to the full report for operational deployment.
RV Reducer Market
Why this report matters for 2026 decision cycles
-
Timing: The study’s base year is 2025, with a historical lens from 2020–2025 and a forecast horizon spanning 2026–2032. This alignment maps directly to many corporate planning and capex cycles, making the output immediately actionable for medium-term investments and supply-chain commitments.
RV Reducer Market -
Macro trajectory: We quantify the global RV reducer market trajectory with a clear and consistent methodology. The market expanded steadily through 2020–2025 and enters the forecast period at a compound annual growth rate (CAGR) of 6.49%, reaching materially higher scale by 2032. These topline dynamics underpin revenue models, IRR calculations, and M&A valuation multiples used by strategic and financial buyers.
RV Reducer Market -
Concentration and competitive intensity: Market concentration is substantial — the combined revenue share of the three largest firms accounts for a dominant portion of the market, with the top five players controlling an even larger share. This concentration creates predictable supplier landscapes but also exposes buyers to supplier-specific risks that should factor into sourcing strategies.
Data-driven snapshot (high level)
-
Historical growth: Our sizing shows consistent year-on-year expansion from 2020 through 2025, reflecting resilient demand across robotics, machine tools, and semiconductor equipment applications.
-
Forecast posture: From a 2026 starting point we project steady growth through 2032, with cyclical variance tied to capital expenditure trends in automation and fab expansion phases. The model uses scenario-based drivers (base, upside, downside) that incorporate technology adoption curves and supply-chain stress testing.
-
Units and currency: All revenue figures in the full study are presented in USD (Million), with transparent FX and inflation adjustments documented in the methodology appendix.
Core dynamics shaping the market
-
Demand-side drivers: Continued adoption of industrial robotics, increased automation across discrete and process industries, and ongoing semiconductor equipment investment are primary growth engines. Customers demand higher torque density, lower backlash, and improved lifetime performance — pushing suppliers to invest in precision metallurgy, advanced gearing geometries, and tighter QA regimes.
-
Supply-side constraints: Specialized high-strength steel remains the primary raw material. Our supply-chain analysis identifies persistent volatility — lead times have lengthened and, in some cases, increased production delays by as much as 20% in recent years. This has direct financial and operational impacts: elevated inventory buffers, longer supplier qualification cycles, and premium logistics costs.
-
Standards and testing: In February 2025 new factory testing standards for vibration characteristics were published. These standards raise the bar for product validation and will accelerate differentiation toward manufacturers capable of higher-fidelity testing and tighter tolerancing, while increasing compliance costs for smaller producers.
-
Consolidation and specialization: High market concentration (CR3 and CR5 metrics documented in the full report) suggests an industry where scale, legacy OEM relationships, and proven reliability confer material advantages — but there remains opportunity for nimble regional players and technology specialists to capture adjacencies.
Competitive landscape — what to watch
-
Nabtesco Corporation (Osaka, Japan) — A global benchmark in RV precision reduction gears with a multi-million unit track record and deep relationships with major robot OEMs. Their product breadth and scale advantage make them a de facto partner for heavy-load, high-reliability applications. Strategic considerations: OEMs and tier-one integrators will prioritize long-term contracts and co-development arrangements with suppliers of this caliber.
-
Nantong Zhenkang Welding Electromachinery Co., Ltd. (Haimen, Nantong, Jiangsu, China) — A high-volume specialist for welding and industrial automation, with significant annual production capacity. Strategic considerations: firms seeking cost-competitive capacity or regional redundancy should evaluate partnerships with established Chinese producers, while accounting for quality certification and IP safeguards.
-
Shenzhen PICEA Motion Technology Co., Ltd. (Shenzhen, China) — Focuses on precision RV reducers and harmonic drives, catering to both robots and automation systems. Strategic considerations: PICEA represents a supplier archetype that blends targeted engineering capability with flexibility for co-design in medium-volume programs.
-
TallMan Robotics (China) — Producer of multiple cycloidal reducer series serving automation and robotics. Strategic considerations: smaller, specialized suppliers are often faster in iterative product development and competitive for niche or fast-evolving applications.
Our full report includes a detailed competitor matrix: product roadmaps, vertical coverage, manufacturing footprints, capacity buffers, IP profiles, and strategic plays (pricing, OEM alliances, aftermarket service). We stratify competitors by capability — from global system suppliers to specialized regional manufacturers — enabling tailored go-to-market and procurement actions.
Practical deliverables and operating tools in the report
The research is designed as a toolkit for immediate application across corporate functions. Highlights include:
-
Robust market-sizing methodology and a reconciled historical dataset (2020–2025), plus a transparent forecast model (2026–2032) that companies can reparameterize for internal planning scenarios.
-
Supply-chain risk heat maps and mitigation playbooks: supplier diversification templates, qualification checklists, and inventory optimization levers tied to material-specific lead-time stress tests.
-
Technology and product roadmap analysis: lifecycle assessments for cycloidal, harmonic, and planetary architectures (discussed qualitatively here), and recommendations for where incremental R&D yields the highest ROI.
-
Commercial strategies: segmentation frameworks for pricing, channel selection, and aftermarket service models that protect margin while supporting customer retention.
-
M&A and partnership playbook: target profiles, valuation sensitivities, integration risk checklists, and a shortlist of capability gaps that acquirers commonly pursue.
-
Regulatory and compliance compendium: implications of the 2025 vibration testing standards, recommended factory testing investments, and certification timelines to reduce time-to-market friction.
-
Scenario-driven financial templates: sensitivity analyses for capital expenditures, margin compression, and demand shocks, enabling CFOs to stress-test P&L and balance sheet outcomes.
Strategic actions for leadership in 2026
-
Procurement leaders: institute dual-sourcing strategies for high-strength steel suppliers and qualify secondary manufacturers in cost-advantaged regions. Incorporate lead-time penalties and dynamic reorder points into procurement contracts to mitigate the 20% lead-time variability we observed.
-
Product and R&D heads: prioritize investments in vibration-control engineering and factory testing capability to comply with 2025 standards and to create product differentiation. Consider modular designs that compress qualification cycles for new SKUs.
-
Commercial and alliance teams: renegotiate OEM contracts with clauses that reflect scale-driven pricing benefits while safeguarding supply continuity. Evaluate aftermarket service and training offerings as margin-enhancing revenue streams.
-
Strategy and corporate development: use our scenario models to size opportunistic M&A targets that close capability gaps (e.g., manufacturing process control, precision metallurgical expertise) and to quantify integration payback under conservative demand assumptions.
Risk landscape and mitigation
-
Material scarcity and supplier concentration: proactively invest in supplier development, backward integration options, or long-term supply agreements to lock-in critical inputs.
-
Regulatory execution risk: accelerate compliance roadmaps for factory testing and embed certification timelines into product launches. Early adopters of the new vibration testing standards will gain procurement preference among risk-averse OEMs.
-
Market concentration risk: high CR3/CR5 metrics imply both stability and vulnerability. Buyers should map single-supplier exposures and develop contingency sourcing plans to avoid production stoppages.
How PW Consulting’s study empowers 2026 planning
This research blends quantitative rigor (historical reconciliation, CAGR-backed forecasting, and scenario modularity) with pragmatic deliverables (playbooks, checklists, and financial templates). For executives, the key value is decision-intelligence: calibrated inputs that transform instincts about supplier risk, product investments, and M&A timing into defensible, traceable strategic moves. Whether you lead procurement, product, finance, or corporate development, the study delivers a compact yet comprehensive foundation to prioritize investments, refine negotiating positions, and allocate capital under uncertainty.
Next steps
-
Access the full study to retrieve segment-level breakdowns, detailed competitor profiles, and downloadable financial models. The preview intentionally omits those granular splits to preserve the analytical value of the complete deliverable.
-
Engage PW Consulting for a tailored workshop: we can apply the forecast models to your product lines, run supplier risk simulations, or build bespoke M&A screens aligned to your corporate strategy.
In an industry where mechanical precision and supply-chain resilience intersect, the right intelligence at the right time materially changes outcomes. Our RV Reducer Market study is engineered to be that intelligence for 2026 — ready to convert macro trends into tactical advantage.
For detailed analysis of this topic, please visit the official page: RV Reducer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com