

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Active Air Sampler Market to Hit USD 594.5M by 2032 at 6.5% CAGR

Active Air Sampler Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
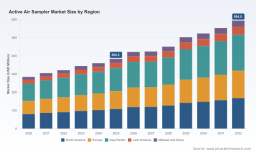
PW Consulting’s new Active Air Sampler Market study delivers a pragmatic intelligence package aimed squarely at the decisions you will make in 2026. The market for active air samplers has shown steady expansion through the recent historical window (2020–2025), rising from approximately USD 285 Million in 2020 to USD 384.3 Million in the base year 2025. Our baseline forecast (2026–2032) projects continued growth to roughly USD 594.5 Million by 2032, implying a compound annual growth rate (CAGR) of 6.5% across the forecast period.
Active Air Sampler Market
Those topline figures capture both structural tailwinds (regulatory tightening, biopharma manufacturing scale‑up, and renewed focus on food/health safety) and the tactical responses of vendors (product, service and digital integration). This preview highlights why these dynamics matter for procurement, R&D, M&A, and service strategy in 2026 — while deliberately preserving detailed subsegment data and granular regional splits to encourage access to the full study.
Active Air Sampler Market
Why this study matters for decisions made in 2026
- Regulatory inflection is real and immediate. Updates to cleanroom and aseptic processing guidance have elevated the commercial importance of validated, continuous viable monitoring and documented data integrity. Compliance timelines and validation build windows mean procurement cycles initiated in 2026 will determine equipment and service footprints for several years.
- Technology convergence reshapes value chains. The integration of active samplers with remote sampling, real‑time particle counters and digital logging platforms is changing purchase criteria from pure instrument cost to integrated solution economics.
- Service & calibration becomes a competitive moat. As buyers prioritize chain‑of‑custody, calibration integrity and 21 CFR/ISO aligned documentation, vendors with robust service networks and accredited calibration offerings capture higher lifetime value.
- Fragmentation creates both risk and opportunity. Market concentration metrics show the industry remains fragmented (CR3 ~19.8% and CR5 ~24.5%), signaling acquisition opportunities for strategic consolidators and whitespace for focused specialists.
- M&A and partnerships will accelerate. Strategic investments and technology partnerships are already visible; the next 12–24 months will separate nimble integrators from single‑product incumbents.
What the full report delivers — practical contents for immediate action
- Market sizing and validated forecasting (base year 2025, historical 2020–2025, forecast 2026–2032) with scenario and sensitivity testing to stress‑test capex plans.
- Segmentation frameworks by region, product type and application, with decision‑grade worksheets for prioritizing addressable revenue pools (note: granular split tables and proprietary subsegment figures are available only in the full report).
- Competitive landscaping and vendor scorecards assessing product portfolio breadth, regulatory fit, digital maturity, service footprint, and channel strategy.
- Regulatory mapping — line‑by‑line implications of EU GMP Annex 1 and ISO 14698‑1 for procurement specifications, validation requirements, sampling protocols, and audit readiness.
- Technology deep dives covering impactor technologies, cyclonic samplers, membrane and gelatin filtration approaches, remote sampling platforms, and real‑time microbial detection integrations.
- Go‑to‑market playbooks and procurement templates: validated RFP language, acceptance test scripts, ROI and TCO calculators, and sample service level agreements.
- Strategic recommendation engine for M&A targeting, partnership screening, and product roadmap prioritization — including a short list of capability gaps buyers and vendors should address immediately.
Competitive landscape — tactical takeaways for vendors and buyers
The vendor universe is populated by specialist instrument makers and larger life‑science players. Several archetypes are visible: engineering‑first innovators focusing on sampling technology (impactors, cyclonic samplers, membrane solutions), platform integrators pursuing digital/data integrity advantages, and service‑centric players anchoring sales through accredited calibration and support networks.
Active Air Sampler Market
- Product innovators: Companies producing cyclonic samplers and multi‑head impactors are advancing sampling efficiency and usability. These firms compete on throughput, capture efficiency and ergonomic design.
- Platform integrators: Vendors offering remote/automated sampling capable of integration with particle counters and LIMS are capturing incremental value as buyers prioritize continuous monitoring and audit trails.
- Compliance & service specialists: Firms that combine instrument sales with ISO/17025‑grade calibration, 21 CFR Part 11–aligned data management and field validation become preferred partners for large regulated customers.
Representative vendors in the market exemplify these archetypes. For example, certain U.S. and European manufacturers offer remote Annex 1‑compliant samplers designed for aseptic Grade A/B environments, while other European and Asian manufacturers focus on portable impactor devices and membrane filter solutions for traditional viable monitoring. Notable moves in the recent timeline reinforce strategic direction: a Swiss vendor launched a next‑generation active microbial air sampler in May 2026 emphasizing improved usability for cleanroom monitoring, a major French life‑science company invested in a real‑time air microbial particle counter integrator in March 2026, and a U.S. supplier received ISO 17025 accreditation for calibration services in late 2025. These events demonstrate the market’s twin emphasis on product refinement and service/accreditation as competitive levers.
Regulatory and technical dynamics shaping procurement
- EU GMP Annex 1 & ISO 14698‑1: Both documents are driving purchases toward systems that facilitate validated continuous viable monitoring, traceable sample handling and documented method performance. Buyers must embed Annex 1 and ISO requirements into technical specifications and acceptance testing.
- Data integrity and remote monitoring: Requirements such as 21 CFR Part 11 compliance and secure electronic records are elevating expectations for onboard software, audit logs, and integration capabilities.
- Validation first, features second: For regulated customers, validated performance (recovery efficiency, repeatability under cleanroom conditions) often trumps minor feature differentials; vendors must prioritize validation packages and ready‑to‑deploy protocols.
Four‑point strategic playbook for 2026
- For vendors — product & validation roadmap: Prioritize modular designs that support both portable and remote deployment, publish independent validation data aligned to ISO 14698‑1, and bundle documented Annex 1 compliance aids to reduce buyer friction.
- For service leaders — accreditation & network expansion: Invest in ISO 17025 capabilities, scale field calibration teams in key manufacturing clusters, and offer subscription‑based calibration and validation services to convert transactional sales into recurring revenue.
- For strategic buyers — procurement discipline: Convert regulatory requirements into mandatory RFP pass/fail criteria (validation artifacts, software audit trails, service SLAs). Evaluate total cost of ownership including calibration cadence, consumables, and validation labor — not just capital price.
- For consolidators — targeted M&A & partnerships: Seek targets that add either accredited calibration infrastructure or digital sampling/real‑time detection capabilities. Partnerships with specialist integrators can accelerate time‑to‑market for combined hardware/software propositions.
Why PW Consulting’s report is uniquely actionable
We combine rigorous top‑down market sizing (base year 2025; historical 2020–2025; forecast 2026–2032) with bottom‑up device, consumables and services economics to produce decision‑grade outputs. Our vendor scorecards synthesize product validation, regulatory fit, service footprint and digital maturity into a single advisory framework that procurement, product and corporate development teams can operationalize. The report also contains editable procurement templates, validation checklists, and M&A screening matrices that accelerate execution timelines for 2026 initiatives.
How to use this preview — next steps
This briefing is intended as a strategic “trailer”: it exposes the trends, vendor archetypes and regulatory drivers that will shape budgets, roadmaps and M&A moves in 2026, while intentionally withholding proprietary subsegment tables and granular regional/application splits. If you are preparing procurement cycles, launching product development initiatives, or evaluating acquisition targets this year, the full PW Consulting report provides the detailed split‑level intelligence, vendor benchmarking matrices and customizable templates that translate insight into action.
Contact PW Consulting to access the complete study and receive a tailored briefing that maps the findings directly to your organization’s product, procurement and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Active Air Sampler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com