

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laser Depaneling Market Poised for 8.1% CAGR Through 2032

Laser Depaneling Machine Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest industry insight frames laser depaneling as a maturing, consolidation-prone equipment market that is increasingly central to high-mix, high-reliability electronics manufacturing. This preview highlights the strategic value of the full study for executives planning CapEx, supply-chain repositioning, or product-line transitions in 2026. It demonstrates the depth of our analysis while intentionally withholding granular segment tables and proprietary model outputs — the full intelligence package is available in the complete report.
Laser Depaneling Machine Market
Market at a Glance — Macro Trajectory
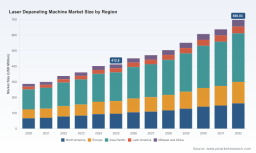
Between 2020 and 2025, the laser depaneling machine market expanded from roughly USD 287 million to approximately USD 413 million, driven by growing requirements for low-stress singulation across consumer, automotive, medical and aerospace electronics. Our forward-looking base-year is 2025 and we model an 8.1% compound annual growth rate for the 2026–2032 forecast window. Under base-case assumptions the market reaches nearly USD 700 million by 2032, with non-linear acceleration tied to high-volume automotive electrification programs and continued substitution away from mechanical routing in selected geographies.
Laser Depaneling Machine Market
Why This Research Matters for 2026 Strategy
- CapEx prioritization with precision: Buyers and OEMs can no longer treat depaneling as a commodity. The report aligns technology roadmaps with production volumes, scrap-reduction targets, and line-balancing metrics to produce actionable CapEx triggers for 2026 procurement cycles.
- Supplier selection under consolidation: The market shows meaningful concentration among a small set of global vendors. The full analysis provides a defensible procurement playbook — from preferred supplier lists to contract length and upgrade-path negotiation levers — enabling procurement teams to capture better TCO outcomes in supplier-dominant markets.
- Risk-aware automation decisions: Integrating laser depaneling into Industry 4.0 stacks reduces labor dependency while raising requirements for MES/ERP interoperability and predictive maintenance. Our scenarios quantify exposure to labor constraints and energy volatility, turning abstract operational risks into prioritized mitigation actions.
What the Full Report Contains — Practical Outputs
Clients will find the report deliberately operational. Highlights include:
Laser Depaneling Machine Market
- Top-down market sizing and a transparent reconciliation of historical shipments and installed base dynamics (2020–2025), plus a seven-year forecast with three scenario bands.
- Technology adoption roadmaps and maturity curves for UV, fiber, CO2 and hybrid approaches — assessing fit by board substrate, thermal sensitivity and line throughput targets (note: detailed share tables are withheld in this preview).
- Vendor scorecards and heatmaps across performance, automation, software, service footprint and upgradeability — practical benchmarks for RFPs and supplier development programs.
- CapEx decision frameworks that translate production KPIs (yield, takt time, changeover time) into payback periods and IRR ranges. Included are modular financial models for quick sensitivity analysis by plant, product family, and region.
- Supply-chain maps and procurement playbooks covering laser modules, optics, motion systems and vision subsystems, plus critical single-source risk flags and recommended dual-sourcing architectures.
- Regulatory and compliance implications for high-reliability markets (automotive, aerospace, medical) including quality traceability and edge integrity requirements — with implementation checklists for quality engineers.
- Implementation blueprints for automation and MES integration, including data models, SMEMA and pick-and-place interface examples, and best-practice P-FMEA items tailored to depaneling processes.
Each chapter includes prescriptive appendices (sample RFP language, test protocols, and acceptance criteria) to accelerate internal alignment between engineering, procurement, and operations teams.
Market Dynamics — Drivers and Headwinds
The market’s growth is shaped by a cluster of technology and supply-side forces:
- Technology substitution: Laser depaneling is displacing mechanical routing in many high-volume and high-mix lines because it reduces mechanical stress, lowers scrap, and supports ultra-thin and flexible substrates. This substitution is uneven by product family and geography; our report provides the decision-tree to quantify replacement economics at the product-line level.
- Automation and labor economics: Integration with MES and higher degrees of automation respond directly to labor shortages and the premium on consistent line yields. The research models labor-availability sensitivity and identifies the operational ROI thresholds at which automation investments become irreversible.
- Edge-quality and regulatory tightening: Higher-spec applications in automotive and aerospace have driven the integration of AI-assisted kerf monitoring and adaptive power modulation on recent UV platforms. These capabilities materially alter warranty exposure and product reliability economics for OEMs.
- Energy and sustainability: New system architectures that reduce carbonization and particulate generation (and thereby secondary cleaning) are delivering both energy and environmental benefits — an increasingly important procurement criterion for Tier‑1 OEMs and EMS providers.
- Consolidation and supplier power: A concentrated vendor landscape raises the importance of contractual design and lifecycle service agreements. The full report includes negotiation playbooks and a vendor-risk heatmap to protect margin and service continuity.
Competitive Landscape — Who Matters and Why
The competitive field includes established laser specialists, automation integrators, and regional OEMs. Key players we profile in depth include LPKF Laser & Electronics, ASYS Group, Genitec, Han’s Laser, IPTE, Seika Machinery, Aurotek, CMS Laser, and Photonics Systems Group. Our vendor analysis focuses on the following dimensions:
- Technology differentiation: UV platforms with CleanCut or equivalent low-HAZ technologies, and fiber systems optimized for copper- and power‑electronics-heavy boards, represent distinct value propositions. We map application-fit against these capabilities to help OEMs choose the right architecture for a given PCB family.
- Automation and software: Vendors that bundle robust vision systems, fiducial alignment, and software connectivity win in high-mix SMT lines. We profile software stack maturity and upgrade pathways for each major supplier.
- Service and aftermarket: Given the installed-base economics, spares and regional service presence are often decisive. The report grades each supplier on response times, spare-parts logistics, and retrofit options.
- Recent strategic moves: We track product launches and live demonstrations that signal technology and commercial intent — for example, the introduction of AI-assisted quality monitoring on new UV platforms and multiple live showcases at major trade events in 2026. These events are early indicators of feature adoption curves and roadmap acceleration.
How to Use This Research in 2026 Planning Cycles
- Procurement teams: Use the vendor scorecards and TCO models to create a pre‑qualified supplier roster for 2026 RFQs, and to determine optimal warranty and service-contract lengths.
- Operations and engineering: Run the included CapEx calculators against representative SKUs to determine which product families should be migrated to laser depaneling in the next 12–36 months.
- Corporate strategy and M&A: The market’s concentration and the presence of technology adjacencies create acquirable assets — from vision software to specialized motion control — that can accelerate capability buildups. The report includes acquisition candidate criteria and valuation heuristics tailored to strategic buyers.
- R&D and product management: Leverage the technology roadmaps and kerf‑quality standards to prioritize feature development and interoperability with customers’ MES ecosystems.
Methodology, Transparency and Limitations
Our approach triangulates proprietary shipment data, vendor disclosures, public financials, trade-show telemetry and OEM interviews. The report documents assumptions, growth drivers and sensitivity ranges so clients can validate and update models with their internal data. In keeping with the “trailer” principle, detailed subsegment tables and regional/application share matrices are excluded from this preview — those datasets form part of the licensed package and are essential for site‑ or product‑level decisioning.
Next Steps — Accessing the Complete Intelligence
For executives who need to convert the macro picture into executable plans in 2026 — including supplier negotiation scripts, plant-level TCO models, and migration maps for product portfolios — PW Consulting’s full Laser Depaneling Machine Market report supplies the data and tools required. The full deliverable includes editable financial models, RFP templates, and a bespoke advisory session to translate findings into a 12–24 month implementation roadmap.
Contact details and the purchase pathway are available on the report landing page. The preview presented here is designed to clarify the report’s strategic value and scope; the granular segmentation matrices, supplier scorecards and regression models are available only with the complete study.
For detailed analysis of this topic, please visit the official page: Laser Depaneling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com