

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Recombinant Proteins Market to Reach USD 5.75 Billion by 2032
By pmarketresearch, 2026-07-13
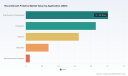
Recombinant Proteins Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As leaders in life sciences strategy, PW Consulting presents an executive preview of our forthcoming Recombinant Proteins Market study. This piece translates macro-market momentum, vendor shifts, and supply-chain inflection points into the practical decision inputs that corporate boards, business unit leaders, and investors must use in 2026. Consider this a trailer: rigorous, insight-rich, and purposefully selective. We reveal the directional drivers and competitive signals but withhold the granular segment matrices that make the full study an indispensable decision tool.
Recombinant Proteins Market
Market Snapshot: Direction and Scale
The recombinant proteins market has transitioned from a specialized research reagent market into a core enabling layer for biopharmaceutical R&D, cell and gene therapy, and scaled biologics manufacturing. Our base-year analysis (2025) captures a market that has more than doubled since 2020 and is on a sustained growth path driven by therapeutic pipeline expansion, diagnostics automation, and the industrialization of cell therapies.
Recombinant Proteins Market
- Historical growth demonstrates a clear acceleration from early-research demand toward clinical and GMP-grade adoption.
- Our forecast through 2032 projects continued expansion at a compound annual growth rate (CAGR) of 10.5%, reflecting durable end-market drivers as well as recurring revenue opportunities in reagent and GMP product portfolios.
- Market concentration is meaningful but not monopolistic: the three largest firms account for a plurality of sales, while a broader group of specialist players capture substantial niche value. This creates both consolidation opportunities and room for focused entrants.
Why 2026 Is a Strategic Inflection Point
Multiple forces converge in 2026 to reshape supplier economics and customer sourcing strategies:
Recombinant Proteins Market
- Industrialization of cell and gene therapies is driving demand for GMP-grade cytokines, growth factors, and engineered proteins at scale.
- Manufacturing innovation — including methanol-free yeast platforms and cell‑free protein synthesis — is reducing variable costs and accelerating discovery-to-manufacturing timelines.
- Geopolitical and regulatory pressures are increasing the cost and complexity of global supply chains, prompting firms to evaluate onshore capacity and diversified sourcing.
These combined trends force a reassessment of sourcing, vertical integration, strategic partnerships, and R&D operating models in 2026. Companies that act now can lock in supply, mitigate regulatory timelines, and capture disproportionate share in adjacent biologics workflows.
What the PW Consulting Recombinant Proteins Report Delivers
The full report is built as a decision-ready toolkit rather than an academic monograph. It synthesizes macro demand trajectories, supplier capabilities, technology roadmaps, and regulatory friction into actionable outputs that executives can apply immediately.
- Strategic frameworks: go-to-market options for reagent suppliers, CDMOs, and biopharma end-users — including build vs. buy decision matrices and partnership archetypes.
- Supply-chain playbooks: supplier qualification scorecards, dual-sourcing templates, and inventory buffers calibrated to biologics product lifecycles and regulatory validation timelines.
- Commercial operating models: pricing levers, contract structures for long-term GMP supply, and commercialization scenarios for catalog vs. custom production.
- M&A and investment checklists: diligence protocols emphasizing technical transfer risk, regulatory readiness, and capacity scalability for strategic acquirers.
- Scenario planning toolsets: three scenario pathways (base, accelerated-adoption, and constrained-supply) with trigger indicators executives can monitor monthly or quarterly.
Each practical module in the report is supported by proprietary market sizing, growth curves, and supplier capability matrices — presented in a way that enables board-level decision-making without requiring additional modelling work.
Competitive Landscape: Who Matters Now
The competitive field is a mix of diversified life-science majors, specialized reagent houses, and manufacturing-focused CDMOs. Below we sketch the core players and their strategic positioning — a succinct map for executives weighing partnership or competitive moves.
- Thermo Fisher Scientific Inc. — Leveraging scale and brand to supply recombinant cytokines, growth factors, and antibodies across research to GMP grades. Strengths: broad catalog, integrated workflow brands, channel reach.
- Bio‑Techne Corporation — Positioned on GMP-grade cytokines and growth factors with manufacturing capacity aimed at cell therapy and biologics clients. Strengths: GMP focus, application know-how, customer education resources.
- Sino Biological, Inc. — Rapid catalog expansion and investment in cell-free synthesis and endotoxin‑low portfolios to serve discovery and applied biologics workstreams. Strengths: high-throughput capability, cost-positioning, product breadth.
- GenScript Biotech Corporation — End-to-end services from design to in-house production, addressing research and early therapeutic development needs. Strengths: integrated service model, flexibility for custom projects.
- ACROBiosystems, Inc. — Niche focus on discovery and preclinical grades optimized for assay development and translational research. Strengths: targeted product optimization, speed to market for assay customers.
- Olon S.p.A. and myBIOS GmbH — Industrial-scale microbial fermentation capability (including Pichia platforms) and recent partnerships that emphasize sustainable, methanol-free production at scale. Strengths: industrial fermentation expertise and green manufacturing pathways.
Market activity through early‑ to mid‑2026 underscores a pattern: incumbents are expanding GMP offerings and platform capabilities, while smaller specialists push innovation (e.g., cell‑free synthesis, endotoxin-minimized processes) to capture upstream discovery and translational demand.
Recent Developments with Strategic Implications
- Olon + myBIOS partnership (Mar 2026): a move toward methanol‑free Pichia platforms that reduce environmental risk, simplify regulatory filings related to hazardous feedstocks, and lower operational complexity for industrial production.
- Bio‑Techne closed‑system manufacturing content (Jan 2026): signals enhanced focus on integrated workflows for cell therapy customers — a content and capability play to win long-term GMP contracts.
- Sino Biological launches (Apr–May 2026): investments in endotoxin‑low protein portfolios and cell‑free synthesis kits indicate a bifurcation of supplier strategies — low-cost/high-throughput discovery tools versus high-quality GMP-ready products.
Collectively, these moves validate a two-track competitive environment: platform and scale investments from established players, and disruptive process technologies from agile specialists. Successful corporate strategies will combine tactical partnerships with targeted internal investments.
Regulatory and Supply-Chain Headwinds
Executives must plan for friction outside of pure market demand:
- Raw-material volatility: recent disruptions to amino acids and trace-metal supply chains have produced meaningful short-term price volatility for culture media feeds. Buyers need dynamic sourcing models and contractual hedges for critical inputs.
- Regulatory timelines: stricter guidelines on animal‑derived components and validations in major markets can add 18–24 months to time-to-market for some GMP products. Regulatory readiness must be integrated into product and M&A timelines.
- Geopolitical constraints: export controls and trade restrictions influence supplier selection, tech-transfer partners, and localization decisions. Scenario planning must assume periodic restrictions as a baseline risk.
Actionable Strategic Playbook for 2026
Below are high‑priority actions for companies seeking to convert market momentum into competitive advantage this year.
- Execute supplier rationalization with resilience scoring: use a dual metric of technical capability and geopolitical reliability when narrowing qualified suppliers for GMP-grade inputs.
- Prioritize platform partnerships over bolt-on acquisitions for rapid capacity needs: partnerships with industrial fermenters or cell‑free providers can deliver faster throughput with lower integration risk.
- Embed regulatory lead‑time into portfolio decisions: require 18–24 month validation buffers for any product path that depends on animal‑derived media or international tech transfers.
- Design commercial contracts with volume flex and price‑indexing clauses to share raw-material volatility risk between suppliers and buyers.
- Use M&A diligence to stress-test technical transfers under real-world lab conditions — not only certificates and SOPs — before pricing transactions.
How Boards and Investors Should Use the Full Report
Boards evaluating strategic options in 2026 should view the PW Consulting Recombinant Proteins study as a tactical playbook and a decision-accelerator. Use the report to:
- Validate portfolio prioritization: determine which reagent families merit investment, divestiture, or partnership based on scalable demand and regulatory complexity.
- Calibrate CAPEX vs. outsourcing: our ROI calculators and break-even analyses show when building internal GMP capacity is justified versus contracting external CDMOs.
- Set KPIs and watchlists: adopt the report’s recommended trigger indicators (supply constraint alerts, raw-material price bands, regulatory milestones) to convert market signals into board-level decisions.
Final Note — Why the Full Study Matters
This preview identifies the tectonic shifts shaping the recombinant proteins market in 2026: platform innovation, supply-chain fragility, regulatory elongation, and a competitive landscape that rewards both scale and niche technical excellence. The complete PW Consulting report translates these dynamics into fully specified models, vendor scorecards, contract templates, and scenario-driven financials — the inputs necessary to move from strategic intent to executable plans.
Access to the full dataset and the operational toolset is intentionally gated: those elements contain the segment-level granularity and supplier benchmarks that materially change negotiation outcomes and M&A valuations. For executives preparing budgets, strategic partnerships, or capital allocations for 2026, this is the missing dossier.
Contact
PW Consulting’s Recombinant Proteins Market study is available now. To license the full report, bespoke advisory, or to commission a tailored scenario analysis, contact our Life Sciences Strategy practice. Equip your executive team with the market intelligence to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Recombinant Proteins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Forensic Accounting Market to Hit USD 1,221 Million by 2032
By pmarketresearch, 2026-07-13
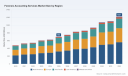
Forensic Accounting Services Market — Strategic Outlook for 2026 Decision‑Makers
As organizations recalibrate risk appetites and compliance frameworks for a new regulatory and technological era, forensic accounting has moved from a specialist discipline to a board‑level capability. PW Consulting’s upcoming Forensic Accounting Services Market study (base year 2025) offers a practical, decision‑grade compass for executives, in‑house counsel, risk officers, and advisory firms preparing strategic moves in 2026 and beyond. The market reached approximately USD 700 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.2% across the 2026–2032 forecast window — a trajectory that frames both near‑term investment priorities and medium‑term capability gaps for enterprises and service providers alike.
Forensic Accounting Services Market
Why this study matters for 2026
-
Convergence of risk vectors. Cyber breaches, complex financial crime, cross‑border litigation, and heightened regulatory scrutiny are converging into multi‑disciplinary investigations that demand integrated forensic accounting, digital forensics, and legal coordination. The market dynamics embedded in this study quantify that convergence and translate it into practical options for allocating spend, talent, and technology in 2026.
Forensic Accounting Services Market -
Capital allocation and M&A timing. With forensic accounting services growing at a mid‑single‑digit premium to adjacent professional services, the study provides the revenue and growth context that informs acquisition bench‑building, bolt‑on strategies, and greenfield investments — particularly where specialized boutiques or regional practices can fill capability gaps quickly.
Forensic Accounting Services Market -
Talent and cost management. Premiums for Certified Fraud Examiners (CFE) and experienced forensic accountants are measurable and persistent; the report translates labor cost inflation and certification premia into workforce planning scenarios, bill‑rate models, and retention playbooks suitable for 2026 budgeting cycles.
Core drivers shaping the market
-
Regulatory and standards pressure. Enforceable professional standards and sector guidance (including contemporary updates to the AICPA’s forensic services guidance) have raised baseline expectations for methodology, documentation, and expert testimony. Our analysis identifies which parts of the forensic workflow will be subject to the most immediate scrutiny and which controls companies should prioritize in 2026 to reduce legal and reputational exposure.
-
Technology and analytics. Forensic analytics tools — from anomaly detection engines to provenance tracing — are entering widespread commercial use. Large advisory firms and niche tool vendors are investing in integrated stacks. The net effect: faster evidence discovery cycles but higher vendor diligence requirements. The study maps the vendor taxonomy, capability tiers, and the practical tradeoffs between build, buy, and partner strategies.
-
Cyber‑forensics coupling. Recent strategic partnerships between major professional services firms and cybersecurity specialists underscore a structural shift: forensic accounting engagements increasingly require deep data security and incident response capabilities. We evaluate how firms can operationalize this coupling without creating duplication or compliance gaps.
-
Litigation intensity and alternative dispute mechanisms. Corporate restructurings, bankruptcy proceedings, and global arbitration trends have sustained demand for litigation support and expert testimony. The report models demand drivers for dispute‑related engagements and the commercial levers firms can use to capture that work.
What the report delivers — practical content for implementers
-
Comprehensive market sizing and growth scenarios. We present a base‑case market sizing for 2025 and model growth through 2032 under multiple adoption and regulatory scenarios to support capital planning.
-
Service and delivery playbooks. Usable templates for structuring fraud investigation, litigation support, risk assessment, and bankruptcy engagements — including team composition, evidence flows, and quality checkpoints.
-
Vendor and capability heatmaps. Benchmarks of global and regional providers across technical skills, digital forensics, expert witness track record, and pricing models — designed for rapid shortlist development and RFP issuance.
-
Financial models and pricing toolkits. Cost‑to‑serve frameworks, utilization levers, and value‑based pricing approaches that reflect the labor premium for certified practitioners and the capital costs of analytics tooling.
-
M&A and partnership playbooks. Due diligence checklists, integration risk matrices, and a prioritized list of capability gaps that are most accretive when addressed by acquisition or alliance in 2026.
-
Regulatory impact matrix. A translator that connects current and emerging enforcement patterns (standards and sector guidance) to operational controls and documentation practices that counsel should mandate prior to or during investigations.
-
Executive briefings and board materials. Ready‑to‑use slide packages that translate forensic risks into financial exposure, disclosure considerations, and remediation timelines suitable for C‑suite and board audiences.
Competitive landscape — what the major players are doing
The market combines global, multi‑disciplinary advisory houses with specialized regional and boutique forensic firms. Leading global firms are leveraging scale and cross‑service integration to deliver end‑to‑end investigative capabilities, while smaller firms compete on domain specialization, rapid responsiveness, and localized expert witness strength. Key players profiled in the study include a mix of large advisory brands and specialised forensic practices; each occupies a distinct strategic position in the value chain.
-
Crawford & Company: A global provider with broad service lines including litigation support and expert financial analysis. Their scale and loss‑adjusting heritage make them a go‑to for insurer‑led investigations and complex claims work.
-
Fiske & Company: A focused litigation‑support and forensic accounting practice that competes through deep technical expertise in fraud investigations and economic damages — a model that is highly attractive to law firms and claimants seeking specialized testimony.
-
Dean Dorton Allen Ford: Known for integrated fraud and risk assessment services, including whistleblower programs and SEC compliance consulting — a profile that aligns with corporate governance and regulatory remediation work.
-
Miller & Company LLP and Pribramsky & Co: Regional firms with strong local testimony pedigrees and practical strengths in dispute resolution and internal audit augmentation — they often win mandates where local legal knowledge and court acceptance are decisive.
-
Cg Team and Forensic Risk Alliance: Providers that blend litigation support with loss recovery and forensic accounting. Their agility makes them competitive for short‑cycle engagements.
-
Orrick, Herrington & Sutcliffe LLP and Alvarez & Marsal: Firms that combine forensic accounting with legal teams and restructuring capabilities, respectively. These integrated models are well suited to multi‑jurisdictional disputes and complex insolvency situations.
Recent market moves illustrate the strategic levers at play: major professional services firms are forming cybersecurity partnerships, launching advanced forensic analytics products, and acquiring boutique specialists to shore up niche capabilities. These developments accelerate consolidation in some parts of the market while raising the technical bar for boutique competitors.
Regulatory, labor, and standards context
-
Standards: The AICPA’s Statement on Standards for Forensic Services (SSFS) remains a central reference point for enforceable engagement standards. Compliance with these standards is increasingly a threshold requirement for admissibility and reputational resilience.
-
Compensation and labor market: CFEs and experienced forensic accountants command a measurable income premium versus general accounting peers; employers should expect higher base costs and plan retention incentives accordingly in 2026 hiring cycles.
-
Professional community and knowledge transfer: Industry forums and professional interest groups (including AICPA specialty areas and annual research conferences) are actively prioritizing AI integration, data privacy, and compliance program design — signaling the next wave of methodological updates that firms must adopt within advisory workflows.
Strategic imperatives for 2026
-
Invest in integrated analytics and secure data handling. Forensic engagements will increasingly hinge on the ability to process large, heterogeneous datasets while preserving evidentiary integrity and privacy — invest in secure analytics stacks and rigorous chain‑of‑custody protocols.
-
Design hybrid sourcing models. Combine in‑house capability for governance and rapid response with vetted external partners for specialty technical work and expert testimony. Our vendor heatmaps make this tactical sourcing executable.
-
Prioritize certification and career pathways. To contain labor cost escalation and talent churn, firms must create certification‑linked advancement tracks and billable pathways that capitalize on the market premium for specialized credentials.
-
Embed regulatory foresight into product design. Design services and engagement terms that anticipate admissibility standards and cross‑border evidence rules — this reduces rework and litigation risk.
-
Use M&A selectively to fill capability gaps. Where speed to market matters (e.g., cyber‑forensics, advanced analytics), targeted acquisitions or alliances will outperform organic build over the medium term.
How to use this report
Think of the study as a practical field guide and negotiation kit. It equips decision‑makers with market context to set 2026 budgets, shortlist partners, structure RFPs, and run post‑transaction integration for forensic capabilities. The study surfaces high‑confidence strategic options while intentionally withholding granular subsegment datapoints in this public summary — a design choice to protect the value of the full analysis and to steer practitioners toward the complete models, raw interview transcripts, and proprietary vendor scores contained in the report.
For executives preparing capital plans, counselers drafting engagement terms, or advisory firms sizing their next acquisition, the full PW Consulting Forensic Accounting Services Market study contains the granular inputs, scenario models, and implementation materials necessary to act decisively in 2026. Access to the full dataset and executable playbooks is available on our research portal.
For detailed analysis of this topic, please visit the official page: Forensic Accounting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Security Screening Market to Reach USD 14,350 Million by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-13
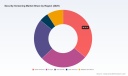
Security Screening Market 2026: Strategic Guide for Executive Decision‑Making
Executive summary
As security screening technologies move from point solutions to integrated, software‑defined systems, corporate and public sector procurement decisions in 2026 will determine not only near‑term compliance but also the architecture of risk mitigation for the next decade. PW Consulting’s new Security Screening Market study consolidates historical performance (2020–2025) with a forward‑looking forecast (2026–2032) to give decision makers an evidence‑based compass. The global market, having reached roughly USD 9.2 billion in 2025, is projected to expand to approximately USD 14.35 billion by 2032, reflecting a 6.8% compound annual growth rate over the forecast window. Market concentration remains meaningful (CR3 ~62%; CR5 ~65%), underscoring a competitive landscape where a small group of vendors shape technology roadmaps and procurement dynamics.
Security Screening Market
Why this matters for 2026 decisions
2026 is a hinge year. Organizations are balancing legacy fleets of scanners and detection equipment against emergent capabilities — AI‑augmented image analytics, consolidated explosive and biological detection, and an accelerating shift to tamper‑evident and compliance‑driven packaging. Decisions made this year will influence capital allocation, vendor relationships, and regulatory compliance for the next procurement cycle. Our study translates market momentum and regulatory pressure into tactical guidance so that CISOs, procurement leaders, and operations heads can prioritize investments that deliver durable risk reduction and measurable cost efficiency.
Security Screening Market
Market snapshot and trajectory
- Historical coverage: 2020–2025, establishing adoption patterns, replacement cycles, and procurement seasonality.
- Forecast window: 2026–2032, with a modeled CAGR of 6.8% to capture technology substitution, regulatory drivers, and macroeconomic effects.
- Competitive structure: Consolidated at the top, creating both barriers and strategic entry points for challengers and technology partners.
Key dynamics shaping the market
Our analysis identifies five forces that will dominate vendor selection and operational tradeoffs in 2026.
Security Screening Market
- Regulatory tightening and compliance complexity — Aviation and transborder screening standards (including ICAO STEB requirements) and jurisdictional Extended Producer Responsibility (EPR) schemes are reshaping packaging and screening specifications. Procurement teams must reconcile international standards with local EPR mandates for packaging content and recyclability.
- Technology convergence — AI‑enabled image analytics, multi‑sensing detection, and non‑intrusive inspection technologies are converging into unified platforms. Vendors that provide modular, software‑upgradeable solutions enable lower lifecycle costs and faster field upgrades.
- Operational economics — Total cost of ownership (TCO) is shifting the calculus from unit price to uptime, false alarm rates, throughput, and staff training requirements. Systems that reduce manual interventions and provide robust remote diagnostics materially impact operational margins.
- Supply chain and materials pressure — Material choices for compliant tamper‑evident packaging (LDPE/PEVA/TPU/PVC) and global sourcing disruptions affect both equipment manufacturers and downstream users such as airports and logistics providers.
- Procurement patterns and market concentration — With a top‑heavy vendor landscape, contract length, service level agreements, and interoperability commitments are strategic levers for buyers to extract value while managing vendor risk.
Strategic implications for buyers and vendors
Below are distilled actions derived from quantitative scenarios and vendor capability assessments in the study — intentionally framed at the strategic level to inform executive conversations in 2026.
- Buyers: move from replacement to platform thinking. Prioritize systems with modular upgrade pathways and open APIs so that AI and sensing upgrades can be implemented without full hardware replacement.
- Buyers: adopt outcome‑based contracting. Shift portions of vendor payment to agreed performance metrics (throughput, false alarm rate, lifecycle availability) to align incentives and manage capital exposure.
- Vendors: invest in software and service playbooks. Hardware margins are compressing; vendors that can monetize analytics, predictive maintenance, and regulatory compliance services will sustain growth.
- Both: institutionalize regulatory foresight. Embed a regulatory monitoring cadence into procurement and product roadmaps to adapt to regional EPR policies and aviation security updates.
- Risk managers: scenario plan for supply disruptions. Maintain dual sourcing strategies for critical components and plan inventory buffers tied to replacement lead times.
What our report delivers (practical, operational modules)
PWC’s Security Screening Market report is constructed for action. The deliverables include:
- Decision frameworks for vendor short‑listing and scorecard templates that weight TCO, upgradeability, and compliance capability.
- Procurement playbooks — model RFP language, SLA clauses, and outcome‑based contracting templates tailored to aviation, border, and critical infrastructure buyers.
- Technology roadmaps mapping legacy equipment replacement cycles to upgrade paths for AI analytics, multi‑modal sensing, and cloud‑enabled fleet management.
- Scenario‑based financial models — stress tested across adoption curves, regulatory shocks, and supply chain disruptions to quantify investment tradeoffs.
- Regulatory checklists and STEB packaging guidance — practical compliance steps tied to international and jurisdictional standards.
Competitive landscape — who matters and why
The market’s leading firms combine deep domain expertise, broad installed bases, and active product and partnership strategies. Our competitive chapter provides qualitative benchmarking and strategic positioning (we intentionally omit proprietary segment share tables here to preserve the value of the full report).
- Established systems integrators and OEMs — Companies with well‑known lines of X‑ray and non‑intrusive inspection products continue to leverage scale, global service networks, and certification histories to win major tenders. Their strength lies in lifecycle support and certification trust; their challenge is swift software innovation.
- Specialist detection and imaging firms — Vendors focused on high‑energy X‑ray, thermal imaging, or explosives detection are pushing into adjacent markets (ports, borders, cargo) through modular solutions and targeted demonstrations.
- Packaging and security‑seal manufacturers — Providers of tamper‑evident bags and secure packaging are gaining strategic importance as regulations mandate certified packaging for aviation and international logistics.
Notable recent developments that underscore market momentum:
- A leading U.S. systems company announced multi‑order wins for cargo and vehicle inspection, illustrating continued public‑sector demand for non‑intrusive inspection solutions.
- A European detection specialist launched an AI integration partnership to enhance threat detection accuracy across an established X‑ray product line — signaling acceleration in AI adoption.
- A North American packaging supplier received a sizable investment to expand U.S. capacity, reflecting structural demand for compliant tamper‑evident packaging.
- Trade show demonstrations by a high‑energy X‑ray vendor showcased miniaturized systems optimized for ports and border screening, pointing to evolving product form factors.
How to use this research in your 2026 planning cycle
Make the report the operational nucleus for three cross‑functional initiatives:
- Capital planning — Use our TCO scenarios to stage capital expenditures across short, medium, and long horizons and to set refresh budgets tied to performance thresholds.
- Vendor governance — Implement the vendor scorecard and SLA playbooks to renegotiate support terms and to create structured upgrade pathways with preferred suppliers.
- Compliance and operational readiness — Adopt the regulatory checklist and STEB guidance to align operations with global and local standards while minimizing throughput disruption.
Risk and sensitivity considerations
Key sensitivities in our models include regulatory tightening on packaging and screening procedures, rapid advances in AI that change false alarm economics, and geopolitical or supply chain shocks that affect lead times for core components. The report includes sensitivity tables and Monte Carlo scenario outputs so decision makers can quantify upside and downside risk to investment plans.
Conclusion — the strategic choice for 2026
For executives facing constrained budgets and expanding security obligations, the central strategic choice is clear: invest selectively in platform architectures that allow incremental capability upgrades while contracting for outcomes that tie vendor economics to operational performance. PW Consulting’s Security Screening Market study provides the frameworks, models, and vendor intelligence to operationalize that choice. The executive summary above is a concise map of the guidance contained in the full report; the complete dataset and actionable templates are available on our publication page for teams ready to turn 2026 decisions into durable advantage.
For detailed analysis of this topic, please visit the official page: Security Screening Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Whole Slide Scanner Market to Reach USD 297.5 Million by 2032 at 4.9% CAGR
By pmarketresearch, 2026-07-13
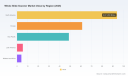
Whole Slide Scanner Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concise but high-impact orientation to our new Whole Slide Scanner Market study — the strategic briefing designed to inform leadership decisions throughout 2026. The market for whole slide scanners is no longer a niche lab capability; it is a foundational platform for modern pathology, clinical workflows and AI-enabled diagnostics. Our analysis shows the market expanding steadily from a 2025 baseline into the next decade at a compound annual growth rate of approximately 4.9%, reflecting gradual but persistent adoption across clinical and research settings and a clear pathway to broader enterprise deployment by 2032.
Whole Slide Scanner Market
Why this research matters for 2026
-
Investors: Understand where volume, regulatory approval and product differentiation converge to create scalable value — and which capabilities command premium multiples as digital pathology becomes standard of care.
Whole Slide Scanner Market -
Vendors: Prioritize R&D, regulatory strategy and channel approaches that convert technical advantage into market share while avoiding commoditization pressures.
Whole Slide Scanner Market -
Healthcare providers and laboratories: Create procurement roadmaps that align capital spending with realistic adoption timelines, workflow ROI and downstream AI-enabled service opportunities.
-
M&A and corporate development teams: Identify targets whose modular technologies, partnerships or regulatory clearances accelerate enterprise deployments.
This report is designed specifically to shorten the time between insight and action. It provides the market architecture, validated growth assumptions and practical tools buyers and suppliers need to shape competitive positioning or procurement decisions in 2026.
What the report delivers — practical, actionable content
-
Executive synthesis: One-page decision memos tailored for CEOs, CTOs and Heads of Pathology summarizing strategic options and risk vectors.
-
Market sizing & forecast: A transparent methodology and multi-year projections anchored on the 2025 baseline and forward CAGR — used to stress-test investment scenarios and budget planning.
-
Technology & product assessment: Comparative frameworks for throughput, image fidelity, fluorescence vs. brightfield workflows, AI-readiness and data output formats.
-
Vendor scorecards & procurement playbooks: Standardized evaluation criteria, vendor negotiation checklists and implementation timelines that reduce deployment risk.
-
Regulatory & reimbursement matrix: Practical guidance for navigating FDA 510(k) pathways, CE‑IVD requirements and CPT coding impacts on project economics.
-
Operational ROI tools: Templates to model labor, throughput and downstream analytics revenue implications under varied adoption curves.
-
Scenario planning: Three credible adoption trajectories (conservative, base-case, accelerated) and recommended strategic moves for each.
To preserve the strategic value of this preview (and in line with our “trailer” principle), detailed segment-level financials and regional splits are reserved for the full report. The deliverables above, however, are designed so that executive teams can begin prioritizing investment and vendor selection immediately.
Market dynamics and implications for strategy
-
Adoption drivers: Persistent capacity pressures in pathology labs, consolidation of reference networks, and the emergence of AI algorithms that rely on standardized, high-quality whole slide images are primary uptake forces. These structural drivers support steady market growth rather than sudden spikes.
-
Regulatory environment: For primary diagnostic use in surgical pathology, most systems must navigate the FDA 510(k) clearance pathway as Class II devices under product code QKQ. In the EU, CE‑IVD conformity remains a gating item for clinical deployments. These regulatory realities make product clearance and validated clinical workflows strategic priorities for vendors aiming at clinical volumes.
-
Reimbursement & economics: The scanner itself is typically not reimbursed as a standalone capital item; reimbursement for digitized workflows is commonly realized through pathology image analysis codes and bundled service models. This dynamic requires vendors and health systems to craft value propositions that emphasize throughput gains, labor arbitrage, and downstream revenue from AI-driven services.
-
Interoperability & formats: Support for enterprise imaging standards and efficient storage formats (including emerging preferences for configurable DICOM and modern compression schemes) materially affects total cost of ownership and integration risk for enterprise customers.
Competitive landscape — who matters and how they play
The market exhibits moderate concentration: the top tier of vendors captures a plurality of commercial activity, while a healthy long tail of niche and regional suppliers competes on price, form factor or specialty applications. Our analysis profiles leading players to clarify positioning and likely moves in 2026.
-
Hamamatsu Photonics (Hamamatsu, Japan) — Strength: clinical high-volume systems (NanoZoomer S360MD/S540). Strategic focus on throughput, reliability and integration into high-volume pathology networks where operational uptime drives purchasing decisions.
-
Leica Biosystems (Nussloch, Germany) — Strength: Clinical-grade scanners cleared for diagnostics (Aperio GT450 DX, GT Elite). Leica’s recent product refresh emphasizes AI-powered quality control and automated artifact detection — a differentiator for buyers seeking predictable, validated workflows.
-
3DHistech (Budapest, Hungary) — Strength: High-throughput and compact clinical-grade scanners (Pannoramic 1000, Scan II). Competitive on throughput per floor-foot and attractive to labs balancing capacity and space constraints.
-
Philips Healthcare (Eindhoven, Netherlands) — Strength: Enterprise-scale solutions and integrated pathology suites (SG300/SG60 and IntelliSite). Philips’ recent announcements on configurable output formats signal a push to simplify enterprise storage and PACS interoperability.
-
Roche Diagnostics (Basel, Switzerland) — Strength: Integration with diagnostic ecosystems and VENTANA scanners (DP 200/DP 600). Roche’s positioning is compelling for labs pursuing end-to-end, validated IVD pathways tied to companion diagnostics.
-
Motic Digital Pathology (San Francisco, USA) — Strength: Accessible clinical and research scanners (EasyScan, Infinity). Competes on price-to-performance for institutions that need clinical-grade digitization without enterprise footprints.
-
OptraSCAN (Toronto, Canada) — Strength: Cost-effective brightfield and fluorescence offerings. Attractive to budget-constrained labs and geographic markets where total cost of ownership is the pivotal procurement criterion.
-
Pramana / Evident (San Diego, USA) — Strength: Volumetric imaging with AI integration. Recent partnerships with major cancer centers highlight a route to clinical validation and advanced analytics-driven workflows.
-
Grundium (Netherlands) — Strength: Compact scanners for smaller labs and research environments. A contender where footprint and capital restraint drive purchasing decisions.
-
Huron TissueScope (Ontario, Canada) — Strength: High-resolution clinical scanners geared to diagnostic accuracy and serviceability in high-throughput clinical settings.
-
Mikroscan Technologies (California, USA) — Strength: Multi-resolution systems that serve mixed clinical/research needs and labs requiring flexible scanning parameters.
Recent market events underscore the competitive dynamics: product launches that embed AI quality control, new configurable output formats for enterprise interoperability, strategic partnerships with cancer centers, and regulatory clearances that unlock clinical use cases. Each of these moves raises the bar for competitors and shortens time-to-value for early adopters.
Strategic actions we recommend for 2026
-
Vendors should prioritize regulatory roadmaps and validated clinical partnerships: FDA 510(k) and CE‑IVD preparedness remain non-negotiable for meaningful clinical adoption.
-
Invest in AI that materially lowers operational risk (artifact detection, QC) rather than purely diagnostic claims — these features accelerate procurement approvals and reduce integration friction.
-
Buyers should run pilot deployments focused on workflow integration and total cost of ownership rather than unit price alone; prioritize systems that support modern image formats and enterprise imaging standards.
-
Investors and acquirers should target companies with validated clinical deployments, strategic partnerships with academic centers, or platform capabilities that can be vertically integrated into lab services.
-
All stakeholders must build interoperability and data governance into implementation plans to avoid downstream storage and AI training costs that can materially erode projected ROI.
How PW Consulting can accelerate your plan
Our full Whole Slide Scanner Market report includes the complete dataset, granular segment and regional analyses, vendor benchmarking matrices and customizable financial models. We pair that intelligence with hands-on advisory services: procurement templates, regulatory gap analyses, vendor due diligence, and implementation roadmaps keyed to your lab footprint and strategic objectives. If you are evaluating capital deployment, M&A targets, or a rollout of enterprise digital pathology in 2026, our team will tailor the forecasts and playbooks to your risk appetite and integration constraints.
To access the complete dataset, segment-level forecasts and vendor scorecards that underpin the strategic recommendations above, please consult the full PW Consulting report. The preview you have read is structured to give you the strategic context and prioritized actions needed for 2026 while reserving the detailed splits that power transactional decisions for subscribers.
For detailed analysis of this topic, please visit the official page: Whole Slide Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Packaging Market Outlook 2026-2032 — 4.5% CAGR, Asia-Pacific Dominates
By pmarketresearch, 2026-07-13
Packaging Market 2026: Strategic Preview for Executive Decision-Making
As global supply chains realign and sustainability regulations accelerate, 2026 will be a pivotal year for packaging executives shaping product portfolios, sourcing strategies, and M&A pipelines. PW Consulting’s latest Packaging Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro trajectories, regulatory inflection points, raw material dynamics, and competitive intent into an operationally oriented intelligence pack designed to inform board-level decisions and 12–36 month implementation plans.
Packaging Market
Market at a Glance — Direction, Scale, and Momentum
- Market scale and trajectory: The global packaging market, measured at the report’s base year (2025), sits at approximately USD 2.15 trillion (reporting in USD, revenue unit: Million). Our forecast path projects the market to expand at a compound annual growth rate (CAGR) of roughly 4.5% through 2032, reaching the low‑to‑mid USD 3.4 trillion range by the end of the forecast horizon.
- Recent volatility and recovery: Historical dynamics (2020–2025) show episodic contraction and rebound tied to raw material price swings and pandemic-related demand shifts. The forecast period assumes normalization of demand patterns, continued premiumization in certain end‑use categories, and a progressive shift toward higher-value (and higher-margin) sustainable solutions.
- Market structure: Concentration remains relatively low: the top three firms account for under one quarter of the market and the top five for roughly one quarter (CR3 ≈ 24.6%; CR5 ≈ 26.2%). This structural profile favors continued competitive intensity, niche specialization, and frequent cross-border M&A.
Why This Study Matters for 2026 Corporate Strategy
Executives entering 2026 face simultaneous pressures: tighter recycled-content rules, state and regional EPR (extended producer responsibility) rollouts, and raw material cost pass‑throughs. This study translates those pressures into decision-grade insights across four corporate imperatives:
Packaging Market
- Regulatory readiness: The report quantifies the compliance exposure of typical product portfolios under emerging frameworks (e.g., EU PPWR implementation timelines and US state-level EPR advances), and models cost-to-comply across alternative packaging architectures.
- Supply‑chain resilience: We map input-price sensitivity (pulp, containerboard, polymers, metals) to supplier concentration, inventory policies, and logistics bottlenecks, creating hedging playbooks that are actionable in procurement and treasury.
- Portfolio optimization: Using scenario-based profitability overlays, the study ranks packaging formats and technologies by risk-adjusted margin contribution across five strategic scenarios — useful for SKU rationalization and capex prioritization.
- M&A and partnership targeting: Given the dispersed market and steady mid-single-digit growth, inorganic growth remains a primary lever. Our screening identifies target archetypes and integration playbooks for both bolt-on and transformational transactions.
What’s Inside the Report — Practical, Executable Content
The study is deliberately tactical. Beyond headline market sizing, it contains:
Packaging Market
- Methodology appendix explaining base-year normalization (2025) and forecast assumptions for 2026–2032, including sensitivity tests tied to raw material price shocks and regulatory adoption timing.
- Segment-level scenario matrices (accessible in full report) that translate demand shifts into margin and cash‑flow implications without leaking competitive subsegment shares in this preview.
- Regulatory impact modeling: cost-to-comply calculators and a compliance roadmap for EU PPWR and major US state EPR laws, with timelines and enforcement risk assessments tailored to brand owners and CPG manufacturers.
- Procurement playbook: indexed supplier scorecards, contract clauses to manage pass-throughs, and a short-list of alternative feedstocks and material substitutions evaluated for technical and sustainability viability.
- Technology and automation ROI templates for packaging lines, including break‑even analyses for retrofit vs. greenfield automation investments.
- Commercial go-to-market guides: channel strategies for converting sustainability claims into price realization, retailer negotiation levers, and pilot frameworks for packaging-as-a-service pilots.
- Detailed competitor profiles and deal‑tracker (high‑level) for the largest technology and material suppliers, with strategic implications for partnerships and co‑innovation.
Competitive Landscape — Who’s Shaping 2026?
The market’s low concentration feeds vigorous strategic maneuvering. The report provides qualitative and actionable analysis of leading players and their likely plays in 2026:
- Amcor plc (HQ: Switzerland) — Amcor’s expanded portfolio (post-merger integrations and product innovation) positions it as a scale player in flexible and rigid formats. Strategic emphasis: modular closures and cost-performance closures designed to lower total system cost for large CPG customers. Watch for continued integration of acquired assets and program-level contracts that lock in multi-year volumes.
- Sealed Air Corporation (HQ: United States) — Focused on protective and food-safety packaging, Sealed Air is doubling down on automation and recycle-ready formats. Recent trade-show presence and product introductions signal a two‑track play: premium protective solutions for ecommerce and compliance-driven food packaging lines aimed at circularity targets.
- Smurfit Westrock (HQ: Ireland) — A leader in paper-based and corrugated solutions, Smurfit Westrock is leveraging recycled fiber and circular-economy narratives to win retailer shelf space. Their trade-show activity underscores investments in productivity and sustainable substrates that reduce scope‑3 exposure for customers.
- Sonoco Products Company (HQ: United States) — Sonoco’s breadth across paper, metal, and plastic gives it flexibility to hybridize solutions for customers seeking transitional pathways away from fossil-based plastics. Expect continued expansion in metal packaging and integrated end‑to‑end supply offerings.
- Huhtamaki Oyj (HQ: Finland) — A specialist in food‑on‑the‑go and mono-material solutions, Huhtamaki is positioned to capture convenience-led demand while meeting stricter recyclability criteria. Their investments in mono-material technologies make them a likely partner for fast-moving foodservice brands facing EPR obligations.
Recent market activity underscores these strategic directions: trade-show launches, product rollouts focused on recyclability and cost efficiency, and public-facing sustainability commitments. The EU PPWR and accelerating US EPR laws are not theoretical risks — they are shaping product roadmaps and go‑to‑market timing in real time.
Regulatory and Raw Material Dynamics — The Twin Speed Factors
Two sets of external variables will disproportionately influence 2026 outcomes:
- Regulations shaping demand and cost: The EU Packaging and Packaging Waste Regulation (PPWR) moved into force in early 2025 and becomes generally applicable in mid‑2026, introducing recycled-content targets and restrictions on certain formats. Meanwhile, US states (including California) are tightening reporting and EPR obligations with 2026 compliance milestones. These measures create asymmetric cost exposure across formats and geographies and will accelerate substitution where viable alternatives exist.
- Raw-material price pressure: Paper and containerboard prices resumed an upward trajectory in 2025, and producer-price indices for pulp and allied products remain volatile. These trends magnify the importance of procurement agility: near-term margin recovery hinges on contract design, captive recycling programs, and selective pass-through mechanisms with brand customers.
Strategic Playbook — Practical Moves for 2026
Based on the synthesis of macro trends, regulatory calendars, and competitor moves, PW Consulting recommends a prioritized, time‑bound playbook for 2026:
- Immediate (0–6 months): Conduct a regulatory exposure audit by SKU and jurisdiction; implement minimum viable compliance packaging changes for SKUs with the highest near‑term enforcement risk.
- Short term (6–18 months): Execute procurement hedges with indexed contracts and strategic peering with fiber and plastics recyclers; pursue pilot mono‑material conversions on high-velocity SKUs to reduce complexity and prepare for recyclability mandates.
- Medium term (18–36 months): Accelerate automation retrofits tied to labor and OEE gains; pursue bolt-on acquisitions that fill capability gaps in sustainable substrates or automated secondary packaging; commit to measurable scope‑3 reductions with validated third‑party metrics to secure retailer and investor trust.
- Commercial: Rework commercial agreements to enable sustainability investments (e.g., shared-cost CAPEX models) and enable premium capture for demonstrably lower lifecycle-impact packaging.
What This Preview Withholds — And Where to Find It
Consistent with our “trailer” approach, this article surfaces directionally the macro market sizing, growth trajectory, concentration metrics, competitive posture, and regulatory context that will drive boardroom decisions in 2026. To preserve the strategic value of the complete intelligence set — including granular segment economics, region-by-region demand curves, SKU-level margin simulations, and proprietary target lists — PW Consulting directs executives to the full report and accompanying datasets, which provide the numerical and model detail required for transaction diligence and operational planning.
Conclusion — Positioning for a Compliance‑and‑Innovation Economy
2026 is shaping up to be a year of consequential choices for packaging leaders: retrofit or replace, buy or build, standardize or customize. The market’s steady mid-single-digit growth masks substantial redistribution of value toward companies that can de‑risk supply chains, deliver verified circular solutions, and monetize sustainability through differentiated service models. PW Consulting’s Packaging Market 2026–2032 study is designed to translate those shifts into executable plans — from procurement and product development to M&A and commercial negotiation — so that executives can move rapidly from regulatory reaction to strategic advantage.
For the full data tables, scenario models, and company playbooks referenced here, access the complete report on the PW Consulting website — it contains the operative granularity required to convert insight into impact.
For detailed analysis of this topic, please visit the official page: Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Online Sports Betting Market to Reach USD 286.3M by 2032 at 9.85% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Online Sports Betting Market 2026: Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a high-level, decision-focused briefing that distills our latest Online Sports Betting Market study into the strategic imperatives CFOs, heads of product, and corporate development teams must act upon in 2026. This is a “trailer” of our full research: it reveals direction, dynamics, and implications you need to prioritize, while reserving the granular segmentation and sensitive numeric breakouts for the full report.
Online Sports Betting Market
Market Trajectory: What the Topline Means for Strategy
The online sports betting market has moved from a niche digital pastime to a mainstream consumer channel within a single business cycle. Measured on a consistent base-year basis, global revenue expanded steadily through the first half of the decade and reached an inflection by 2025. The market posted material growth between 2020 and 2025 and — under our central scenario — is set to continue expanding at a compound annual growth rate (CAGR) of roughly 9.85% over the 2026–2032 forecast window. By 2026 the market advances further from its 2025 base and continues a trajectory that, if uninterrupted by major regulatory shocks, roughly doubles market scale by the end of our forecast.
Online Sports Betting Market
Why the topline matters: a near-double market size within a single planning horizon changes the math of customer acquisition, technology investment, and regulatory engagement. Growth at this pace compresses the timeline for ROI on platform builds, makes scale economies achievable faster for vertically integrated operators, and shifts competitive advantage toward firms that combine regulatory footprint, brand reach, and real-time operational excellence.
Online Sports Betting Market
Strategic Implications for 2026 Corporate Decision-Making
- Prioritize architectural scalability now: At ~10% CAGR, platforms will be handling materially higher peak loads and concurrent live-event bets. Organizations should move from ad-hoc cloud solutions to architecture designs that balance latency, resilience, and compliance. Hybrid-cloud patterns and edge/local-zone deployments (used by leading operators) are becoming standard for live-betting latency SLAs and data residency requirements.
- Treat regulation as a product constraint and a growth lever: Recent regulatory resets — including new rulemaking directives from the U.S. regulatory apparatus in early 2026 — mean that legal frameworks will change in ways that affect product design, contract structures, and partnership models. Companies that embed regulatory scenario planning into product roadmaps will avoid costly rework and can turn compliance into a competitive moat through faster market entry.
- Optimize go-to-market via strategic partnerships: As brand and distribution remain decisive, strategic alliances with media, sports leagues, and retail channels accelerate user acquisition and deepen engagement. Partnership plays that bundle content, loyalty, and payment experiences outperform stand-alone customer-acquisition strategies.
- Monetize beyond the wager: Ecosystem monetization — through adjacent casino, prediction markets, and cross-sell into lotteries or fantasy products — materially increases lifetime value. The highest-performing operators are integrating multi-product “super app” architectures that keep users within a single commerce and loyalty layer.
- Embed responsible gaming and AML into front-line UX: Responsible gaming and anti-money-laundering tooling are now core product features, not compliance afterthoughts. Solutions that provide real-time risk signals and seamless remediation preserve trust and reduce regulatory friction.
Operational and Technology Imperatives
Operational excellence in 2026 requires three concurrent investments: infrastructure that meets latency and residency requirements; engineering practices that support continuous deployment across jurisdictions; and analytics capabilities that enable real-time margin management.
- Edge and local-zone deployment: Leading operators are using local cloud zones to meet strict data residency and latency needs for live betting. Enterprises planning national or multi-jurisdictional rollouts should evaluate local-zone and edge computing as part of their 18–36 month infrastructure roadmap.
- Hybrid cloud for compliance and portability: Hybrid solutions that leverage Azure Arc, Nutanix, and similar technologies provide a repeatable pattern for compliant multi-jurisdictional processing while reducing vendor lock-in.
- Real-time analytics and risk controls: Live in-play wagering magnifies exposure to both fraud and margin erosion. Investing in streaming analytics and automated limit-adjustment engines is now table stakes.
Competitive Landscape: Who’s Winning and Why
The market’s competitive structure shows moderate concentration: the top three operators account for a meaningful share of revenue and the five largest players capture a clear majority of consolidated market power. This mix creates both opportunity and pressure: scale matters, but differentiated propositions can still win share.
- DraftKings Inc. (Boston) — DraftKings continues to execute a vertically integrated playbook, blending sportsbook and adjacent product lines while leveraging media partnerships. Recent moves to expand a unified “super app” will put pressure on smaller operators to improve cross-product journeys.
- FanDuel / Flutter (New York) — FanDuel’s dual capability in daily fantasy and sportsbook, underpinned by Flutter’s capital and international muscle, keeps it at the center of U.S. regulated market competition.
- bet365 Group (UK) — bet365 remains a global benchmark for live betting features and product reliability. Its cross-jurisdictional operational playbook is a practical case study in regulatory and technical execution at scale.
- Entain and Flutter (UK / Global) — Both companies continue to leverage multi-brand portfolios to target diverse customer segments across regulated markets.
- U.S. casino-integrated operators (Caesars, MGM, Penn National) — Integration with retail gaming, loyalty, and hospitality assets yields unique cross-sell economics, especially in states with retail/online hybrid models.
- Specialists and challengers (PointsBet, others) — Niche propositions focused on product innovation (in-play mechanics, marketplace differentiation) can grow regionally and become attractive M&A targets for scale players looking to fill capability gaps.
Notable recent developments reflect evolving battlegrounds: exclusive media-provider partnerships, rollouts of enterprise-level fraud and geolocation tooling, and product expansions into unified gaming super apps. These moves accelerate winner-take-most dynamics in channels where distribution and engagement depth drive LTV/cost-of-acquisition economics.
Regulatory and Policy Context — What to Watch in 2026
Regulatory dynamics are the single largest source of upside and downside risk to 2026 plans. Key themes:
- Rulemaking momentum: A prominent U.S. regulatory authority reversed prior guidance and initiated fresh rulemaking in early 2026, signaling a period of legal clarification. Companies should assume a dynamic regulatory environment and build flexible compliance controls.
- Cross-border data policies: National-level data residency and cross-border transfer rules remain uneven. Operators adopting hybrid-compute and localized processing reduce execution risk and accelerate market entry.
- Responsible gaming expectations: Regulators and stakeholders expect proactive harm-minimization features. Operators that operationalize these expectations into product design will reduce enforcement risk and strengthen brand trust.
M&A, Partnerships, and Capital Allocation Guidance
With near-double growth projected over the planning horizon and meaningful concentration among incumbents, the M&A and partnership landscape is active and tactical. Key advisory points for 2026:
- Buy vs. build calculus: If your strategic imperative is rapid market entry or capability acquisition (e.g., live-betting engine, geolocation compliance suite, or a multi-product loyalty layer), acquisition of specialist assets can be materially faster than in-house development—provided integration plans are disciplined.
- Balance sheet and timing: Growth at this scale rewards front-loaded investment in customer acquisition and product differentiation. However, overpaying for scale without an operational plan to sustain margins is the single most common value-destroying path.
- Partnership archetypes: Content/distribution partnerships, regulated-market operating partnerships, and technology licensing models each solve different problems. Choose the archetype that aligns with your control requirements and time-to-market constraints.
What the Full PW Consulting Report Delivers
Our complete Online Sports Betting Market study is designed for practitioners making 12–36 month strategic bets. Highlights include:
- Integrated market sizing and forecast models (base year 2025) with scenario sensitivity for regulatory and macroeconomic shocks.
- Actionable go-to-market playbooks for market entry, product bundling, and loyalty-driven retention.
- Operational blueprints for technology, data residency, and live-event scaling, including vendor shortlists and cost-of-ownership frameworks.
- Detailed competitive profiles and M&A playbooks for both buyers and sellers—covering integration risks and capture opportunity timelines.
- Regulatory impact matrices and pre-approved contract language templates for key market-entry and partner arrangements.
- Scorecards and KPIs for real-time monitoring of operational risk, margin performance, and regulatory compliance.
Importantly, while this preview outlines the market’s macro growth and strategic themes, the full report contains the granular segmentation, regional and device-level insights, and model-ready spreadsheets necessary to operationalize these recommendations. Those datasets are intentionally withheld here to preserve the integrity and commercial value of the full research.
Final Recommendation: What to Do in Q2–Q4 2026
- Immediate action: complete a 90-day technical and regulatory readiness assessment focused on latency, data residency, and AML/responsible gaming controls.
- Six-month horizon: finalize partnership and media strategies that prioritize distribution reach and cross-product retention economics; begin selective integrations with cloud local-zone or edge providers where necessary.
- 12–36 months: allocate capital toward M&A or organic build programs that secure leadership in at least one high-return jurisdiction or product vertical, ensuring a defensible path to scale.
The online sports betting market in 2026 is at a strategic inflection: growth is robust, competitive stakes are higher, and regulatory complexity requires disciplined execution. For boards and executive teams, the question is not if the market will grow, but who will capture the economics of that growth. PW Consulting’s full Online Sports Betting Market report gives you the prioritized, executable intelligence to answer that question with confidence.
Access the Full Report
To obtain the detailed segmentation, model-ready forecasts, and the operational playbooks referenced here, please visit our full study page or contact your PW Consulting representative. The full report provides the data and tools your leadership team needs to convert 2026 market momentum into sustainable market leadership.
For detailed analysis of this topic, please visit the official page: Online Sports Betting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Active Magnetic Bearing Market to Reach US$395M by 2032 at 6.3% CAGR - PW Consulting
By pmarketresearch, 2026-07-13
Active Magnetic Bearing Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting presents a concise strategic preview of the Active Magnetic Bearing (AMB) market to orient executive choices in 2026. Our full study — built on a 2025 base year and a detailed 2020–2025 historical analysis — projects the AMB market to expand at a compound annual growth rate (CAGR) of approximately 6.3% over the 2026–2032 forecast window. Underpinning that trajectory is a clear shift from lubricant‑dependent rotary systems toward oil‑free, digitally monitored rotating equipment, creating discrete windows for technology investment, supply‑chain reconfiguration, and commercial playbooks.
Active Magnetic Bearing Market
Why this study matters for 2026 decisions
- Prioritize capital allocation with confidence: With the market moving from niche to mainstream applications, the report turns macro momentum into investment thresholds — helping leadership decide when to scale pilots into full product lines.
- Translate regulation into advantage: Energy‑efficiency and oil‑free operation mandates are no longer hypothetical. We map regulatory impact scenarios and quantify likely timing for accelerated procurement cycles across key end markets.
- De‑risk supply and manufacturing choices: Specialized polymers, advanced alloys and high‑precision labor are persistent cost drivers. The study outlines resilient sourcing strategies and factory footprint tradeoffs to protect margins under tightening labor and material conditions.
- Shape M&A and partnership strategy: The sector is consolidating around a handful of engineering‑intensive providers. Our competitive heatmaps and capability matrices identify the most complementary targets and alliance structures for rapid capability capture.
- Operationalize go‑to‑market moves: From retrofit economics to asset‑level remote monitoring services, our playbooks translate technical advantage into pricing, warranty and service offers that accelerate adoption.
What the report delivers — practical, decision‑grade outputs
- Top‑line market sizing and forward projections calibrated to macro drivers (2025 base and full 2026–2032 forecasts), enabling scenario planning across conservative, central and accelerated demand paths.
- Technology roadmaps that link controller architectures, sensor fidelity, materials selection and packaging (including sealed/canned options for harsh environments) to lifecycle cost and reliability tradeoffs.
- Supplier and cost models that break down bill‑of‑materials sensitivities (electronics, actuators, sensors, polymers, alloys), with stress tests for raw‑material shocks and regional labor cost differentials.
- Use‑case total cost of ownership (TCO) templates for compressors, turbines, motors and pumps — showing where AMB delivers payback through reduced lubrication, lower maintenance and service‑integrated uptime guarantees.
- Go‑to‑market playbooks for OEMs, system integrators and aftermarket suppliers: partner selection criteria, commercial structures, retrofit migration paths and pricing frameworks for subscription vs. capital sale models.
- Investment and M&A suitability matrices highlighting bolt‑on vs. transformational acquisition targets, with diligence checklists for IP, controller safety validation, and field‑performance datasets.
- Risk register and mitigation options covering regulatory, supply‑chain, and operational hazards — plus accelerant scenarios linked to carbon‑neutral policy adoption curves.
- Interactive executive dashboards (Excel + BI) for board briefings — enabling real‑time sensitivity testing of demand, price erosion and margin recovery strategies.
Competitive landscape — who matters and why (high‑level)
The competitive field blends specialist AMB pure‑plays, traditional bearing incumbents scaling their product lines, and large industrial OEMs embedding hybrid solutions. The study synthesizes vendor positioning across controller IP, actuator design, sensor systems, and integration services.
Active Magnetic Bearing Market
- SpinDrive Oy (Finland) — A pure‑play innovator whose Magma X800 controller and integrated AMB stacks have made it a visible partner for high‑speed turbo blowers, flywheels and oil‑free motors. SpinDrive’s strength is tight control‑system IP and rapid productization for high‑RPM niches.
- Waukesha Bearings (United States) — Focused on large turbomachinery and remote digital controls, Waukesha’s portfolio emphasizes high‑availability systems and field proven hardware. Recent product introductions targeting wind‑turbine shafts highlight an OEM‑service approach to reduce maintenance windows.
- MECOS AG (Switzerland) — A customization leader for precision rotating equipment, MECOS competes on close co‑engineering with compressor and blower OEMs; its advantage is bespoke system delivery for demanding industrial use cases.
- Calnetix Technologies (United States) — With offerings geared toward high‑speed motor‑generators, defense/aerospace, and energy‑storage flywheels, Calnetix pairs power‑dense machines with AMB controllers geared for mission‑critical uptime.
- Synchrony Inc. (United States) — Known for integrated thrust bearing systems and electronics, Synchrony plays in oil & gas and high‑speed compression where established OEM relationships and systems‑level warranties matter.
- SKF AB and Schaeffler Technologies (Europe) — Traditional bearing giants are expanding into magnetic bearings and AMB components. Their global manufacturing muscle and channel access enable rapid scaling once product maturity crosses required thresholds.
- Siemens AG (Germany) — As an OEM supplier, Siemens brings hybrid AMB strategies into industrial drives and energy‑efficient rotating equipment, leveraging system integration capabilities at scale.
Several notable market moves underscore strategic dynamics that will shape 2026 decisions: a strategic partnership announced to co‑deliver oil‑free motor systems; targeted product launches addressing wind main shafts; and new manufacturing capacity investments to serve rising global demand. These signals collectively point to an industry transitioning from bespoke projects to scalable product platforms — but with differentiated competitive moats driven by control IP and systems integration.
Active Magnetic Bearing Market
Supply‑chain and technical dynamics to watch
- Materials and manufacturing intensity: AMB systems require specialized polymers for insulation, advanced alloys for rotor/stator precision, and high‑tolerance machining. These inputs, coupled with skilled labor needs, create persistent upward pressure on unit costs unless mitigated by scale or regional cost arbitrage.
- Regulatory and policy tailwinds: Energy‑efficiency mandates, oil‑free operational requirements and carbon‑neutral commitments are accelerating procurement cycles in power generation, oil & gas, and industrial process sectors. Companies that can align product specs to compliance timelines will capture earlier adoption premiums.
- Application environment complexity: Offshore, subsea and corrosive‑fluid environments create requirements for canned/sealed designs and specialist materials — a differentiation axis that raises barrier to entry for generalist suppliers.
- Digital and service economics: Remote monitoring, predictive maintenance analytics and uptime‑backed service contracts convert AMB from a hardware sale to a service platform. Firms that integrate analytics and warranty engineering will capture a disproportionate share of aftermarket revenue.
Recommended strategic actions for 2026
- Immediate (0–12 months): Run pilot retrofits with clear TCO metrics in targeted plants; secure strategic supply agreements for critical polymers/alloys; set aside capex for controller validation and safety certification.
- Medium (12–24 months): Establish co‑development partnerships with controller specialists or sensor firms; evaluate regional manufacturing hubs to lower labor and logistics exposure; deploy remote monitoring pilots linked to SLAs.
- Longer term (24–48 months): Pursue bolt‑on acquisitions for control electronics or coatings tech to secure IP and margin; design modular AMB platforms for faster OEM integration; build aftermarket service teams to capture recurring revenue.
Concluding guidance
For executives making 2026 choices, the AMB market presents a classic technology‑transition opportunity: growing demand, rising policy support, and clear differentiation possible through control IP and integration capabilities. PW Consulting’s full report converts market momentum into executable programs — from procurement playbooks and supplier scorecards to M&A target shortlists and board‑ready scenario models. This preview highlights the high‑value directions; our complete study contains the granular segmentation, region‑ and application‑level datasets, and interactive models required to convert strategy into contract and production timelines.
To access the full dataset, segmentation breakdowns, and the decision‑grade tools referenced here, please visit our report page for subscription and licensing details.
For detailed analysis of this topic, please visit the official page: Active Magnetic Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
IR-Cut Filter Market to Reach USD 344.8 Million by 2032 — PW Consulting
By pmarketresearch, 2026-07-13
IR-Cut Filter Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As camera systems continue to permeate automotive, surveillance, industrial and consumer applications, the IR-cut filter market is entering a period of measured expansion. Using 2025 as the base year, our top-line modeling shows the global market growing from a mid-hundreds million USD base in 2025 along a compound annual growth rate (CAGR) of 5.67% through the forecast window to 2032. The trajectory reflects a combination of steady demand from established categories and sporadic, higher-growth pulses driven by regulatory change, camera feature refresh cycles, and technology substitution among filter types.
IR-Cut Filter Market
For executives planning 2026 budgets and strategic initiatives, this report distills the commercial implications of that trajectory: where to prioritize capacity, which technology bets carry asymmetric value, how pricing and procurement should adapt in a more volatile upstream environment, and what consolidation or partnership moves are likely to create scale advantage over the coming three- to five-year horizon.
IR-Cut Filter Market
Why this report matters now
2026 is a pivotal year for many stakeholders in the IR-cut filter value chain. The market is large enough to support multiple global leaders and regional specialists, but it remains concentrated enough—with the three-largest producers accounting for just over half of market sales—to make competitive moves meaningful. That concentration, combined with recent regulatory momentum in developed markets and material-cost volatility, creates both risk and opportunity.
IR-Cut Filter Market
Our research is intentionally positioned as a strategic “advance packet”: it demonstrates rigorous, data-driven analysis and scenario work to inform C-suite conversations while reserving the granular segmentation and proprietary model outputs for the full report. This enables procurement heads, product leaders, and corporate development teams to align quickly on priorities and next steps while preserving the incentive to access the detailed intelligence required for execution.
Key market dynamics shaping 2026 decisions
- Demand composition and pockets of acceleration. Long-term demand springs from camera deployment across automotive ADAS/vision systems, security and surveillance networks, consumer imaging, and industrial sensing. Growth is heterogeneous—some end-markets expand steadily, others are more cyclical or policy-driven—so strategic planning must be granular at the application level even if the headline growth appears stable.
- Supply-side concentration and strategic implications. Market concentration metrics show the top three suppliers capture just over half of global revenues, and the top five account for a modestly larger share. This configuration favors players who can combine technology differentiation (materials, coatings, assembly) with global supply reach; it also keeps margins susceptible to capacity shifts and competitive pricing in certain subsegments.
- Material cost volatility. Specialty optical glass and coating inputs experienced meaningful cost pressure in recent years—an illustrative spike of ~8.4% in 2023 tied to geopolitics and energy constraints, and price swings of up to ~12% across a two-year window. These swings directly affect product gross margins and favor suppliers with integrated upstream positions or long-term supply contracts.
- Regulatory tailwinds. Safety and surveillance mandates in principal markets have increased the end-market addressable base for camera-equipped systems. Regulatory upticks often produce lumpy demand—accelerated procurement cycles for automotive and public safety projects—so calendar-year planning must accommodate timing risk.
What the full report contains (practical, executable content)
- Top-line market model with annual historicals (2020–2025) and forward projections (2026–2032), including sensitivity scenarios tied to macro and regulatory shocks.
- Type- and application-level demand drivers (glass vs. plastic vs. hybrid approaches), with a discrete assessment of technology substitution risk and roadmap implications for camera module partners.
- Supply landscape and supplier scorecards: capacity footprints, technology specializations, customer concentration, and commercial posture—designed for quick vendor shortlisting.
- Cost-build and margin benchmarking that isolates the impact of raw-material inflation, coating complexity, and assembly tolerances on product economics.
- Regulatory and standards mapping with compliance checklists for major markets—critical for automotive OEMs and tier suppliers planning 2026 product launches.
- M&A and partnership playbooks with screened target archetypes, valuation heuristics, and integration risk checklists tailored to strategic acquirers and financial sponsors.
- Procurement and commercial levers: hedging strategies, contract templates for multi-year supply, and pricing playbooks for passing through raw-material moves without sacrificing volume.
- Scenario-based capacity planning tools and a stress-test framework to evaluate supplier resilience under raw-material shocks and demand surges.
Competitive landscape: profiles and strategic positioning
The competitive map spans specialty glass houses, regional optical manufacturers, and vertically integrated suppliers that combine filter manufacturing with module assembly. Below is a distilled view of the strategic postures of core players covered in our analysis:
- Zhejiang Crystal-Optech Co., Ltd. – A China-based specialist focused on end-to-end filter assemblies for digital cameras, smartphones, surveillance systems and automotive applications. Strengths: scale in low-cost manufacturing, deep OEM relationships in Asia, and fast product turnaround.
- Hubei Wufang Photoelectric Co., Ltd. – A diversified supplier with capabilities spanning consumer electronics, autonomous driving, and emerging metaverse optics. Strengths: nimble R&D tied to adjacent imaging trends and early traction in non-traditional camera applications.
- OPTRONTEC Inc. – Korea-based innovator producing absorptive and reflective IR-cut solutions, plus band-pass and film filters for image and 3D sensing. Strengths: technical differentiation in thin-film approaches and applicability in 3D sensing stacks.
- SCHOTT AG – German premium glass supplier offering high-performance NIR-cut glasses tailored to high-end mobile and professional imaging. Strengths: material science leadership, reputational cachet with premium device OEMs, and robust durability testing.
- AGC Inc. – Japanese glass and coating expert with NF Glass Filter offerings geared to visibility compensation in camera systems. Strengths: broad material portfolio and cross-industry scale.
- TAMA ELECTRONICS Co., Ltd. – Japanese manufacturer with advanced dicing services and absorption-type filter options. Strengths: manufacturing precision and parts integration for high-optical-performance applications.
- Hermosa Optics Inc. – Taiwan-based supplier focused on IR-cut and low-pass filter (LPF) solutions for optical instruments. Strengths: regional manufacturing agility and tailored optics for instrumentation.
- Suzhou Qimeng Crystal Material Co., Ltd. – Chinese producer of a broad optical product set including OLPF, IR-cut and UV filters. Strengths: diversified product portfolio and responsiveness to local OEM demand.
Recent market activity underlines two themes: (1) product refinement by established camera OEMs—e.g., a high-profile optical update and replacement program announced by a major camera manufacturer in mid-2025—and (2) continuous catalog and specification updates by specialty optical houses. These moves highlight the importance of both product reliability and after-sales support in customer selection criteria.
Implications for 2026 strategy
For executives deciding resource allocation in 2026, the following imperatives emerge from our analysis:
- De-risk supply by design. Formalize multi-sourcing strategies, pursue selective vertical integration for strategic materials, and include force majeure and price adjustment clauses triggered by raw-material indices.
- Prioritize technology differentials that matter to customers. Invest in coatings and hybrid-film approaches where optical performance materially improves end-product differentiation (color fidelity, low-light behavior, NIR rejection) and commandable pricing.
- Embed regulatory monitoring into product pipelines. Anticipate procurement waves caused by safety mandates and time product certifications to coincide with regulatory windows to capture incremental demand.
- Adopt opportunistic consolidation or alliances. Given the moderate concentration of the market, well-timed bolt-on acquisitions or strategic partnerships can accelerate capability stacks (e.g., coating technology, dicing services) and shorten product cycles.
- Operationalize margin protection. Use forward purchase agreements, index-linked pricing, and modular product architectures to preserve margin in the face of raw-material swings.
How to use the full report
This article provides a strategic orientation and highlights the levers that will matter most in 2026. The full IR-Cut Filter Market report from PW Consulting contains the granular segmentation, the transparent modelling workbook, and the supplier scorecards required to turn these insights into executable plans—whether you are optimizing procurement, sizing manufacturing investments, launching a differentiated filter product, or screening acquisition targets.
Access to the full dataset and modeling tools will allow your team to: run company-specific scenarios, extract region/application-level demand curves, test pricing sensitivities, and generate board-ready slides for capital allocation and M&A committees—capabilities we recommend deploying promptly to set 2026 priorities with confidence.
For detailed analysis of this topic, please visit the official page: IR-Cut Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com