

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Whole Slide Scanner Market to Reach USD 297.5 Million by 2032 at 4.9% CAGR

Whole Slide Scanner Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concise but high-impact orientation to our new Whole Slide Scanner Market study — the strategic briefing designed to inform leadership decisions throughout 2026. The market for whole slide scanners is no longer a niche lab capability; it is a foundational platform for modern pathology, clinical workflows and AI-enabled diagnostics. Our analysis shows the market expanding steadily from a 2025 baseline into the next decade at a compound annual growth rate of approximately 4.9%, reflecting gradual but persistent adoption across clinical and research settings and a clear pathway to broader enterprise deployment by 2032.
Whole Slide Scanner Market
Why this research matters for 2026
-
Investors: Understand where volume, regulatory approval and product differentiation converge to create scalable value — and which capabilities command premium multiples as digital pathology becomes standard of care.
Whole Slide Scanner Market -
Vendors: Prioritize R&D, regulatory strategy and channel approaches that convert technical advantage into market share while avoiding commoditization pressures.
Whole Slide Scanner Market -
Healthcare providers and laboratories: Create procurement roadmaps that align capital spending with realistic adoption timelines, workflow ROI and downstream AI-enabled service opportunities.
-
M&A and corporate development teams: Identify targets whose modular technologies, partnerships or regulatory clearances accelerate enterprise deployments.
This report is designed specifically to shorten the time between insight and action. It provides the market architecture, validated growth assumptions and practical tools buyers and suppliers need to shape competitive positioning or procurement decisions in 2026.
What the report delivers — practical, actionable content
-
Executive synthesis: One-page decision memos tailored for CEOs, CTOs and Heads of Pathology summarizing strategic options and risk vectors.
-
Market sizing & forecast: A transparent methodology and multi-year projections anchored on the 2025 baseline and forward CAGR — used to stress-test investment scenarios and budget planning.
-
Technology & product assessment: Comparative frameworks for throughput, image fidelity, fluorescence vs. brightfield workflows, AI-readiness and data output formats.
-
Vendor scorecards & procurement playbooks: Standardized evaluation criteria, vendor negotiation checklists and implementation timelines that reduce deployment risk.
-
Regulatory & reimbursement matrix: Practical guidance for navigating FDA 510(k) pathways, CE‑IVD requirements and CPT coding impacts on project economics.
-
Operational ROI tools: Templates to model labor, throughput and downstream analytics revenue implications under varied adoption curves.
-
Scenario planning: Three credible adoption trajectories (conservative, base-case, accelerated) and recommended strategic moves for each.
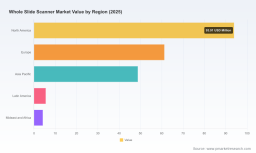
To preserve the strategic value of this preview (and in line with our “trailer” principle), detailed segment-level financials and regional splits are reserved for the full report. The deliverables above, however, are designed so that executive teams can begin prioritizing investment and vendor selection immediately.
Market dynamics and implications for strategy
-
Adoption drivers: Persistent capacity pressures in pathology labs, consolidation of reference networks, and the emergence of AI algorithms that rely on standardized, high-quality whole slide images are primary uptake forces. These structural drivers support steady market growth rather than sudden spikes.
-
Regulatory environment: For primary diagnostic use in surgical pathology, most systems must navigate the FDA 510(k) clearance pathway as Class II devices under product code QKQ. In the EU, CE‑IVD conformity remains a gating item for clinical deployments. These regulatory realities make product clearance and validated clinical workflows strategic priorities for vendors aiming at clinical volumes.
-
Reimbursement & economics: The scanner itself is typically not reimbursed as a standalone capital item; reimbursement for digitized workflows is commonly realized through pathology image analysis codes and bundled service models. This dynamic requires vendors and health systems to craft value propositions that emphasize throughput gains, labor arbitrage, and downstream revenue from AI-driven services.
-
Interoperability & formats: Support for enterprise imaging standards and efficient storage formats (including emerging preferences for configurable DICOM and modern compression schemes) materially affects total cost of ownership and integration risk for enterprise customers.
Competitive landscape — who matters and how they play
The market exhibits moderate concentration: the top tier of vendors captures a plurality of commercial activity, while a healthy long tail of niche and regional suppliers competes on price, form factor or specialty applications. Our analysis profiles leading players to clarify positioning and likely moves in 2026.
-
Hamamatsu Photonics (Hamamatsu, Japan) — Strength: clinical high-volume systems (NanoZoomer S360MD/S540). Strategic focus on throughput, reliability and integration into high-volume pathology networks where operational uptime drives purchasing decisions.
-
Leica Biosystems (Nussloch, Germany) — Strength: Clinical-grade scanners cleared for diagnostics (Aperio GT450 DX, GT Elite). Leica’s recent product refresh emphasizes AI-powered quality control and automated artifact detection — a differentiator for buyers seeking predictable, validated workflows.
-
3DHistech (Budapest, Hungary) — Strength: High-throughput and compact clinical-grade scanners (Pannoramic 1000, Scan II). Competitive on throughput per floor-foot and attractive to labs balancing capacity and space constraints.
-
Philips Healthcare (Eindhoven, Netherlands) — Strength: Enterprise-scale solutions and integrated pathology suites (SG300/SG60 and IntelliSite). Philips’ recent announcements on configurable output formats signal a push to simplify enterprise storage and PACS interoperability.
-
Roche Diagnostics (Basel, Switzerland) — Strength: Integration with diagnostic ecosystems and VENTANA scanners (DP 200/DP 600). Roche’s positioning is compelling for labs pursuing end-to-end, validated IVD pathways tied to companion diagnostics.
-
Motic Digital Pathology (San Francisco, USA) — Strength: Accessible clinical and research scanners (EasyScan, Infinity). Competes on price-to-performance for institutions that need clinical-grade digitization without enterprise footprints.
-
OptraSCAN (Toronto, Canada) — Strength: Cost-effective brightfield and fluorescence offerings. Attractive to budget-constrained labs and geographic markets where total cost of ownership is the pivotal procurement criterion.
-
Pramana / Evident (San Diego, USA) — Strength: Volumetric imaging with AI integration. Recent partnerships with major cancer centers highlight a route to clinical validation and advanced analytics-driven workflows.
-
Grundium (Netherlands) — Strength: Compact scanners for smaller labs and research environments. A contender where footprint and capital restraint drive purchasing decisions.
-
Huron TissueScope (Ontario, Canada) — Strength: High-resolution clinical scanners geared to diagnostic accuracy and serviceability in high-throughput clinical settings.
-
Mikroscan Technologies (California, USA) — Strength: Multi-resolution systems that serve mixed clinical/research needs and labs requiring flexible scanning parameters.
Recent market events underscore the competitive dynamics: product launches that embed AI quality control, new configurable output formats for enterprise interoperability, strategic partnerships with cancer centers, and regulatory clearances that unlock clinical use cases. Each of these moves raises the bar for competitors and shortens time-to-value for early adopters.
Strategic actions we recommend for 2026
-
Vendors should prioritize regulatory roadmaps and validated clinical partnerships: FDA 510(k) and CE‑IVD preparedness remain non-negotiable for meaningful clinical adoption.
-
Invest in AI that materially lowers operational risk (artifact detection, QC) rather than purely diagnostic claims — these features accelerate procurement approvals and reduce integration friction.
-
Buyers should run pilot deployments focused on workflow integration and total cost of ownership rather than unit price alone; prioritize systems that support modern image formats and enterprise imaging standards.
-
Investors and acquirers should target companies with validated clinical deployments, strategic partnerships with academic centers, or platform capabilities that can be vertically integrated into lab services.
-
All stakeholders must build interoperability and data governance into implementation plans to avoid downstream storage and AI training costs that can materially erode projected ROI.
How PW Consulting can accelerate your plan
Our full Whole Slide Scanner Market report includes the complete dataset, granular segment and regional analyses, vendor benchmarking matrices and customizable financial models. We pair that intelligence with hands-on advisory services: procurement templates, regulatory gap analyses, vendor due diligence, and implementation roadmaps keyed to your lab footprint and strategic objectives. If you are evaluating capital deployment, M&A targets, or a rollout of enterprise digital pathology in 2026, our team will tailor the forecasts and playbooks to your risk appetite and integration constraints.
To access the complete dataset, segment-level forecasts and vendor scorecards that underpin the strategic recommendations above, please consult the full PW Consulting report. The preview you have read is structured to give you the strategic context and prioritized actions needed for 2026 while reserving the detailed splits that power transactional decisions for subscribers.
For detailed analysis of this topic, please visit the official page: Whole Slide Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com