

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Security Screening Market to Reach USD 14,350 Million by 2032 at 6.8% CAGR

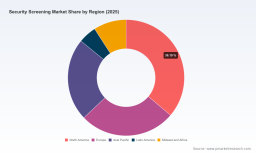
Security Screening Market 2026: Strategic Guide for Executive Decision‑Making
Executive summary
As security screening technologies move from point solutions to integrated, software‑defined systems, corporate and public sector procurement decisions in 2026 will determine not only near‑term compliance but also the architecture of risk mitigation for the next decade. PW Consulting’s new Security Screening Market study consolidates historical performance (2020–2025) with a forward‑looking forecast (2026–2032) to give decision makers an evidence‑based compass. The global market, having reached roughly USD 9.2 billion in 2025, is projected to expand to approximately USD 14.35 billion by 2032, reflecting a 6.8% compound annual growth rate over the forecast window. Market concentration remains meaningful (CR3 ~62%; CR5 ~65%), underscoring a competitive landscape where a small group of vendors shape technology roadmaps and procurement dynamics.
Security Screening Market
Why this matters for 2026 decisions
2026 is a hinge year. Organizations are balancing legacy fleets of scanners and detection equipment against emergent capabilities — AI‑augmented image analytics, consolidated explosive and biological detection, and an accelerating shift to tamper‑evident and compliance‑driven packaging. Decisions made this year will influence capital allocation, vendor relationships, and regulatory compliance for the next procurement cycle. Our study translates market momentum and regulatory pressure into tactical guidance so that CISOs, procurement leaders, and operations heads can prioritize investments that deliver durable risk reduction and measurable cost efficiency.
Security Screening Market
Market snapshot and trajectory
- Historical coverage: 2020–2025, establishing adoption patterns, replacement cycles, and procurement seasonality.
- Forecast window: 2026–2032, with a modeled CAGR of 6.8% to capture technology substitution, regulatory drivers, and macroeconomic effects.
- Competitive structure: Consolidated at the top, creating both barriers and strategic entry points for challengers and technology partners.
Key dynamics shaping the market
Our analysis identifies five forces that will dominate vendor selection and operational tradeoffs in 2026.
Security Screening Market
- Regulatory tightening and compliance complexity — Aviation and transborder screening standards (including ICAO STEB requirements) and jurisdictional Extended Producer Responsibility (EPR) schemes are reshaping packaging and screening specifications. Procurement teams must reconcile international standards with local EPR mandates for packaging content and recyclability.
- Technology convergence — AI‑enabled image analytics, multi‑sensing detection, and non‑intrusive inspection technologies are converging into unified platforms. Vendors that provide modular, software‑upgradeable solutions enable lower lifecycle costs and faster field upgrades.
- Operational economics — Total cost of ownership (TCO) is shifting the calculus from unit price to uptime, false alarm rates, throughput, and staff training requirements. Systems that reduce manual interventions and provide robust remote diagnostics materially impact operational margins.
- Supply chain and materials pressure — Material choices for compliant tamper‑evident packaging (LDPE/PEVA/TPU/PVC) and global sourcing disruptions affect both equipment manufacturers and downstream users such as airports and logistics providers.
- Procurement patterns and market concentration — With a top‑heavy vendor landscape, contract length, service level agreements, and interoperability commitments are strategic levers for buyers to extract value while managing vendor risk.
Strategic implications for buyers and vendors
Below are distilled actions derived from quantitative scenarios and vendor capability assessments in the study — intentionally framed at the strategic level to inform executive conversations in 2026.
- Buyers: move from replacement to platform thinking. Prioritize systems with modular upgrade pathways and open APIs so that AI and sensing upgrades can be implemented without full hardware replacement.
- Buyers: adopt outcome‑based contracting. Shift portions of vendor payment to agreed performance metrics (throughput, false alarm rate, lifecycle availability) to align incentives and manage capital exposure.
- Vendors: invest in software and service playbooks. Hardware margins are compressing; vendors that can monetize analytics, predictive maintenance, and regulatory compliance services will sustain growth.
- Both: institutionalize regulatory foresight. Embed a regulatory monitoring cadence into procurement and product roadmaps to adapt to regional EPR policies and aviation security updates.
- Risk managers: scenario plan for supply disruptions. Maintain dual sourcing strategies for critical components and plan inventory buffers tied to replacement lead times.
What our report delivers (practical, operational modules)
PWC’s Security Screening Market report is constructed for action. The deliverables include:
- Decision frameworks for vendor short‑listing and scorecard templates that weight TCO, upgradeability, and compliance capability.
- Procurement playbooks — model RFP language, SLA clauses, and outcome‑based contracting templates tailored to aviation, border, and critical infrastructure buyers.
- Technology roadmaps mapping legacy equipment replacement cycles to upgrade paths for AI analytics, multi‑modal sensing, and cloud‑enabled fleet management.
- Scenario‑based financial models — stress tested across adoption curves, regulatory shocks, and supply chain disruptions to quantify investment tradeoffs.
- Regulatory checklists and STEB packaging guidance — practical compliance steps tied to international and jurisdictional standards.
Competitive landscape — who matters and why
The market’s leading firms combine deep domain expertise, broad installed bases, and active product and partnership strategies. Our competitive chapter provides qualitative benchmarking and strategic positioning (we intentionally omit proprietary segment share tables here to preserve the value of the full report).
- Established systems integrators and OEMs — Companies with well‑known lines of X‑ray and non‑intrusive inspection products continue to leverage scale, global service networks, and certification histories to win major tenders. Their strength lies in lifecycle support and certification trust; their challenge is swift software innovation.
- Specialist detection and imaging firms — Vendors focused on high‑energy X‑ray, thermal imaging, or explosives detection are pushing into adjacent markets (ports, borders, cargo) through modular solutions and targeted demonstrations.
- Packaging and security‑seal manufacturers — Providers of tamper‑evident bags and secure packaging are gaining strategic importance as regulations mandate certified packaging for aviation and international logistics.
Notable recent developments that underscore market momentum:
- A leading U.S. systems company announced multi‑order wins for cargo and vehicle inspection, illustrating continued public‑sector demand for non‑intrusive inspection solutions.
- A European detection specialist launched an AI integration partnership to enhance threat detection accuracy across an established X‑ray product line — signaling acceleration in AI adoption.
- A North American packaging supplier received a sizable investment to expand U.S. capacity, reflecting structural demand for compliant tamper‑evident packaging.
- Trade show demonstrations by a high‑energy X‑ray vendor showcased miniaturized systems optimized for ports and border screening, pointing to evolving product form factors.
How to use this research in your 2026 planning cycle
Make the report the operational nucleus for three cross‑functional initiatives:
- Capital planning — Use our TCO scenarios to stage capital expenditures across short, medium, and long horizons and to set refresh budgets tied to performance thresholds.
- Vendor governance — Implement the vendor scorecard and SLA playbooks to renegotiate support terms and to create structured upgrade pathways with preferred suppliers.
- Compliance and operational readiness — Adopt the regulatory checklist and STEB guidance to align operations with global and local standards while minimizing throughput disruption.
Risk and sensitivity considerations
Key sensitivities in our models include regulatory tightening on packaging and screening procedures, rapid advances in AI that change false alarm economics, and geopolitical or supply chain shocks that affect lead times for core components. The report includes sensitivity tables and Monte Carlo scenario outputs so decision makers can quantify upside and downside risk to investment plans.
Conclusion — the strategic choice for 2026
For executives facing constrained budgets and expanding security obligations, the central strategic choice is clear: invest selectively in platform architectures that allow incremental capability upgrades while contracting for outcomes that tie vendor economics to operational performance. PW Consulting’s Security Screening Market study provides the frameworks, models, and vendor intelligence to operationalize that choice. The executive summary above is a concise map of the guidance contained in the full report; the complete dataset and actionable templates are available on our publication page for teams ready to turn 2026 decisions into durable advantage.
For detailed analysis of this topic, please visit the official page: Security Screening Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com