

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Forensic Accounting Market to Hit USD 1,221 Million by 2032

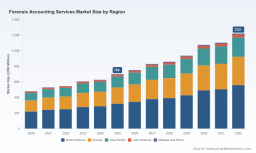
Forensic Accounting Services Market — Strategic Outlook for 2026 Decision‑Makers
As organizations recalibrate risk appetites and compliance frameworks for a new regulatory and technological era, forensic accounting has moved from a specialist discipline to a board‑level capability. PW Consulting’s upcoming Forensic Accounting Services Market study (base year 2025) offers a practical, decision‑grade compass for executives, in‑house counsel, risk officers, and advisory firms preparing strategic moves in 2026 and beyond. The market reached approximately USD 700 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.2% across the 2026–2032 forecast window — a trajectory that frames both near‑term investment priorities and medium‑term capability gaps for enterprises and service providers alike.
Forensic Accounting Services Market
Why this study matters for 2026
-
Convergence of risk vectors. Cyber breaches, complex financial crime, cross‑border litigation, and heightened regulatory scrutiny are converging into multi‑disciplinary investigations that demand integrated forensic accounting, digital forensics, and legal coordination. The market dynamics embedded in this study quantify that convergence and translate it into practical options for allocating spend, talent, and technology in 2026.
Forensic Accounting Services Market -
Capital allocation and M&A timing. With forensic accounting services growing at a mid‑single‑digit premium to adjacent professional services, the study provides the revenue and growth context that informs acquisition bench‑building, bolt‑on strategies, and greenfield investments — particularly where specialized boutiques or regional practices can fill capability gaps quickly.
Forensic Accounting Services Market -
Talent and cost management. Premiums for Certified Fraud Examiners (CFE) and experienced forensic accountants are measurable and persistent; the report translates labor cost inflation and certification premia into workforce planning scenarios, bill‑rate models, and retention playbooks suitable for 2026 budgeting cycles.
Core drivers shaping the market
-
Regulatory and standards pressure. Enforceable professional standards and sector guidance (including contemporary updates to the AICPA’s forensic services guidance) have raised baseline expectations for methodology, documentation, and expert testimony. Our analysis identifies which parts of the forensic workflow will be subject to the most immediate scrutiny and which controls companies should prioritize in 2026 to reduce legal and reputational exposure.
-
Technology and analytics. Forensic analytics tools — from anomaly detection engines to provenance tracing — are entering widespread commercial use. Large advisory firms and niche tool vendors are investing in integrated stacks. The net effect: faster evidence discovery cycles but higher vendor diligence requirements. The study maps the vendor taxonomy, capability tiers, and the practical tradeoffs between build, buy, and partner strategies.
-
Cyber‑forensics coupling. Recent strategic partnerships between major professional services firms and cybersecurity specialists underscore a structural shift: forensic accounting engagements increasingly require deep data security and incident response capabilities. We evaluate how firms can operationalize this coupling without creating duplication or compliance gaps.
-
Litigation intensity and alternative dispute mechanisms. Corporate restructurings, bankruptcy proceedings, and global arbitration trends have sustained demand for litigation support and expert testimony. The report models demand drivers for dispute‑related engagements and the commercial levers firms can use to capture that work.
What the report delivers — practical content for implementers
-
Comprehensive market sizing and growth scenarios. We present a base‑case market sizing for 2025 and model growth through 2032 under multiple adoption and regulatory scenarios to support capital planning.
-
Service and delivery playbooks. Usable templates for structuring fraud investigation, litigation support, risk assessment, and bankruptcy engagements — including team composition, evidence flows, and quality checkpoints.
-
Vendor and capability heatmaps. Benchmarks of global and regional providers across technical skills, digital forensics, expert witness track record, and pricing models — designed for rapid shortlist development and RFP issuance.
-
Financial models and pricing toolkits. Cost‑to‑serve frameworks, utilization levers, and value‑based pricing approaches that reflect the labor premium for certified practitioners and the capital costs of analytics tooling.
-
M&A and partnership playbooks. Due diligence checklists, integration risk matrices, and a prioritized list of capability gaps that are most accretive when addressed by acquisition or alliance in 2026.
-
Regulatory impact matrix. A translator that connects current and emerging enforcement patterns (standards and sector guidance) to operational controls and documentation practices that counsel should mandate prior to or during investigations.
-
Executive briefings and board materials. Ready‑to‑use slide packages that translate forensic risks into financial exposure, disclosure considerations, and remediation timelines suitable for C‑suite and board audiences.
Competitive landscape — what the major players are doing
The market combines global, multi‑disciplinary advisory houses with specialized regional and boutique forensic firms. Leading global firms are leveraging scale and cross‑service integration to deliver end‑to‑end investigative capabilities, while smaller firms compete on domain specialization, rapid responsiveness, and localized expert witness strength. Key players profiled in the study include a mix of large advisory brands and specialised forensic practices; each occupies a distinct strategic position in the value chain.
-
Crawford & Company: A global provider with broad service lines including litigation support and expert financial analysis. Their scale and loss‑adjusting heritage make them a go‑to for insurer‑led investigations and complex claims work.
-
Fiske & Company: A focused litigation‑support and forensic accounting practice that competes through deep technical expertise in fraud investigations and economic damages — a model that is highly attractive to law firms and claimants seeking specialized testimony.
-
Dean Dorton Allen Ford: Known for integrated fraud and risk assessment services, including whistleblower programs and SEC compliance consulting — a profile that aligns with corporate governance and regulatory remediation work.
-
Miller & Company LLP and Pribramsky & Co: Regional firms with strong local testimony pedigrees and practical strengths in dispute resolution and internal audit augmentation — they often win mandates where local legal knowledge and court acceptance are decisive.
-
Cg Team and Forensic Risk Alliance: Providers that blend litigation support with loss recovery and forensic accounting. Their agility makes them competitive for short‑cycle engagements.
-
Orrick, Herrington & Sutcliffe LLP and Alvarez & Marsal: Firms that combine forensic accounting with legal teams and restructuring capabilities, respectively. These integrated models are well suited to multi‑jurisdictional disputes and complex insolvency situations.
Recent market moves illustrate the strategic levers at play: major professional services firms are forming cybersecurity partnerships, launching advanced forensic analytics products, and acquiring boutique specialists to shore up niche capabilities. These developments accelerate consolidation in some parts of the market while raising the technical bar for boutique competitors.
Regulatory, labor, and standards context
-
Standards: The AICPA’s Statement on Standards for Forensic Services (SSFS) remains a central reference point for enforceable engagement standards. Compliance with these standards is increasingly a threshold requirement for admissibility and reputational resilience.
-
Compensation and labor market: CFEs and experienced forensic accountants command a measurable income premium versus general accounting peers; employers should expect higher base costs and plan retention incentives accordingly in 2026 hiring cycles.
-
Professional community and knowledge transfer: Industry forums and professional interest groups (including AICPA specialty areas and annual research conferences) are actively prioritizing AI integration, data privacy, and compliance program design — signaling the next wave of methodological updates that firms must adopt within advisory workflows.
Strategic imperatives for 2026
-
Invest in integrated analytics and secure data handling. Forensic engagements will increasingly hinge on the ability to process large, heterogeneous datasets while preserving evidentiary integrity and privacy — invest in secure analytics stacks and rigorous chain‑of‑custody protocols.
-
Design hybrid sourcing models. Combine in‑house capability for governance and rapid response with vetted external partners for specialty technical work and expert testimony. Our vendor heatmaps make this tactical sourcing executable.
-
Prioritize certification and career pathways. To contain labor cost escalation and talent churn, firms must create certification‑linked advancement tracks and billable pathways that capitalize on the market premium for specialized credentials.
-
Embed regulatory foresight into product design. Design services and engagement terms that anticipate admissibility standards and cross‑border evidence rules — this reduces rework and litigation risk.
-
Use M&A selectively to fill capability gaps. Where speed to market matters (e.g., cyber‑forensics, advanced analytics), targeted acquisitions or alliances will outperform organic build over the medium term.
How to use this report
Think of the study as a practical field guide and negotiation kit. It equips decision‑makers with market context to set 2026 budgets, shortlist partners, structure RFPs, and run post‑transaction integration for forensic capabilities. The study surfaces high‑confidence strategic options while intentionally withholding granular subsegment datapoints in this public summary — a design choice to protect the value of the full analysis and to steer practitioners toward the complete models, raw interview transcripts, and proprietary vendor scores contained in the report.
For executives preparing capital plans, counselers drafting engagement terms, or advisory firms sizing their next acquisition, the full PW Consulting Forensic Accounting Services Market study contains the granular inputs, scenario models, and implementation materials necessary to act decisively in 2026. Access to the full dataset and executable playbooks is available on our research portal.
For detailed analysis of this topic, please visit the official page: Forensic Accounting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com