

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
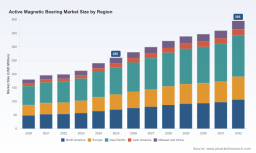
Active Magnetic Bearing Market to Reach US$395M by 2032 at 6.3% CAGR - PW Consulting

Active Magnetic Bearing Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting presents a concise strategic preview of the Active Magnetic Bearing (AMB) market to orient executive choices in 2026. Our full study — built on a 2025 base year and a detailed 2020–2025 historical analysis — projects the AMB market to expand at a compound annual growth rate (CAGR) of approximately 6.3% over the 2026–2032 forecast window. Underpinning that trajectory is a clear shift from lubricant‑dependent rotary systems toward oil‑free, digitally monitored rotating equipment, creating discrete windows for technology investment, supply‑chain reconfiguration, and commercial playbooks.
Active Magnetic Bearing Market
Why this study matters for 2026 decisions
- Prioritize capital allocation with confidence: With the market moving from niche to mainstream applications, the report turns macro momentum into investment thresholds — helping leadership decide when to scale pilots into full product lines.
- Translate regulation into advantage: Energy‑efficiency and oil‑free operation mandates are no longer hypothetical. We map regulatory impact scenarios and quantify likely timing for accelerated procurement cycles across key end markets.
- De‑risk supply and manufacturing choices: Specialized polymers, advanced alloys and high‑precision labor are persistent cost drivers. The study outlines resilient sourcing strategies and factory footprint tradeoffs to protect margins under tightening labor and material conditions.
- Shape M&A and partnership strategy: The sector is consolidating around a handful of engineering‑intensive providers. Our competitive heatmaps and capability matrices identify the most complementary targets and alliance structures for rapid capability capture.
- Operationalize go‑to‑market moves: From retrofit economics to asset‑level remote monitoring services, our playbooks translate technical advantage into pricing, warranty and service offers that accelerate adoption.
What the report delivers — practical, decision‑grade outputs
- Top‑line market sizing and forward projections calibrated to macro drivers (2025 base and full 2026–2032 forecasts), enabling scenario planning across conservative, central and accelerated demand paths.
- Technology roadmaps that link controller architectures, sensor fidelity, materials selection and packaging (including sealed/canned options for harsh environments) to lifecycle cost and reliability tradeoffs.
- Supplier and cost models that break down bill‑of‑materials sensitivities (electronics, actuators, sensors, polymers, alloys), with stress tests for raw‑material shocks and regional labor cost differentials.
- Use‑case total cost of ownership (TCO) templates for compressors, turbines, motors and pumps — showing where AMB delivers payback through reduced lubrication, lower maintenance and service‑integrated uptime guarantees.
- Go‑to‑market playbooks for OEMs, system integrators and aftermarket suppliers: partner selection criteria, commercial structures, retrofit migration paths and pricing frameworks for subscription vs. capital sale models.
- Investment and M&A suitability matrices highlighting bolt‑on vs. transformational acquisition targets, with diligence checklists for IP, controller safety validation, and field‑performance datasets.
- Risk register and mitigation options covering regulatory, supply‑chain, and operational hazards — plus accelerant scenarios linked to carbon‑neutral policy adoption curves.
- Interactive executive dashboards (Excel + BI) for board briefings — enabling real‑time sensitivity testing of demand, price erosion and margin recovery strategies.
Competitive landscape — who matters and why (high‑level)
The competitive field blends specialist AMB pure‑plays, traditional bearing incumbents scaling their product lines, and large industrial OEMs embedding hybrid solutions. The study synthesizes vendor positioning across controller IP, actuator design, sensor systems, and integration services.
Active Magnetic Bearing Market
- SpinDrive Oy (Finland) — A pure‑play innovator whose Magma X800 controller and integrated AMB stacks have made it a visible partner for high‑speed turbo blowers, flywheels and oil‑free motors. SpinDrive’s strength is tight control‑system IP and rapid productization for high‑RPM niches.
- Waukesha Bearings (United States) — Focused on large turbomachinery and remote digital controls, Waukesha’s portfolio emphasizes high‑availability systems and field proven hardware. Recent product introductions targeting wind‑turbine shafts highlight an OEM‑service approach to reduce maintenance windows.
- MECOS AG (Switzerland) — A customization leader for precision rotating equipment, MECOS competes on close co‑engineering with compressor and blower OEMs; its advantage is bespoke system delivery for demanding industrial use cases.
- Calnetix Technologies (United States) — With offerings geared toward high‑speed motor‑generators, defense/aerospace, and energy‑storage flywheels, Calnetix pairs power‑dense machines with AMB controllers geared for mission‑critical uptime.
- Synchrony Inc. (United States) — Known for integrated thrust bearing systems and electronics, Synchrony plays in oil & gas and high‑speed compression where established OEM relationships and systems‑level warranties matter.
- SKF AB and Schaeffler Technologies (Europe) — Traditional bearing giants are expanding into magnetic bearings and AMB components. Their global manufacturing muscle and channel access enable rapid scaling once product maturity crosses required thresholds.
- Siemens AG (Germany) — As an OEM supplier, Siemens brings hybrid AMB strategies into industrial drives and energy‑efficient rotating equipment, leveraging system integration capabilities at scale.
Several notable market moves underscore strategic dynamics that will shape 2026 decisions: a strategic partnership announced to co‑deliver oil‑free motor systems; targeted product launches addressing wind main shafts; and new manufacturing capacity investments to serve rising global demand. These signals collectively point to an industry transitioning from bespoke projects to scalable product platforms — but with differentiated competitive moats driven by control IP and systems integration.
Active Magnetic Bearing Market
Supply‑chain and technical dynamics to watch
- Materials and manufacturing intensity: AMB systems require specialized polymers for insulation, advanced alloys for rotor/stator precision, and high‑tolerance machining. These inputs, coupled with skilled labor needs, create persistent upward pressure on unit costs unless mitigated by scale or regional cost arbitrage.
- Regulatory and policy tailwinds: Energy‑efficiency mandates, oil‑free operational requirements and carbon‑neutral commitments are accelerating procurement cycles in power generation, oil & gas, and industrial process sectors. Companies that can align product specs to compliance timelines will capture earlier adoption premiums.
- Application environment complexity: Offshore, subsea and corrosive‑fluid environments create requirements for canned/sealed designs and specialist materials — a differentiation axis that raises barrier to entry for generalist suppliers.
- Digital and service economics: Remote monitoring, predictive maintenance analytics and uptime‑backed service contracts convert AMB from a hardware sale to a service platform. Firms that integrate analytics and warranty engineering will capture a disproportionate share of aftermarket revenue.
Recommended strategic actions for 2026
- Immediate (0–12 months): Run pilot retrofits with clear TCO metrics in targeted plants; secure strategic supply agreements for critical polymers/alloys; set aside capex for controller validation and safety certification.
- Medium (12–24 months): Establish co‑development partnerships with controller specialists or sensor firms; evaluate regional manufacturing hubs to lower labor and logistics exposure; deploy remote monitoring pilots linked to SLAs.
- Longer term (24–48 months): Pursue bolt‑on acquisitions for control electronics or coatings tech to secure IP and margin; design modular AMB platforms for faster OEM integration; build aftermarket service teams to capture recurring revenue.
Concluding guidance
For executives making 2026 choices, the AMB market presents a classic technology‑transition opportunity: growing demand, rising policy support, and clear differentiation possible through control IP and integration capabilities. PW Consulting’s full report converts market momentum into executable programs — from procurement playbooks and supplier scorecards to M&A target shortlists and board‑ready scenario models. This preview highlights the high‑value directions; our complete study contains the granular segmentation, region‑ and application‑level datasets, and interactive models required to convert strategy into contract and production timelines.
To access the full dataset, segmentation breakdowns, and the decision‑grade tools referenced here, please visit our report page for subscription and licensing details.
For detailed analysis of this topic, please visit the official page: Active Magnetic Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com