

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Transparent ABS Market to Reach USD 1,018.22M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-13
Transparent ABS Plastics Market — Strategic Intelligence for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, decision-focused briefing that frames our Transparent ABS Plastics Market research for executives preparing strategic moves in 2026. This briefing synthesizes the report’s core macro-trends and strategic implications while intentionally withholding granular sub‑segment tables and regional splits to encourage access to the full intelligence package.
Transparent ABS Plastics Market
Market trajectory: what the numbers tell senior leadership
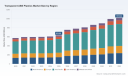
The transparent ABS market is entering a multi-year expansion phase. On a consolidated basis the industry moved from the mid‑hundreds of millions of USD in 2020 to a base year (2025) market size just above USD 630 million. Our forecast model, built from a combination of demand drivers, pricing scenarios and input-cost pass‑through mechanics, projects a compound annual growth rate (CAGR) of 5.5% over the 2026–2032 horizon. By the end of that period the market exceeds the USD 1 billion mark, creating an enlarged addressable opportunity for suppliers, converters and end‑users willing to act decisively in 2026.
Transparent ABS Plastics Market
Notably, the run‑up into 2026 contains an observable near‑term uplift: pricing effects and demand normalization combine to produce a pronounced step‑change early in the forecast. For executives this implies a 2026 planning year that differs materially from the prior five‑year trendline — planning assumptions should be updated accordingly.
Transparent ABS Plastics Market
Why this research matters for 2026 decisions
- Procurement and pass‑through mechanics. Volatile styrene feedstock costs and logistics disruptions are already driving supplier price actions. Our report quantifies the sensitivity of finished ABS prices to raw material swings and models pass‑through timelines across contractual types — essential for procurement teams renegotiating 2026 contracts.
- Product and portfolio prioritization. Transparent ABS is diversifying across high‑clarity applications (consumer electronics and medical) and utility applications (appliances and industrial components). The research shows where clarity, impact resistance, and scratch resistance generate premium value — guiding product roadmaps and premium‑tier launches in 2026.
- CapEx and footprint optimization. Given regional shifts in demand and feedstock supply dynamics, our scenarios help capital planners decide between brownfield debottlenecks, tolling arrangements, or near‑market compounding capacity.
- M&A and partnering playbook. The combination of meaningful market concentration among established suppliers and pockets of specialty opportunity creates a fertile environment for bolt‑on acquisitions and strategic alliances. The report surfaces acquisition archetypes and value capture pathways.
Report deliverables — what executives get
- Proven market sizing methodology and a downloadable model with adjustable assumptions (price, feedstock cost, demand elasticity, capacity additions).
- Three actionable 2026–2028 scenarios (Baseline, High‑Growth, Stress) with quantified P&L impacts for manufacturers, compounders and OEMs.
- Supplier scorecards and risk matrices evaluating technical capability, product breadth, geographic reach and contract flexibility.
- Value‑chain maps and cost‑to‑serve analytics that reconcile resin pricing to finished‑goods economics across molding and extrusion routes.
- Regulatory and sustainability playbook highlighting chemical recycling pathways, mechanical recycling constraints for transparent grades, and likely policy impacts through 2032.
- Commercial go‑to‑market playbooks for targeting high‑margin applications and converting specification wins into volume growth.
Competitive landscape — what tier‑one players signal for 2026
The transparent ABS arena is defined by a mix of global petrochemical majors and specialized resin producers. The competitive field combines large, integrated suppliers with strong distribution channels and regional specialists focused on specialty MABS or performance grades. Our synthesis of public profiles and commercial intelligence highlights several strategic takeaways:
- Integrated global suppliers (e.g., LG Chem, SABIC): These players leverage feedstock integration and broad application portfolios to defend share in appliance, automotive, and electronics channels. Their product stories emphasize processability and dimensional stability — attributes that increase switching costs for OEMs.
- Specialty and MABS leaders (e.g., INEOS Styrolution, Chi Mei, Denka, Lotte Chemical): These companies compete on optical clarity, high‑impact formulations and scratch/weather resistance. Their competitiveness in healthcare and premium consumer segments makes them preferred partners for product differentiation strategies.
- Regional European footholds (e.g., Trinseo): Localized supply and service, plus regional contract structures, create tactical advantages during short‑term raw material shocks and logistics constraints.
Recent supplier actions provide practical signals for 2026 planning: Trinseo implemented a Europe‑focused list price increase in March 2026, and US producers lifted ABS prices in January 2026 following a surge in styrene costs and logistics constraints. These moves demonstrate two important facts: first, feedstock volatility is a real and immediate determinant of finished resin economics; second, leading suppliers are prepared to invoke price increases to protect margins when pass‑through is feasible. For buyers and OEM procurement teams, these events elevate the importance of hedging, indexation clauses, and flexible sourcing strategies.
Market structure and bargaining power
The market sits in a moderately concentrated structure: a small set of multinational producers accounts for a meaningful share of supply, while a broader tier of players serves regional niches and specialty applications. This structure yields outsized supplier influence during input‑cost shocks but leaves space for agile contract strategies and value‑added services (technical support, color matching, and custom compounding) to secure preferential treatment and stable supply.
Segment dynamics shaping near‑term winners
- Application momentum: High‑clarity requirements in medical devices and modern consumer electronics create demand for premium transparent grades. These applications favor suppliers that can demonstrate tight optical tolerances and traceable quality systems.
- Performance trade‑offs: Formulators face a three‑way trade between impact resistance, rigidity and optical clarity. Manufacturers that can tune formulations to a given OEM’s processing window (e.g., higher flow for thin‑wall molding or low stress whitening for visible surfaces) will capture margin pools above commodity resin levels.
- Sustainability constraints: Recycling transparent ABS is more challenging than opaque grades due to color and clarity retention. Chemical recycling and dedicated collection streams are two high‑value R&D pathways identified in the study.
- Price sensitivity: End markets are variably price elastic. Appliance and industrial demand shows more sensitivity to resin pricing than medical devices — an important consideration for pricing strategy and contract tenure negotiations.
Priority actions for corporate leaders in 2026
Based on the macro view and scenario testing, we recommend a prioritized three‑tier action plan to convert market expansion into sustainable margin and volume gains in 2026:
- Immediate (0–6 months): Lock and hedge. Negotiate short‑term fixed volumes with mixed indexation, secure logistics lanes, and execute limited feedstock hedges where feasible. Implement scalp pricing clauses to avoid unexpected margin erosion during raw material spikes.
- Near term (6–18 months): Product and commercial capture. Develop or qualify premium transparent grades tailored to high‑value segments. Strengthen technical partnerships with top suppliers and invest in color/optical labs that shorten qualification timelines for OEMs.
- Strategic (18–36 months): Capacity, sustainability and M&A. Evaluate brownfield expansions or tolling agreements in markets where demand growth and feedstock economics align. Pursue targeted acquisitions of specialty compounding assets that fill capability gaps (e.g., scratch‑resistant or MABS technologies). Embed a sustainability roadmap that prioritizes circularity for transparent grades.
How PW Consulting’s report de‑risks your 2026 choices
This research is structured to be actionable for three executive audiences: procurement chiefs needing contract playbooks; product/engineering leads defining material specs; and corporate strategy teams sizing opportunities for M&A or capacity investment. The combination of a transparent forecasting engine, supplier scorecards, and scenario P&L models enables executives to stress‑test decisions against the most likely market evolutions in 2026–2028.
To maintain the report’s role as a decision enabler, we have deliberately kept granular regional and application split tables, and the detailed revenue-by‑segment grids, exclusive to the full deliverable. These are the exact tables that operations, procurement and corporate development teams will use when executing commercialization plans and negotiating supplier agreements.
Next step — get the full intelligence
If you are planning procurement cycles, product launches, capacity investments, or M&A activity in 2026, the full Transparent ABS Plastics Market report and the embedded model are essential planning tools. The comprehensive dataset contains the segment‑level revenue breakdowns, supplier‑level volumes and price scenarios that are intentionally excluded from this preview. Contact PW Consulting to access the full report and downloadable modeling workbook so your team can translate the high‑level insights above into executable plans with confidence.
For detailed analysis of this topic, please visit the official page: Transparent ABS Plastics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air Deodorizer & Sterilizer Market to reach USD 13.42B by 2032 at 8.1% CAGR
By pmarketresearch, 2026-07-13
Air Deodorizer and Sterilizer Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a focused strategic preview of our comprehensive Air Deodorizer and Sterilizer Market study (base year 2025). This briefing synthesizes the macro trajectory, competitive dynamics, regulatory inflection points, and the high‑impact levers that corporate leaders must prioritize in 2026. Consider this a strategic trailer: it demonstrates the analytical depth that underpins our full study while intentionally withholding granular segment tables to prompt direct engagement with the source report for transaction‑grade data.
Air Deodorizer And Sterilizer Market
Macro Trajectory: Market Momentum and What It Means
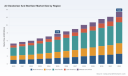
The global market for air deodorization and sterilization has moved from niche adoption to mainstream capital planning over the past half‑decade. Measured in USD (Billion), the market expanded from approximately 5.27 in 2020 to around 7.78 in 2025 and is projected to reach roughly 13.42 by 2032. This trajectory represents a compound annual growth rate (CAGR) of 8.1% over the forecast window, reflecting persistent demand driven by healthcare requirements, workplace health priorities, hospitality recovery, and heightened consumer awareness of indoor air quality (IAQ).
Air Deodorizer And Sterilizer Market
For corporate decision‑makers, that growth profile is more than a headline. It defines the envelope within which product roadmaps, manufacturing investments, channel strategies, and M&A activity must be calibrated. A sustained ~8% CAGR supports multi‑year investments in next‑generation sterilization technologies (UVC LED, plasma, advanced filtration), but it also requires discipline: not every product variant or regional push will scale proportionately. The full report contains deterministic forecasts, scenario variants, and sensitivity analyses that translate this headline CAGR into actionable revenue curves and break‑even horizons for specific product archetypes.
Air Deodorizer And Sterilizer Market
Why 2026 Is a Strategic Inflection Point
- Capital allocation windows are opening: With 2026 marking the transition from recovery to sustained growth for several end markets, firms face decisions about ramping production lines, dedicating R&D budgets to sterilization vs. deodorization features, and prioritizing certification pathways for medical use.
- Regulatory and certification gates matter: Medical‑grade clearances and food‑safety certifications materially expand addressable markets but also extend time‑to‑market and capex requirements.
- Channel economics are shifting: The interplay between direct healthcare procurement, commercial HVAC integration, and consumer retail is reshaping pricing power and margins.
In practical terms: 2026 is the year to decide whether to scale, partner, or exit specific subsegments. Our report equips executives with the scenario planning and economic models required to take those decisions with confidence.
Report Coverage: Operational Intelligence You Can Use
PW Consulting’s full study contains the following practitioner‑oriented deliverables (high level):
- Comprehensive market sizing and forecasts (2020–2032) with baseline and stress scenarios, including forward curves by product archetype and adoption phase.
- Granular segmentation (by region, by device type, by end application) with growth velocity matrices—note: this preview deliberately omits those tables to preserve the value of the full dataset.
- Technology landscape map: evaluation of UVC (including UVC LED), plasma, HEPA/filtration hybrids, photocatalytic oxidation and emerging innovations—each assessed for efficacy, cost, certification burden and deployment use cases.
- Regulatory and compliance playbook tailored to medical, commercial and food‑service channels (including certification timelines, lab protocols and procurement requirements).
- Competitive benchmarking: validated vendor scorecards, capability matrices, go‑to‑market archetypes, and prioritized partnership targets.
- Go‑to‑market templates for OEMs, integrators and channel partners: pricing models, pilot frameworks, procurement tender language and KPI dashboards for post‑deployment validation.
- M&A and partnership heatmap: valuation multiples, strategic rationale for bolt‑on acquisitions, and checkpoints for rapid integration.
- Supply‑chain stress tests and component roadmap: critical inputs, lead‑time exposures, and recommended dual‑source strategies for high‑risk parts.
These deliverables are designed to convert market projections into executable plans: where to deploy capital, which certifications to prioritize, how to price for hospital tenders versus commercial HVAC channels, and how to structure distribution partnerships for rapid scale.
Competitive Landscape: Strategic Implications of Core Players
The competitive structure is characterized by a mix of specialized technology providers and large diversified industrial OEMs. The market concentration metrics indicate meaningful leader presence—our analysis shows that the top three firms hold a significant share of the market, while the top five consolidate a further portion of industry revenue—highlighting an environment where scale and certification credentials create durable advantages.
- Sanuvox Technologies (Montreal, Canada): A specialist in UV air purification and surface disinfection with solutions positioned for institutional healthcare. Sanuvox’s patented UV architectures and hospital deployments make it a first mover for clients prioritizing validated pathogen inactivation.
- Camfil (Stockholm, Sweden): Renowned for advanced filtration and high‑containment production capacity, Camfil is strategically placed to serve hospital, lab and controlled environment projects where filtration performance and supply reassurance matter.
- Novaerus / WellAir (Charlotte, NC): A leader in portable plasma air disinfection with FDA 510(k) clearances for certain product lines, enabling direct access to healthcare procurement channels that require medical device classification.
- Trion (Peachtree City, GA): Focused on commercial IAQ solutions and attractive to integrators who value modular systems for large facilities.
- Panasonic and Daikin (Osaka, Japan): Large OEMs with R&D scale and broad distribution; their investments in proprietary deodorization (nanoe™, Streamer) and plug‑and‑play sterilization products position them to capture both consumer and commercial segments rapidly.
- IQAir and Blueair (Switzerland/Stockholm): Brands that emphasize HEPA performance and consumer/medical certifications, respectively—important for customers prioritizing particle removal and validated filtration efficacy.
Recent corporate actions further crystallize market direction: strategic distribution partnerships, product launches featuring real‑time IAQ sensing and UVC LED sterilization, and industry recognition that reinforces brand trust. Each of these moves alters channel dynamics and shortens the path to market for differentiated products.
Regulatory, Certification and Supply Considerations
Regulation and certification materially affect access to high‑value segments. Notable compliance and certification dynamics to factor into 2026 plans include the following:
- Food safety and antibacterial deodorization certifications can unlock hospitality and food‑service procurement pipelines.
- Medical device clearances create exclusive procurement corridors in hospitals but require sustained clinical validation and regulatory engineering investment.
- Zero‑ozone and regional air quality compliance regimes impose design constraints and influence component selection and manufacturing locations.
- Manufacturing scale, exemplified by advanced filtration production lines, is a competitive moat—firms that secure capacity early can protect margins when demand surges.
Our full report includes a decision matrix mapping certification choices to forecasted incremental addressable revenue and payback periods—an indispensable tool when deciding whether to fast‑track clinical trials or prioritize retail rollouts.
Actionable Strategic Recommendations for 2026
- Prioritize certification pathways by segment economics: For companies targeting healthcare, invest in medical‑grade clearance early. For hospitality and consumer markets, HACCP and food‑safety recognitions may deliver faster commercial adoption with lower regulatory cost.
- Match technology to channel economics: UVC LED and plasma offer faster differentiation but can carry higher upfront R&D and component scarcity risks; HEPA and filtration hybrids scale more predictably through existing HVAC channels.
- Lock capacity and diversify suppliers: Secure production capacity for critical filters and optics; mitigate lead times through dual sourcing and nearshoring where appropriate.
- Design channel‑specific value propositions: Build discrete sales plays for hospital procurement, wholesale HVAC integrators, and consumer retail—with tailored pricing, warranty, and service models for each.
- Pursue targeted partnerships and bolt‑on M&A: Use partnership frameworks to accelerate distribution, and consider small acquisitions to acquire certifications, distribution access or specialized IP.
Each recommendation is supported by quantified ROI scenarios in the full study—models that show how incremental investments in certification, production capacity or channel development translate into NPV under different adoption curves.
Risk Radar and Contingency Planning
Key risks to monitor include component supply disruption, changes in regional regulatory standards, and the emergence of alternative disinfection modalities that shift adoption curves. The report contains stress test outputs that quantify revenue and margin impacts under late‑cycle component shortages and accelerated regulatory change—allowing leaders to create contingency budgets and flexible supply contracts.
Next Steps
This preview outlines the strategic terrain for the Air Deodorizer and Sterilizer market as companies prepare to act in 2026. For procurement teams, R&D leaders and corporate strategists, the full PW Consulting report provides the granular tables, vendor share data, and executable playbooks necessary to move from insight to action. Our dataset includes the full segmentation by region, type and application, plus vendor scorecards, pricing curves and scenario models that are intentionally withheld from this preview.
To access the complete intelligence suite—including deterministic revenue tables, segmental growth drivers, and step‑by‑step implementation templates—please refer to the detailed report page. PW Consulting stands ready to support bespoke advisory and implementation workstreams that translate these findings into measurable outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Air Deodorizer And Sterilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blister Tooling Market to Hit USD 244.96M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Blister Tooling Market: Strategic Intelligence for 2026 Decision-Makers
Executive snapshot
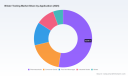
As companies recalibrate supply chains and product portfolios for 2026, blister tooling has emerged as a focal point for operational resilience and regulatory compliance across pharmaceutical, medical device and fast-moving consumer product lines. PW Consulting’s new Blister Tooling Market study positions senior executives to convert packaging tooling choices from a cost center into a competitive lever. The market expanded from roughly USD 144 million in 2020 to about USD 180 million by 2025. Beginning 2026 we estimate the market at approximately USD 185 million, and our scenario-weighted baseline forecasts a compound annual growth rate near 7% through 2032, with the market approaching the mid‑hundreds of millions by the end of the forecast window.
Blister Tooling Market
Why this matters for 2026 strategic decisions
-
Timing capital allocation: Companies planning capital expenditure or line conversions in 2026 must reconcile one-time tooling investments with a pathway to amortize costs under increasing regulatory and sustainability obligations. Our study quantifies key break-even horizons under realistic throughput and scrap assumptions and shows how a ~7% market growth trajectory affects supplier capacity and delivery risk.
Blister Tooling Market -
Supplier selection and dual-sourcing: Blister tooling remains a fragmented supply market (CR3 ≈ 25%), which creates both opportunity and operational risk. Buyers who move beyond price—assessing machine compatibility, local engineering support, lead times and aftermarket responsiveness—can materially reduce downtime and validation cycles.
Blister Tooling Market -
Regulatory-driven rework and validation: Heightened scrutiny on GMP, serialization, and packaging material stewardship is increasing validation workloads. Decisions made in 2026 about tooling standards and supplier validation strategies will determine the ease and cost of meeting evolving compliance expectations.
What PW Consulting’s Blister Tooling Market study delivers (practical, transaction-ready content)
This research is designed as a decision kit for C-suite and functional leaders—operations, packaging, regulatory, procurement and M&A. Rather than high-level rhetoric, the report provides actionable modules that teams can use immediately during 2026 execution cycles:
-
Executive dashboards: Scenario-based P&L and cash-flow implications of tooling choices, including sensitivity to throughput, uptime improvement and scrap reduction.
-
Tooling procurement playbooks: Standardized RFP templates, validated evaluation criteria (technical, regulatory, warranty/LTAs), and negotiation tactics calibrated to supplier concentration and lead-time dynamics.
-
OEM and third‑party compatibility maps: Machine-to-tooling compatibility matrices, changeover time benchmarks, and guidance on retrofits versus OEM replacement strategies.
-
Validation and regulatory checklists: Pre-supplied test plans and CSV/qualification templates aligned with 21 CFR 211 and EU GMP Annex 15 requirements to accelerate line qualification without sacrificing compliance.
-
Sustainability and material strategy: Practical evaluation frameworks for switching to higher post-consumer content materials, including cost-impact heat maps and recommended pilot protocols that anticipate regional EPR and recycled-content mandates.
-
CapEx/Opex trade-off models: Decision trees for buy vs. lease vs. service agreements that quantify lifecycle cost across tooling families and production profiles.
-
M&A and partnership playbooks: Target shortlists, valuation multiples for tooling businesses and a due-diligence checklist tailored to intellectual property, contract backlogs and service capabilities.
-
Operational playbooks: Best-practice maintenance schedules, spare-parts strategies, and modularization tactics to reduce time-to-changeover on high-mix lines.
Competitive landscape — how leading players shape choices in 2026
The blister tooling supply base blends specialist tooling houses, machine manufacturers producing integrated tooling, and contract packagers that internalize tooling capabilities. Key players profiled in our study include:
-
HPT Pharma (Warminster, PA) — A specialist focused on precision tooling for pharmaceutical and nutraceutical lines. HPT’s strength lies in end-to-end format sets and in-house CNC capacity that shortens lead times relative to OEM channels. For buyers prioritizing fast replacement and validated format libraries, HPT’s model is a compelling alternative to OEM supply.
-
Pharmaworks (USA) — A prominent North American machine builder that designs tooling for both its equipment and third-party machines. Pharmaworks is expanding into robotics and high-speed feeders; recent 2026 product introductions (including a robotic feeder and enhancements to its TF1e machine) signal a push toward higher automation and plug-and-play tooling ecosystems.
-
Prodieco (Europe, with US presence) — Offers broad format solutions and validation services, and in 2026 made strategic moves to strengthen local North American support through partnership agreements. For firms needing validated tooling with regional engineering backup, Prodieco’s network is a pragmatic option.
-
Ascend Packaging Systems — A custom manufacturer focused on change parts and feeders with an emphasis on compatibility across major machine brands—useful for manufacturers seeking bespoke solutions without full OEM dependence.
-
Contract packagers and tooling fabricators such as Blisterpak, VisiPak, and Sharples Die feature in our supplier maps as important local capacity nodes, often preferred for thermoforming and card sealing tooling because of integrated production and tooling support models.
Recent activity through early 2026 shows a market balancing product innovation (robotic feeders, faster changeover tooling) with distribution and service expansion—evidence that buyers can negotiate not only on price but on total value (validation support, speed-to-market, and lifecycle servicing).
Regulatory and sustainability dynamics that will drive tooling strategy
-
Regulatory tightening: Compliance requirements such as 21 CFR 211, EU GMP Annex 15, and strengthened DSCSA traceability expectations continue to increase validation scope at package level. Tooling specifications that facilitate product traceability, material segregation and controlled environments materially reduce time-to-approval for new SKUs.
-
Extended producer responsibility and recycled-content mandates: Jurisdictional advances—such as California’s EPR program and multi-state recycled content laws—are reshaping material selection decisions for blister substrates. Tools and seals must be validated for alternate substrate formulations; early pilots mitigate downstream rework risk.
-
Quality and serialization: Buyers increasingly require tooling that integrates with serialization and tamper-evidence workflows; tooling vendors that deliver validated interfaces accelerate regulatory compliance and reduce integration costs.
Strategic recommendations for 2026 (what to do in the next 6–18 months)
-
Prioritize validation-friendly tooling: Select tooling partners that provide qualification artifacts and pre‑tested format sets to shorten regulatory timelines.
-
Implement dual-sourcing for critical SKUs: Given supplier fragmentation and lead-time variability, dual-sourcing reduces single-point failure risk without eroding price leverage.
-
Run targeted sustainability pilots: Choose 2–3 SKUs for accelerated substrate trials with tooling partners who can co‑develop and validate the alternative materials under production conditions.
-
Negotiate service-level agreements linked to uptime and changeover targets: Contract terms tied to measurable performance reduce total cost of ownership and create incentives for vendor innovation.
-
Build tooling roadmaps into product portfolio planning: Align product lifecycle decisions with tooling amortization timelines to avoid repeated retooling costs as product families evolve.
Methodology, data integrity and what’s intentionally withheld
Our findings combine primary interviews with tooling manufacturers, OEMs and packaging end-users, proprietary shipment and pricing models, and regulatory/standards mapping. Historical data spans 2020–2025; the forecast window runs 2026–2032. To preserve the utility of this public preview while protecting the proprietary analytical value in the full study, this article intentionally omits granular regional and application splits, and precise segment-level revenue figures. The full report includes breakouts, supplier scorecards, validated pricing bands and downloadable procurement templates.
Conclusion — the strategic value proposition
For 2026, blister tooling decisions are no longer tactical line items; they are strategic inflection points that affect speed-to-market, compliance cost and sustainability positioning. PW Consulting’s Blister Tooling Market study equips executives with the quantitative scenarios, supplier playbooks and regulatory-ready tools required to make confident, defensible decisions throughout 2026 and beyond. If your objective is to reduce validation cycle time, lower total cost of ownership, and de‑risk packaging transitions while meeting emerging sustainability mandates, the full report contains the operational intelligence you will use this year.
Next steps
Access the full study for detailed regional and application breakouts, supplier scorecards, and the transaction-ready toolkits described above. Our team is available for bespoke briefings and scenario modeling to align the findings to your 2026 capital and operational plans.
For detailed analysis of this topic, please visit the official page: Blister Tooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Keratin Market 2026 Strategic Preview — A PW Consulting Industry Brief
As companies prepare strategic plans and capital allocations for 2026, the keratin market presents a distinctive combination of steady macro growth, concentrated supplier power, and accelerating technological and regulatory disruption. This brief synthesizes the most consequential signals from PW Consulting’s full Keratin Market Report (base year 2025) to help senior executives, product leaders, and investment committees frame decisions that capture upside while limiting downside. Consider this a high-quality trailer: rigorous, source-backed insight designed to inform your agenda-setting — with the complete datasets, segment tables and scenario models reserved for the full report.
Keratin Market
Market at a Glance: Growth Trajectory and Structural Context
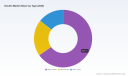
Our market model, anchored on a 2025 base year (USD, revenue unit: Million), documents a clear recovery and re-acceleration phase across 2020–2025 and projects continued expansion through 2032. After rising from a mid-single-thousand-million base in 2020 to a 2025 valuation used as the report’s reference point, the keratin market is expected to grow at a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. Under the central scenario, this trajectory implies meaningful incremental demand across personal care, therapeutic wound care, and adjacent nutraceutical and food applications.
Keratin Market
Competitive structure is moderately concentrated: the top three suppliers account for a meaningful share of global revenues, and the top five further increase concentration—conditions that create both defensive advantages for incumbents and entry points for well-capitalized challengers with differentiated technology, sustainable sourcing, or regulatory-savvy go-to-market strategies.
Keratin Market
Why 2026 Is a Strategic Inflection Point
-
Demand maturation in high-value applications: Personal care remains the primary commercial engine, but higher-margin therapeutic and medical uses (advanced wound care, nutraceutical formulations) are scaling faster as clinical validation and reimbursement pathways mature.
-
Shift from commodity to specialty: Buyers increasingly prize traceability, claim substantiation, and functional performance (peptide engineering, controlled hydrolysis profiles). Suppliers that can couple raw-ingredient economics with technical service will capture disproportionate value.
-
Regulatory tightening and consumer scrutiny: Updated safety guidance and chemical restrictions require proactive reformulation, transparent labeling, and more robust tamper-proof safety data — all of which raise the bar for compliance and accelerate consolidation among suppliers who can meet stricter standards.
Regulatory and Policy Dynamics — Practical Implications
Two regulatory developments are especially material for 2026 planning. First, updated safety guidance on heat-activated hair smoothing products has raised liability and labeling requirements for formulations that may emit aldehydes under intended use. Second, jurisdictional bans on certain formaldehyde-releasing chemistries (enacted at state levels) have tightened formulation windows for traditional keratin hair treatments.
Strategic response options we recommend to clients:
-
Immediate compliance triage: map existing SKUs against the guidance, identify at-risk products, and prioritize reformulation or withdrawal pathways.
-
Labeling and claims governance: anticipate more conservative claims substantiation and invest in standardized safety testing and consumer-facing transparency (e.g., sourcing certificates, third-party verification).
-
Regulatory scenario planning: build adaptive product roadmaps that allow rapid substitution of at-risk chemistries without disrupting commercial channels.
Competition and Recent Developments — What Matters to Buyers and Investors
Our competitive scan focuses both on legacy chemical majors and specialist ingredient houses. Two exemplars illustrate the strategic polarity in the industry:
-
Keraplast (Christchurch, New Zealand) — a specialist producer that leverages regeneratively sourced sheep wool to deliver high-performance keratin ingredients and peptides across personal care, nutraceutical, and wound care markets. Keraplast’s recent exclusive manufacturing agreement with a wound-care partner demonstrates how targeted partnerships can accelerate clinical and commercial scale-up in therapeutic niches.
-
BASF SE (Ludwigshafen, Germany) — a diversified chemical leader that is intensifying its play in natural-based personal care inputs, as evidenced by product innovations focused on sustainability-derived polymers and betaine alternatives. Such moves underscore a broader trend: major suppliers are de-risking portfolios toward sustainable feedstocks and lighter claim sets that align with consumer and regulatory demand.
For strategists, the takeaway is twofold: (1) specialist producers can command premium value through provenance, formulation support, and clinical positioning; (2) large suppliers bring scale, procurement heft, and route-to-market breadth, and they are moving rapidly to occupy the sustainable-ingredient premium.
Technology and Innovation Themes to Watch in 2026
-
Bioprocessing and peptide precision: advances in controlled hydrolysis and peptide fractionation are enabling differentiated functional profiles for hair repair and wound-healing applications.
-
Alternative sourcing: regenerative livestock sourcing, feather and byproduct valorization, and early-stage microbial fermentation approaches are reshaping input risk and sustainability narratives.
-
Formulation adjacencies: convergence with natural polymer innovation (lightweight styling polymers, betaines from sustainable oils) is creating integrated ingredient suites that reduce formulation complexity for OEMs.
Commercial and M&A Playbook for 2026
Our analysis identifies five practical strategic moves that should be considered this year:
-
Portfolio triage: segment products into defend, refactor, and retire categories based on regulatory risk, margin profile, and growth trajectory — allocate R&D resources accordingly.
-
Partnership-first scale-up: where clinical or regulatory validation is required (e.g., wound care), partner with contract manufacturers or specialist OEMs to accelerate commercialization while containing capital outlay.
-
Targeted M&A and bolt-ons: prioritize acquisitions that fill upstream traceability gaps (sustainable raw-material controls), add peptide engineering capability, or provide immediate access to regulated medical channels.
-
Pricing and contract redesign: implement indexing and pass-through mechanisms for spikes in input costs, and negotiate longer-duration offtake contracts with key raw-material suppliers to stabilize supply.
-
Brand and claims defensibility: invest in clinical endpoints and third-party verification to protect premium price points and expedite payer acceptance in healthcare segments.
Report Deliverables — What You’ll Find in the Full PW Consulting Keratin Report
The full study contains the operating model and granular intelligence needed to execute the playbook above, including:
- Proprietary market-sizing model (historical 2020–2025; forecast 2026–2032) with scenario toggles and sensitivity analyses.
- Competitive profiles and strategic positioning maps for incumbent and emerging suppliers.
- Regulatory matrix and red-team assessments of jurisdictional risks.
- Technology tracker covering sourcing, processing, and formulation innovations.
- Commercial heat maps and go-to-market playbooks by channel and use case.
- M&A screening framework and a prioritized target list based on strategic fit and integration complexity.
To preserve commercial value and drive direct engagement, detailed segment breakouts (regional, by type, by application) and the downloadable model are available exclusively through the PW Consulting report portal.
Practical Next Steps for 2026 Decision-Makers
-
Immediate (0–3 months): commission a regulatory exposure audit of your keratin-containing SKUs; validate supplier documentation and perform a claims risk review.
-
Near-term (3–9 months): run scenario tests using our market model to inform 2026 budget allocations for R&D, capacity, and strategic partnerships; prioritize one or two pilot reformulations to mitigate regulatory exposure.
-
Medium-term (9–18 months): pursue strategic supply agreements or bolt-on M&A to secure raw-material traceability, peptide engineering capability, or medical-channel access.
Concluding Perspective
The keratin market in 2026 sits at the intersection of robust demand growth — underpinned by personal care and therapeutic applications — and an evolving regulatory and sustainability landscape that penalizes inaction. Our central forecast shows continued expansion at a mid-single-digit CAGR, creating attractive returns for firms that can combine technical differentiation with regulatory foresight and supply-chain resilience. At the same time, moderate market concentration signals an opening for focused entrants that offer provenance, clinical validation, or cost-effective alternatives.
PW Consulting’s full Keratin Market Report delivers the quantitative backbone and qualitative insight to turn these signals into executable strategies. For access to the detailed segment tables, the full financial model, and bespoke advisory options to support 2026 planning, please consult the PW Consulting report access page or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Keratin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Micromachining Market to Hit USD 606.48M by 2032 (7.6% CAGR)
By pmarketresearch, 2026-07-13
Laser Micromachining Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
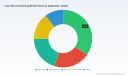
The laser micromachining market is at an inflection point. After steady expansion through the early 2020s, the market reached an estimated USD 366.25 Million in our base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 7.6% over the 2026–2032 forecast period, reaching roughly USD 606.48 Million by 2032. These headline metrics reflect the combined effect of robust demand in high-precision sectors, accelerating adoption of ultrafast and fiber laser technologies, and steady improvements in throughput and cost-efficiency that make micromachining competitive against traditional micro-CNC and etching processes.
Laser Micromachining Market
Why this matters for corporate decision-making in 2026
-
Timing and scale: The mid-2020s are the window where practical performance gains translate directly into procurement, capacity, and product design choices. With a clear multi-year growth trajectory, capital allocation for laser-based microprocessing is no longer exploratory — it is strategic. Decisions made in 2026 will determine whether firms are technology leaders or late adopters across the next product cycle.
Laser Micromachining Market -
Cost and productivity inflection: Our sector analysis indicates laser micromachining can reduce labor costs by up to 70% relative to traditional CNC approaches in precision manufacturing contexts. This reshapes unit economics for small-feature, high-mix production runs, particularly in electronics, medical devices, and advanced packaging.
Laser Micromachining Market -
Regulatory and safety obligations: Compliance is now a commercial constraint. Recent regulatory developments — including the EU Machinery Regulation requirements for CE-marking of laser equipment, FDA expectations for laser-controlled medical device processes, ISO 11553-1 industrial laser safety standards, and national laser safety standards such as China GB/T 7247.1 — must be built into procurement, validation, and supplier selection strategies. Non-compliance risks slow market entry, unexpected costs, and damaged customer relationships.
-
Market structure: The competitive landscape shows meaningful concentration at the top: the three largest suppliers account for a majority share of the market footprint (CR3 ~58%), while the top five raise this concentration to approximately 68% (CR5 ~68%). This mixed structure of strong incumbents and innovative challengers creates both partnership opportunities and competitive threats depending on your go-to-market approach.
What the PW Consulting report delivers — practical, decision-grade outputs
Our report is designed for commercial leaders, procurement teams, product architects, and corporate development executives who need actionable intelligence in 2026. Key deliverables include:
- Validated market sizing and forward-looking scenario modeling (base year 2025, forecast 2026–2032) with sensitivity tests tied to technology adoption and macroeconomic variation.
- Technology roadmaps that match laser types to applications and cost buckets, including practical trade-offs for ultrafast, fiber, excimer and CO2 platforms.
- A battery of procurement tools: supplier shortlists, vendor scorecards, sample RFP language, and compliance checklists aligned with EU/FDA/ISO/GB standards.
- Operational playbooks for factory integration, including process qualification templates, cycle-time optimization guides, and maintenance/Spare Part strategies to manage uptime.
- Commercial models and ROI templates to compare CAPEX vs OPEX deployment scenarios, including break-even horizons under conservative and aggressive adoption curves.
- Competitive landscape dossiers and go-to-market maps highlighting strategic options: OEM partnerships, captive manufacturing, contract micromachining, and licensing.
- Dealflow and M&A screening heuristics tailored to market concentration metrics and technology gaps, plus illustrative transaction case studies.
- Executive dashboards and investment memos that translate technical findings into board-ready recommendations.
Competitive landscape snapshot — who matters and why
The market blends global incumbents with specialized innovators. Below is a condensed, practical read on the firms shaping supply-side dynamics in 2026 and why they matter to decision-makers.
-
Coherent (United States) — Strength: precision manufacturing lasers and systems targeted at high-accuracy cutting, drilling, marking and ablation. Strategic implication: attractive as a systems partner for industrial OEMs and display/semiconductor capital equipment integrators seeking turnkey solutions.
-
IPG Photonics (United States) — Strength: fiber-laser sources optimized for microprocessing, microwelding and microdrilling. Strategic implication: core supplier for players prioritizing high beam quality and reliability; recent industry recognition underscores product maturation and scale readiness.
-
TRUMPF Group (Germany) — Strength: industrial-grade cutting and marking systems (TruLaser series) with deep process control. Strategic implication: favored by manufacturers requiring robust factory integration and service footprints across mature industries.
-
Han’s Laser Technology Industry Group (China) — Strength: comprehensive portfolio for precision cutting and processing with strong regional distribution. Strategic implication: competitive option for cost-sensitive high-volume deployments and regional supply security.
-
GF Machining Solutions (Switzerland) — Strength: dedicated micromachining machines for micro-engraving, shaping and drilling. Strategic implication: appealing to precision tool users and contract manufacturers servicing advanced medical and aerospace niches.
-
AMADA WELD TECH (Japan) — Strength: Delta Laser systems and femtosecond integration for ablation, drilling and surface texturing. Strategic implication: relevant for product teams pursuing next-level surface functionalization and micro-assembly.
-
3D-Micromac (Germany) — Strength: laser micro-structuring for semiconductors, sensors and packaging. Strategic implication: a go-to for advanced packaging and sensor OEMs seeking tight process controls and niche expertise.
-
Oxford Lasers (UK), Lasea (Belgium), OpTek Systems (UK) — Strength: high-precision marking, microstructuring and high-speed material removal respectively. Strategic implication: specialized suppliers that can supply capability gaps or co-develop bespoke solutions for electronics and industrial customers.
Recent market activity and signals
- Trade shows and demonstrations in early 2026 have accelerated visibility for femtosecond and compact high-power sources — notable public showcases include platforms focused on ultra-precise micromachining and fiber-based solutions.
- Industry awards and technology recognition in 2026 are validating new single-mode, high-power laser sources that materially change throughput assumptions for certain microprocessing applications.
- Regional compliance events and standard updates have increased the bar for supplier validation, creating an opening for certified integrators and a hurdle for small scale entrants without compliance capabilities.
Strategic actions we recommend for 2026
-
Portfolio review: Map your product roadmaps to micromachining capabilities now. For R&D teams, prioritize feasibility pilots with femtosecond and high-brightness fiber lasers where material quality or microfeature integrity is a differentiator.
-
Procurement & compliance: Require CE/FDA/ISO conformity evidence in RFPs and budget for validation time. Compliance documentation is a commercial lever — early-certified partners shorten time-to-market.
-
Manufacturing footprint: Use our CAGR-backed capacity planning templates to decide between in-house adoption vs contract micromachining partnerships. Consider hybrid models where high-mix, low-volume work is outsourced while high-volume, IP-sensitive processes are retained.
-
Partnering & M&A: With top-tier suppliers commanding significant share, targeted acquisitions or strategic alliances are effective routes to access advanced beam sources, process know-how, or distribution in key regions.
-
Service & aftermarket: Build service and spare-part strategies into procurement decisions; equipment uptime and process reproducibility are major differentiators for OEM customers.
Practical next steps — a 90-day plan for executives
- Initiate a technology pilot with one incumbent and one specialist supplier to validate process performance on your critical materials.
- Commission a compliance gap analysis focused on EU/FDA/ISO/China laser standards to avoid procurement delays.
- Use PW Consulting’s vendor scorecard to shortlist three suppliers for a formal RFP and a two-week on-site evaluation phase.
- Run a rapid CAPEX vs OPEX scenario using our ROI templates to determine the most economic deployment pathway based on your projected volumes using the 7.6% market growth baseline.
Closing — the report as the next strategic lever
This brief is a strategic “trailer.” It surfaces the critical dynamics, the competitive map, and the decision levers that matter in 2026 — but it intentionally omits the granular regional and application-level splits and the supplier-level revenue details that are essential for transaction-grade decisions. The full PW Consulting Laser Micromachining Market report contains those detailed regional and application segmentation tables, interactive scenarios, supplier scorecards, and downloadable procurement templates that operational teams need to execute quickly and confidently.
For teams planning capital commitments, supplier negotiations, or M&A activity in 2026, acquiring the full report is the recommended next step. PW Consulting’s analysts are available to walk clients through tailored readouts that turn the forecast and market structure into a concrete implementation roadmap.
For detailed analysis of this topic, please visit the official page: Laser Micromachining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antipyretic & Analgesic Market to Reach USD 70.62 Million by 2032
By pmarketresearch, 2026-07-13
Antipyretic & Analgesic Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
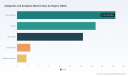
PW Consulting’s latest market intelligence on the Antipyretic & Analgesic sector uses 2025 as the base year and examines historical trends from 2020–2025, with a forward-looking forecast covering 2026–2032. The global market demonstrated steady expansion through the 2020s, rising from under USD 40 million (2020) to roughly USD 50 million in 2025, and our modeling projects continued growth to an estimated market size north of USD 70 million by 2032 under a mid‑case trajectory. This path reflects a compounded annual growth rate (CAGR) for the forecast period of approximately 5.09%.
Antipyretic and Analgesic Market
For senior executives evaluating resource allocation, portfolio moves, or M&A activity in 2026, these headline dynamics signal a market that is mature but still offers pockets of profitable expansion—provided companies align strategy to regulatory risk, supply‑chain realities, and emergent clinical and product innovation.
Antipyretic and Analgesic Market
Why this intelligence matters for 2026 corporate strategy
- Timing capital and M&A moves: With a mid‑single digit CAGR and an uneven growth runway across product forms and channels, 2026 is a window to consolidate assets, selectively acquire API/finished-dose capacity, or invest in differentiated formulations ahead of expected demand inflection points.
- Regulatory and quality risk management: High‑visibility recalls and label initiatives in 2025–2026 elevate regulatory premium; proactive remediation, labeling strategies, and physician outreach programs will materially affect market access and brand trust.
- Portfolio prioritization: Companies must decide whether to double down on established mass‑market OTC brands, pursue Rx‑to‑OTC switches, or invest in differentiated non‑opioid analgesics that can command premium positioning.
- Supply‑chain and manufacturing decisions: API capacity moves and episodic contamination recalls underscore the need for dual sourcing, regional manufacturing footprints, and supplier oversight as core to continuity and cost control.
Market dynamics shaping 2026 strategy
The Antipyretic & Analgesic market is being pulled in three directions simultaneously: steady baseline demand for symptomatic fever and pain relief; selective premiumization and formulation innovation; and episodic regulatory and safety shocks that reallocate demand and create short‑run volatility.
Antipyretic and Analgesic Market
- Growth fundamentals: Demographic trends, greater OTC self‑care adoption in emerging markets, and a continued focus on non‑opioid pain management sustain baseline expansion. The overall market trajectory to 2032 embodies these structural tailwinds while remaining sensitive to regulatory signals.
- Regulatory headwinds: A notable 2025–2026 development is the initiation of label review processes by the US regulator for acetaminophen products following safety communications. Label adjustments and physician advisories can depress demand in sensitive sub‑segments and shift prescribing behavior; companies should prepare for phased impacts rather than an immediate demand collapse.
- Quality and recall shocks: Recent class II recalls involving acetaminophen and naproxen formulations (late 2025 and mid‑2026) highlight persistent execution risk in packaging and chemical control. These events produce short‑term market share swings and long‑term reputational effects, emphasizing the importance of end‑to‑end quality systems and rapid crisis communication playbooks.
- Supply‑side capacity: Strategic investments by major chemical suppliers to expand API capacity—particularly for widely used actives—have materially improved supply stability since the early 2020s. Firms that secure offtake agreements or co‑invest in capacity gain a measurable competitive cost and reliability advantage.
- Innovation pressure: The approval of a first‑in‑class non‑opioid oral analgesic in early 2025 introduces a new competitive axis: novel mechanisms that can displace legacy actives in moderate‑to‑severe pain indications. This shifts the R&D calculus for incumbents: defend, partner, or pivot.
Competitive landscape — mapped for action
We mapped the competitive set across four archetypes—global consumer health brands, generics manufacturers, API producers, and platform innovators—and profiled a set of incumbent and emergent players critical to 2026 planning:
- Global consumer health leaders (e.g., large established CPG/consumer health firms) maintain power through branded trust, broad retail distribution, and marketing scale. Their primary advantage is brand equity in OTC channels and strong relationships with retailers and wholesalers.
- Large generics and specialty pharma provide cost competitiveness and scale for both OTC and prescription segments. Their playbook centers on manufacturing efficiency and breadth of dosage forms.
- API and CDMO suppliers are strategic counter‑parties: ownership or long‑term supply agreements with major API makers materially reduce procurement risk and can protect margins.
- Platform/innovation entrants are introducing differentiated chemistries and formulations that target unmet needs (e.g., first‑in‑class non‑opioid analgesics). These entrants change the competitive equation in targeted indications, even if their initial commercial footprint is specialist and modest.
Representative companies we analyzed include legacy consumer brands, global generics manufacturers, API producers, and the new clinical entrant with an approved non‑opioid analgesic. Our competitive benchmarking evaluates go‑to‑market models, manufacturing footprints, quality incident histories, pipeline novelty, and channel strengths to reveal where advantage is concentrated. Notably, the market structure remains moderately fragmented: the top three players collectively hold less than one‑third of the market, and the top five account for roughly one‑third—creating room for both scale plays and nimble innovators.
What the full report delivers — practical, executable modules
This research is designed for corporate strategists, business unit leaders, BD teams, and private equity investors who need numbers they can act upon. Core deliverables include:
- Market sizing and CAGR models (2020–2032) with adjustable assumptions for pricing, channel mix, and substitution effects.
- Scenario analysis (regulatory stress, product recall shocks, and accelerated innovation uptake) with P&L and volume impacts translated into NPV sensitivities.
- A regulatory & safety matrix that maps upcoming label changes, recall likelihood by product class, and mitigation playbooks for market access teams.
- Competitive benchmarking dossiers for the leading global players, generics manufacturers, and API suppliers—covering strategy, capacity, quality history, and strategic options.
- M&A target screening and valuation heuristics tailored to 2026 market dynamics, including earn‑out structuring and integration risk checklists.
- Go‑to‑market playbooks for premiumization, Rx‑to‑OTC pathways, retail alliance formation, and digital channel acceleration.
- Operational toolkit: supplier risk scorecards, dual‑sourcing templates, and recall response protocols to shorten time‑to‑recovery and preserve brand trust.
We intentionally provide this overview as a strategic "trailer"—showcasing analytical depth and decision‑oriented outputs while withholding granular sub‑segment tables and full company share tables to preserve the commercial value of the full deliverable. The complete dataset and financial models are available in the full report and accompanying Excel workbook.
How to convert insight into 2026 action — recommended agenda
- Immediate (0–6 months): Run a rapid regulatory impact stress test using the report’s label‑change scenarios; prioritize risk mitigations (label claims, communication plans, and physician engagement) for actives with elevated scrutiny.
- Near term (6–12 months): Reassess supplier contracts and secure capacity through offtake or equity partnerships, focusing on minimizes single‑supplier exposure for critical APIs and finished dose manufacturing.
- Medium term (12–24 months): Execute targeted M&A or JV plays to acquire cost‑competitive API capacity or differentiated formulations; use scenario valuations from our models to size bids and structure contingent payments.
- Product strategy: Segment the portfolio into cash‑flow engines (core OTC brands), defensive investments (quality/labeling upgrades), and optionality plays (novel non‑opioid formulations or specialty Rx indications). Prioritize launches that can be protected by formulation IP or premium delivery formats.
- Commercial execution: Reinforce retail and digital channel programs to capture premiumization and convenience trends; calibrate pricing models to preserve margins in the face of rising raw‑material and compliance costs.
- Innovation & partnerships: Consider partnerships with clinical innovators or licensing of novel analgesics where internal R&D investment is not feasible—this can be the fastest route to diversify beyond legacy actives.
Closing — why PW Consulting’s report is the practical edge
For executives preparing 2026 budgets, negotiating M&A, or standing up regulatory response teams, our Antipyretic & Analgesic market study translates macro growth (historical and forecast), regulatory inflection points, and competitive posture into executable choices. The market’s steady expansion—against a backdrop of episodic regulatory and quality shocks—creates high value for disciplined, forward‑looking decisions. Our full report provides the granular tables, country and channel splits, company market shares, and downloadable modeling tools you need to operationalize strategy.
To access the complete market tables, per‑company market share assignments, and the interactive financial model that underpins the scenarios summarized above, please consult the PW Consulting report package. The full dataset is the difference between a plausible plan and a winning one in 2026.
For detailed analysis of this topic, please visit the official page: Antipyretic and Analgesic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Denatonium Benzoate Anhydrous Market to Reach USD 276.07M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-13
Denatonium Benzoate Anhydrous Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a concise yet high-fidelity preview of our latest Denatonium Benzoate Anhydrous market study. This briefing is tailored to corporate leaders, strategy teams, and investment committees preparing decisions in 2026. It demonstrates the analytical depth and operational utility of the full report while preserving the premium, segment-level intelligence that drives competitive positioning—intentionally withheld here to direct stakeholders to the full publication for transaction-grade detail.
Denatonium Benzoate Anhydrous Market
Why this market matters for 2026
- Denatonium benzoate remains the preeminent aversive agent and denaturant across a range of industrial, pharmaceutical, and consumer applications. Its unique functional role gives the product a defensive demand base even in cyclical downturns, while pockets of above-market growth arise from adjacent product innovations and regulatory shifts.
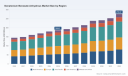
- From a macro perspective, the market demonstrates steady expansion: historical global revenues rose from USD 144.8 Million in 2020 to USD 186.61 Million in 2025. Our forecast conservatively projects continued growth across 2026–2032 at a compound annual growth rate (CAGR) of 5.8%, reaching USD 276.07 Million by 2032.
- For companies making 2026-era strategic choices—capacity expansion, vertical integration, product development, or M&A—these dynamics imply that timing, route-to-market, and product grade strategy will determine whether investments deliver premium returns or subscale exposure.
Market trajectory and the underlying drivers
The market’s historical performance (2020–2025) reflects a blend of stable base demand and selective upside from regulatory and product use-case shifts. Between 2025 and the early forecast years, the market is expected to pass the USD 190–200 Million inflection point and continue upward toward USD 276.07 Million by 2032 under baseline assumptions. Key drivers include:
Denatonium Benzoate Anhydrous Market
- Regulatory enforcement and safer‑use mandates that increase demand for aversive agents in household and industrial formulations.
- Product-grade diversification—different grades for pharmaceutical, cosmetic, and industrial applications—supporting premium pricing in specialty niches.
- Supply-side innovation, including biotechnological production routes, that can lower cost curves for select producers and enable margin expansion or aggressive pricing strategies.
- Consolidation trends among chemical suppliers, evidenced by the market’s moderate concentration metrics (CR3 ~35.4% and CR5 ~42.7%), which create opportunities for scale-driven differentiation but also preserve space for agile niche players.
What this means for 2026 corporate strategy
Decisions made in 2026 will be shaped by the market’s transition from recovery to structural growth. Executives should prioritize three pillars:
Denatonium Benzoate Anhydrous Market
- Portfolio granularity: Different end‑use grades and formats (powders, granules, specialty preparations) have materially different margin profiles and regulatory footprints. Strategic focus should be on aligning product‑grade mix to the company’s distribution strength and regulatory capabilities.
- Supply resilience: With limited global concentration at the top, buyers can pursue dual‑sourcing, backward integration, or strategic partnerships to secure continuity and negotiate more favorable cost terms as volumes grow.
- Regulatory and go‑to‑market agility: Regulatory shifts can rapidly change demand patterns. Firms that embed regulatory intelligence and rapid reformulation/customization into their launch processes will capture share from slower incumbents.
Report contents — practical tools included
The full PW Consulting report (base year 2025; historical coverage 2020–2025; forecast horizon 2026–2032) is engineered for operational decision-making. Highlights include:
- Top‑line and price forecasts (USD Million), including year-by-year market sizing and baseline/alternative scenarios calibrated to raw material, regulatory, and demand shocks.
- Demand drivers matrix linking end‑use markets to adoption levers and sensitivity analyses designed for scenario planning.
- Supply‑side model mapping global capacity, technology routes (including biotech manufacturing), lead times, and cost benchmarks to identify bottlenecks and margin pools.
- Commercial playbooks: go‑to‑market strategies for manufacturers, distributors, and private label players, with checklists for quality/grade certification, labeling, and regulatory dossiers.
- Valuation and transaction support: M&A screening rubric, target scorecards, and synergy templates for bolt‑on and platform deals.
- Supplier evaluation and a procurement negotiation toolkit—practical templates and KPIs to improve purchasing outcomes and secure supply resilience.
Note: this preview intentionally omits segment-level numerical splits (regional, application, and type percentages/values). Those granular tables and proprietary scorecards are proprietary to the full report and remain essential for executional decisions.
Competitive landscape — who matters and why
The competitive set is balanced between established global players and specialized regional manufacturers and distributors. The structure (CR3 ~35.4%, CR5 ~42.7%) suggests moderate concentration: market leadership exists but does not preclude competition from nimble or specialized entrants.
- Johnson Matthey (London, UK) — Operating under an internationally recognized brand, their Bitrex product is the reference standard for bitterness and denaturation. Their incumbent position is strengthened by brand recognition, integrated quality systems, and established distribution into regulated markets. Strategic implications: competitors must either differentiate on cost, specialty grades, or service to displace such incumbents in regulated accounts.
- Haihang Industry (Jinan, China) — A producer focused on CAS‑specified material for pharmaceutical and industrial applications. Their scale and local supply chain advantages make them a natural partner for price‑sensitive or volume buyers seeking reliability in Asian supply chains.
- Zhejiang Synose Tech (Jinhua, China) — Manufactures multiple pharmacopoeia‑grade variants for cosmetics and pharmaceuticals. Strength lies in regulatory compliance capabilities and diversified grade offerings, attractive to customers requiring certified materials.
- Zhengzhou Beth Food Additive (Zhengzhou, China) — Positions the product in food‑adjacent and additive markets, exploiting formulators who need food‑grade or food‑adjacent bittering agents.
- ECSA Chemicals (Lausanne, Switzerland) — A distributor specializing in bulk formats and logistics to European markets; valuable for manufacturers or buyers who lack direct importing footprints and need secure supply in premium markets.
- Shanxi Laike Bio‑Engineering (Shanxi, China) — Represents an alternative production route via biotech processes. If their commercially scalable processes reduce cost or environmental footprint, they could be a disruptive force in selected niches.
Collectively, these players illustrate the different competitive vectors: brand/quality leadership, low‑cost scale supply, regulatory compliance for sensitive end‑uses, distribution/logistics specialization, and process innovation. For decision-makers in 2026, the critical task is to map where your firm sits along these vectors and to choose a compensating strategy — e.g., premiumization, cost leadership, channel control, or technology differentiation.
Investment, M&A and partnership opportunities
Given the market’s steady CAGR of 5.8% and the forecast trajectory into 2032, the market is attractive for targeted investments rather than broad, undifferentiated plays. Practical opportunities include:
- Acquiring regional or specialty producers to secure grade diversity and shorten time‑to‑market for regulated customers.
- Partnering with biotech producers to pilot lower‑cost or greener production routes that can be scaled selectively for margin improvement.
- Investing in downstream formulation capabilities (e.g., premixed denaturants or custom blends) to capture higher value in customer supply chains.
Risks and regulatory considerations
While demand fundamentals are supportive, three risk vectors require active mitigation in 2026 planning:
- Regulatory shifts: Changes in denaturant approvals or labeling standards can rapidly re‑segment demand. Maintain a regulatory watchlist and contingency reformulation budget.
- Raw material volatility: Price shocks in feedstocks or energy can compress margins; long‑term contracts or hedging strategies should be evaluated.
- Quality and certification risk: For pharmaceutical and cosmetic customers, lapses in certification can result in lost contracts. Investment in quality systems is non‑optional for suppliers targeting premium channels.
How to use this preview and next steps
This brief demonstrates the strategic insights available in the full PW Consulting Denatonium Benzoate Anhydrous Market report, which provides the granular, transaction‑grade analysis required for 2026 decision-making: full regional and application-level forecasts, supplier scorecards, price modeling, and M&A screening templates. The full dataset enables precise scenario modeling (e.g., incremental capacity vs. demand sensitivity), which is essential for capital allocation and negotiation strategies.
For leadership teams preparing budgets, CAPEX proposals, or acquisition mandates in 2026, the two immediate actions we recommend are:
- Commission the full report to obtain the segment-level tables and supplier scorecards needed to run investment return simulations and procurement negotiations.
- Use the report’s supply model and commercial playbooks to stress‑test your current supplier base and identify immediate quick‑wins (dual sourcing, grade rationalization, or channel consolidation) that improve resilience and margins within 6–12 months.
Closing
Denatonium benzoate anhydrous sits at the intersection of regulatory necessity and niche performance chemistry. Our analysis shows a market that is predictable at the macro level but rich in micro opportunities and risks—exactly the environment where disciplined strategy, operational execution, and targeted investments create disproportionate value. To convert these insights into executable plans for 2026, PW Consulting’s full report and accompanying models are the necessary next step.
For detailed analysis of this topic, please visit the official page: Denatonium Benzoate Anhydrous Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Print-On-Demand Software Market Poised for 31.1% CAGR Through 2032
By pmarketresearch, 2026-07-13
Print On Demand Software Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our flagship market research on the Print On Demand (POD) Software market. This article synthesizes the report’s most consequential insights for executives planning capital allocation, product roadmaps, or M&A strategies in 2026 — while preserving the detailed segment-level intelligence available in the full study.
Print On Demand Software Market
Why this research matters for 2026
-
Rapid adoption windows: The POD software market is moving from niche automation projects into enterprise-grade workflows. Companies that lock in integrations and fulfillment partnerships in 2026 will enjoy durable advantages as the market scales.
Print On Demand Software Market -
Strategic inflection point: Our base year is 2025, and the near-term horizon (2026–2032) frames decisions on capacity, platform architecture, and channel expansion that determine market leadership.
Print On Demand Software Market -
Regulatory and cost pressure: New privacy requirements and evolving cloud licensing practices mean that TCO and contract design are now as strategic as feature parity.
Market trajectory — headline macro picture
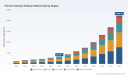
The POD software market has experienced rapid expansion through 2025, growing from roughly $1.3 billion (2020) to about $3.3 billion in our base year, 2025. Our forecast projects that investment and adoption will accelerate meaningfully in 2026 and beyond — with the market expanding to roughly $4.4 billion in 2026 and on a path to exceed $22 billion by 2032. That growth implies a compound annual growth rate of approximately 31.1% across the forecast window.
What these headline numbers tell us: this is not incremental software substitution. Buyers are consolidating multiple functions — storefront orchestration, automated SKU generation, order routing, production scheduling, and fulfillment — into platform-level investments. The pace of adoption and the scale of the opportunity justify strategic bets in 2026, but the timing and structure of those bets will materially influence competitive outcomes.
Key market dynamics shaping 2026 choices
-
Shift from point tools to composable platforms — Buyers increasingly expect POD platforms to operate as orchestration layers that manage third‑party printers, multiple fulfillment partners, logistics providers and storefronts via robust APIs and event-driven automation. Integration capability is the new table stake.
-
Fulfillment density and distributed production — The economics of POD are driven by proximity to consumer and inventory-lite models. Software that optimizes routing across a distributed fulfillment network adds immediate margin and delivery-time advantages.
-
Automation wins on unit economics — End-to-end automation (from design templates and mockups to print-ready file validation and shipping labels) reduces manual touchpoints and labor exposure — a critical lever as labor rules and privacy laws change in 2026.
-
Regulatory & procurement pressures — Emerging state privacy laws now require data protection assessments for automated processing, while federal and enterprise buyers face new cloud licensing and vendor-surcharge practices that increase the effective cost of integrated cloud workflows. Platform architecture and contracting sophistication are therefore central to procurement decisions.
-
Specialized verticalization — Successful vendors will pair core POD orchestration with domain IP — e.g., textile DTG workflows, decorator network management, or brand-storefront experiences — to justify pricing and reduce churn.
Competitive landscape — strategic positioning of core providers
The competitive field is heterogeneous: established print-technology companies, agile SaaS orchestration providers, and free or open-entry solutions co-exist. Below are concise strategic takeaways on representative vendors covered in the study.
-
Fulfill Engine (United States): Positions as an all-in-one platform with deep API connectivity, white-label storefront capabilities, and automation for production and fulfillment across e‑commerce and decorator networks. Strategic edge: orchestration-first product design that targets enterprise partners and multi-operator ecosystems. Consideration for buyers: evaluate long-term integration and revenue-sharing terms to avoid lock-in.
-
MPODx (United States): Focuses on automating product creation, order fulfillment, packaging and shipping directly via e-commerce integrations. Strategic edge: simplicity and automation for SMB-to-midmarket merchants. Consideration: assess scalability of fulfillment routing logic and quality-control workflows for higher-volume enterprise deployments.
-
Kornit Digital / KornitX (Israel): Brings an end-to-end offering tailored to digital textile printing, combining SaaS workflow with a global fulfillment network and on-demand production for apparel. Strategic edge: vertical specialization in textile DTG with integrated hardware partnerships. Consideration: firms needing cross-category flexibility should weigh KornitX’s deep apparel workflows against more horizontal orchestration platforms.
-
Durst Software & Solutions (Italy): Optimizes web-to-print and POD for smart print factories and high-volume automated production. Strategic edge: industrial-grade production planning and integration with high-throughput presses. Consideration: best fit for partners focused on scaling factory automation rather than consumer storefront features.
-
MarketPrint (Germany): Offers a free POD software entry point for online shop operators emphasizing order processing, automated printing workflows and UX optimization. Strategic edge: low-cost adoption funnel and rapid time-to-live for merchants. Consideration: monetization and enterprise-readiness vary; evaluate support and SLA provisions for mission-critical operations.
-
PrintNow (United States): Delivers web-to-print storefronts with dynamic pricing, product customization, and integration to 140+ fulfillment partners. Strategic edge: broad partner network and retail-ready storefront features. Consideration: vendor performance across the partner network is heterogeneous; governance tooling and SLAs are differentiators.
Recent market moves highlight how these strengths convert to scale. A notable April 2026 partnership expanded Durst’s reach into MENA markets via a regional integrator, signaling that localized e-commerce and regulatory expertise is a decisive factor for geographic expansion. Similarly, an expanded collaboration in early 2025 between a leading fulfillment operator and a textile-printing hardware provider demonstrates that capacity investments (e.g., fleet deployments of high‑speed DTG systems) are being paired with software orchestration to win share.
Implications for buyers and investors in 2026
-
Negotiate contract levers that align incentives — As cloud licensing practices and vendor pricing models shift, buyers should build true TCO models that include licensing surcharges, integration lift, and ongoing vendor migration costs. Consider outcome-based pricing where feasible.
-
Prioritize modularity and data governance — With new privacy assessment obligations, prefer architectures that allow for regional data segmentation, robust logging, and clear vendor security attestations.
-
Target pilot-to-scale pathways — Run two parallel pilots: one to validate integration and unit economics with local fulfillment partners, and another to stress-test peak volumes and edge-case returns workflows. The ability to reach scale quickly separates winners from also-rans.
-
Account for labor and skill shifts — Automation will reduce repetitive roles but raise demand for cloud-integration engineers, data-protection officers, and fulfillment orchestration specialists. Plan for reskilling and selective outsourcing.
-
Consider M&A as an acceleration tool — For incumbents, acquiring orchestration or fulfillment-network capabilities can shorten time-to-market and lock in partner exclusivity. For investors, software firms with proven workflows and partner pipelines are high-conviction targets.
What the full PW Consulting report delivers (operational view)
This research is designed to be immediately actionable for strategy, procurement, product, and M&A teams. Key deliverables include:
-
Proprietary market-sizing models (historical 2020–2025 and base-year 2025 validation) and scenario-based forecasts through 2032.
-
Vendor scorecards and capability matrices aligned to buyer archetypes (enterprise brands, platform partners, fulfillment networks, and SMB marketplaces).
-
Integration playbooks for API-first architectures, event-driven order routing, and multi‑print-farm orchestration.
-
Commercial negotiation templates that neutralize cloud-surcharge exposures and clarify TCO levers.
-
RFP checklists and technical acceptance criteria for proofs-of-concept and pilot-to-scale transitions.
-
Scenario planning modules exploring alternative futures (e.g., accelerated regionalization, hardware-backed vertical consolidation, the impact of stricter privacy regimes).
How to use this research in 90 days
-
30 days — Use the vendor scorecards and RFP checklist to shortlist 2–3 platform partners and run aligned pilot charters with clear success metrics.
-
60 days — Execute integration sprints and validate routing, SLA adherence, and cost-per-order baselines; stress-test privacy and export controls.
-
90 days — Make a go/no-go decision on platform roll-out, finalize commercial terms that include migration rights, and begin capacity alignment with fulfillment partners for a Q4 scaling window.
Final perspective
The Print On Demand software market presents a rare combination of rapid growth, structural demand for orchestration, and a window where integration and commercial design meaningfully determine competitive advantage. With a projected CAGR north of 30% through 2032 and a market that moves from billions into the tens of billions in the coming years, 2026 is the year to convert exploratory budgets into strategic commitments — but to do so with disciplined contracting, modular architectures, and network-aware product strategies.
For executives seeking the complete dataset, vendor-by-vendor scoring, and the executable playbooks referenced here, the full PW Consulting Print On Demand Software Market report provides the models and appendices necessary to operationalize these insights. Access to the full report and supporting deliverables is available via our research portal.
For detailed analysis of this topic, please visit the official page: Print On Demand Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com