

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Print-On-Demand Software Market Poised for 31.1% CAGR Through 2032

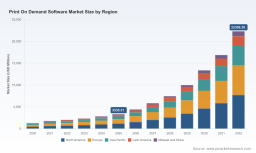
Print On Demand Software Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our flagship market research on the Print On Demand (POD) Software market. This article synthesizes the report’s most consequential insights for executives planning capital allocation, product roadmaps, or M&A strategies in 2026 — while preserving the detailed segment-level intelligence available in the full study.
Print On Demand Software Market
Why this research matters for 2026
-
Rapid adoption windows: The POD software market is moving from niche automation projects into enterprise-grade workflows. Companies that lock in integrations and fulfillment partnerships in 2026 will enjoy durable advantages as the market scales.
Print On Demand Software Market -
Strategic inflection point: Our base year is 2025, and the near-term horizon (2026–2032) frames decisions on capacity, platform architecture, and channel expansion that determine market leadership.
Print On Demand Software Market -
Regulatory and cost pressure: New privacy requirements and evolving cloud licensing practices mean that TCO and contract design are now as strategic as feature parity.
Market trajectory — headline macro picture
The POD software market has experienced rapid expansion through 2025, growing from roughly $1.3 billion (2020) to about $3.3 billion in our base year, 2025. Our forecast projects that investment and adoption will accelerate meaningfully in 2026 and beyond — with the market expanding to roughly $4.4 billion in 2026 and on a path to exceed $22 billion by 2032. That growth implies a compound annual growth rate of approximately 31.1% across the forecast window.
What these headline numbers tell us: this is not incremental software substitution. Buyers are consolidating multiple functions — storefront orchestration, automated SKU generation, order routing, production scheduling, and fulfillment — into platform-level investments. The pace of adoption and the scale of the opportunity justify strategic bets in 2026, but the timing and structure of those bets will materially influence competitive outcomes.
Key market dynamics shaping 2026 choices
-
Shift from point tools to composable platforms — Buyers increasingly expect POD platforms to operate as orchestration layers that manage third‑party printers, multiple fulfillment partners, logistics providers and storefronts via robust APIs and event-driven automation. Integration capability is the new table stake.
-
Fulfillment density and distributed production — The economics of POD are driven by proximity to consumer and inventory-lite models. Software that optimizes routing across a distributed fulfillment network adds immediate margin and delivery-time advantages.
-
Automation wins on unit economics — End-to-end automation (from design templates and mockups to print-ready file validation and shipping labels) reduces manual touchpoints and labor exposure — a critical lever as labor rules and privacy laws change in 2026.
-
Regulatory & procurement pressures — Emerging state privacy laws now require data protection assessments for automated processing, while federal and enterprise buyers face new cloud licensing and vendor-surcharge practices that increase the effective cost of integrated cloud workflows. Platform architecture and contracting sophistication are therefore central to procurement decisions.
-
Specialized verticalization — Successful vendors will pair core POD orchestration with domain IP — e.g., textile DTG workflows, decorator network management, or brand-storefront experiences — to justify pricing and reduce churn.
Competitive landscape — strategic positioning of core providers
The competitive field is heterogeneous: established print-technology companies, agile SaaS orchestration providers, and free or open-entry solutions co-exist. Below are concise strategic takeaways on representative vendors covered in the study.
-
Fulfill Engine (United States): Positions as an all-in-one platform with deep API connectivity, white-label storefront capabilities, and automation for production and fulfillment across e‑commerce and decorator networks. Strategic edge: orchestration-first product design that targets enterprise partners and multi-operator ecosystems. Consideration for buyers: evaluate long-term integration and revenue-sharing terms to avoid lock-in.
-
MPODx (United States): Focuses on automating product creation, order fulfillment, packaging and shipping directly via e-commerce integrations. Strategic edge: simplicity and automation for SMB-to-midmarket merchants. Consideration: assess scalability of fulfillment routing logic and quality-control workflows for higher-volume enterprise deployments.
-
Kornit Digital / KornitX (Israel): Brings an end-to-end offering tailored to digital textile printing, combining SaaS workflow with a global fulfillment network and on-demand production for apparel. Strategic edge: vertical specialization in textile DTG with integrated hardware partnerships. Consideration: firms needing cross-category flexibility should weigh KornitX’s deep apparel workflows against more horizontal orchestration platforms.
-
Durst Software & Solutions (Italy): Optimizes web-to-print and POD for smart print factories and high-volume automated production. Strategic edge: industrial-grade production planning and integration with high-throughput presses. Consideration: best fit for partners focused on scaling factory automation rather than consumer storefront features.
-
MarketPrint (Germany): Offers a free POD software entry point for online shop operators emphasizing order processing, automated printing workflows and UX optimization. Strategic edge: low-cost adoption funnel and rapid time-to-live for merchants. Consideration: monetization and enterprise-readiness vary; evaluate support and SLA provisions for mission-critical operations.
-
PrintNow (United States): Delivers web-to-print storefronts with dynamic pricing, product customization, and integration to 140+ fulfillment partners. Strategic edge: broad partner network and retail-ready storefront features. Consideration: vendor performance across the partner network is heterogeneous; governance tooling and SLAs are differentiators.
Recent market moves highlight how these strengths convert to scale. A notable April 2026 partnership expanded Durst’s reach into MENA markets via a regional integrator, signaling that localized e-commerce and regulatory expertise is a decisive factor for geographic expansion. Similarly, an expanded collaboration in early 2025 between a leading fulfillment operator and a textile-printing hardware provider demonstrates that capacity investments (e.g., fleet deployments of high‑speed DTG systems) are being paired with software orchestration to win share.
Implications for buyers and investors in 2026
-
Negotiate contract levers that align incentives — As cloud licensing practices and vendor pricing models shift, buyers should build true TCO models that include licensing surcharges, integration lift, and ongoing vendor migration costs. Consider outcome-based pricing where feasible.
-
Prioritize modularity and data governance — With new privacy assessment obligations, prefer architectures that allow for regional data segmentation, robust logging, and clear vendor security attestations.
-
Target pilot-to-scale pathways — Run two parallel pilots: one to validate integration and unit economics with local fulfillment partners, and another to stress-test peak volumes and edge-case returns workflows. The ability to reach scale quickly separates winners from also-rans.
-
Account for labor and skill shifts — Automation will reduce repetitive roles but raise demand for cloud-integration engineers, data-protection officers, and fulfillment orchestration specialists. Plan for reskilling and selective outsourcing.
-
Consider M&A as an acceleration tool — For incumbents, acquiring orchestration or fulfillment-network capabilities can shorten time-to-market and lock in partner exclusivity. For investors, software firms with proven workflows and partner pipelines are high-conviction targets.
What the full PW Consulting report delivers (operational view)
This research is designed to be immediately actionable for strategy, procurement, product, and M&A teams. Key deliverables include:
-
Proprietary market-sizing models (historical 2020–2025 and base-year 2025 validation) and scenario-based forecasts through 2032.
-
Vendor scorecards and capability matrices aligned to buyer archetypes (enterprise brands, platform partners, fulfillment networks, and SMB marketplaces).
-
Integration playbooks for API-first architectures, event-driven order routing, and multi‑print-farm orchestration.
-
Commercial negotiation templates that neutralize cloud-surcharge exposures and clarify TCO levers.
-
RFP checklists and technical acceptance criteria for proofs-of-concept and pilot-to-scale transitions.
-
Scenario planning modules exploring alternative futures (e.g., accelerated regionalization, hardware-backed vertical consolidation, the impact of stricter privacy regimes).
How to use this research in 90 days
-
30 days — Use the vendor scorecards and RFP checklist to shortlist 2–3 platform partners and run aligned pilot charters with clear success metrics.
-
60 days — Execute integration sprints and validate routing, SLA adherence, and cost-per-order baselines; stress-test privacy and export controls.
-
90 days — Make a go/no-go decision on platform roll-out, finalize commercial terms that include migration rights, and begin capacity alignment with fulfillment partners for a Q4 scaling window.
Final perspective
The Print On Demand software market presents a rare combination of rapid growth, structural demand for orchestration, and a window where integration and commercial design meaningfully determine competitive advantage. With a projected CAGR north of 30% through 2032 and a market that moves from billions into the tens of billions in the coming years, 2026 is the year to convert exploratory budgets into strategic commitments — but to do so with disciplined contracting, modular architectures, and network-aware product strategies.
For executives seeking the complete dataset, vendor-by-vendor scoring, and the executable playbooks referenced here, the full PW Consulting Print On Demand Software Market report provides the models and appendices necessary to operationalize these insights. Access to the full report and supporting deliverables is available via our research portal.
For detailed analysis of this topic, please visit the official page: Print On Demand Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com