

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Keratin Market to Expand at 6.8% CAGR

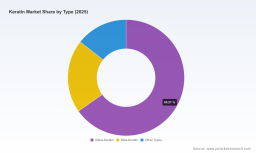
Keratin Market 2026 Strategic Preview — A PW Consulting Industry Brief
As companies prepare strategic plans and capital allocations for 2026, the keratin market presents a distinctive combination of steady macro growth, concentrated supplier power, and accelerating technological and regulatory disruption. This brief synthesizes the most consequential signals from PW Consulting’s full Keratin Market Report (base year 2025) to help senior executives, product leaders, and investment committees frame decisions that capture upside while limiting downside. Consider this a high-quality trailer: rigorous, source-backed insight designed to inform your agenda-setting — with the complete datasets, segment tables and scenario models reserved for the full report.
Keratin Market
Market at a Glance: Growth Trajectory and Structural Context
Our market model, anchored on a 2025 base year (USD, revenue unit: Million), documents a clear recovery and re-acceleration phase across 2020–2025 and projects continued expansion through 2032. After rising from a mid-single-thousand-million base in 2020 to a 2025 valuation used as the report’s reference point, the keratin market is expected to grow at a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. Under the central scenario, this trajectory implies meaningful incremental demand across personal care, therapeutic wound care, and adjacent nutraceutical and food applications.
Keratin Market
Competitive structure is moderately concentrated: the top three suppliers account for a meaningful share of global revenues, and the top five further increase concentration—conditions that create both defensive advantages for incumbents and entry points for well-capitalized challengers with differentiated technology, sustainable sourcing, or regulatory-savvy go-to-market strategies.
Keratin Market
Why 2026 Is a Strategic Inflection Point
-
Demand maturation in high-value applications: Personal care remains the primary commercial engine, but higher-margin therapeutic and medical uses (advanced wound care, nutraceutical formulations) are scaling faster as clinical validation and reimbursement pathways mature.
-
Shift from commodity to specialty: Buyers increasingly prize traceability, claim substantiation, and functional performance (peptide engineering, controlled hydrolysis profiles). Suppliers that can couple raw-ingredient economics with technical service will capture disproportionate value.
-
Regulatory tightening and consumer scrutiny: Updated safety guidance and chemical restrictions require proactive reformulation, transparent labeling, and more robust tamper-proof safety data — all of which raise the bar for compliance and accelerate consolidation among suppliers who can meet stricter standards.
Regulatory and Policy Dynamics — Practical Implications
Two regulatory developments are especially material for 2026 planning. First, updated safety guidance on heat-activated hair smoothing products has raised liability and labeling requirements for formulations that may emit aldehydes under intended use. Second, jurisdictional bans on certain formaldehyde-releasing chemistries (enacted at state levels) have tightened formulation windows for traditional keratin hair treatments.
Strategic response options we recommend to clients:
-
Immediate compliance triage: map existing SKUs against the guidance, identify at-risk products, and prioritize reformulation or withdrawal pathways.
-
Labeling and claims governance: anticipate more conservative claims substantiation and invest in standardized safety testing and consumer-facing transparency (e.g., sourcing certificates, third-party verification).
-
Regulatory scenario planning: build adaptive product roadmaps that allow rapid substitution of at-risk chemistries without disrupting commercial channels.
Competition and Recent Developments — What Matters to Buyers and Investors
Our competitive scan focuses both on legacy chemical majors and specialist ingredient houses. Two exemplars illustrate the strategic polarity in the industry:
-
Keraplast (Christchurch, New Zealand) — a specialist producer that leverages regeneratively sourced sheep wool to deliver high-performance keratin ingredients and peptides across personal care, nutraceutical, and wound care markets. Keraplast’s recent exclusive manufacturing agreement with a wound-care partner demonstrates how targeted partnerships can accelerate clinical and commercial scale-up in therapeutic niches.
-
BASF SE (Ludwigshafen, Germany) — a diversified chemical leader that is intensifying its play in natural-based personal care inputs, as evidenced by product innovations focused on sustainability-derived polymers and betaine alternatives. Such moves underscore a broader trend: major suppliers are de-risking portfolios toward sustainable feedstocks and lighter claim sets that align with consumer and regulatory demand.
For strategists, the takeaway is twofold: (1) specialist producers can command premium value through provenance, formulation support, and clinical positioning; (2) large suppliers bring scale, procurement heft, and route-to-market breadth, and they are moving rapidly to occupy the sustainable-ingredient premium.
Technology and Innovation Themes to Watch in 2026
-
Bioprocessing and peptide precision: advances in controlled hydrolysis and peptide fractionation are enabling differentiated functional profiles for hair repair and wound-healing applications.
-
Alternative sourcing: regenerative livestock sourcing, feather and byproduct valorization, and early-stage microbial fermentation approaches are reshaping input risk and sustainability narratives.
-
Formulation adjacencies: convergence with natural polymer innovation (lightweight styling polymers, betaines from sustainable oils) is creating integrated ingredient suites that reduce formulation complexity for OEMs.
Commercial and M&A Playbook for 2026
Our analysis identifies five practical strategic moves that should be considered this year:
-
Portfolio triage: segment products into defend, refactor, and retire categories based on regulatory risk, margin profile, and growth trajectory — allocate R&D resources accordingly.
-
Partnership-first scale-up: where clinical or regulatory validation is required (e.g., wound care), partner with contract manufacturers or specialist OEMs to accelerate commercialization while containing capital outlay.
-
Targeted M&A and bolt-ons: prioritize acquisitions that fill upstream traceability gaps (sustainable raw-material controls), add peptide engineering capability, or provide immediate access to regulated medical channels.
-
Pricing and contract redesign: implement indexing and pass-through mechanisms for spikes in input costs, and negotiate longer-duration offtake contracts with key raw-material suppliers to stabilize supply.
-
Brand and claims defensibility: invest in clinical endpoints and third-party verification to protect premium price points and expedite payer acceptance in healthcare segments.
Report Deliverables — What You’ll Find in the Full PW Consulting Keratin Report
The full study contains the operating model and granular intelligence needed to execute the playbook above, including:
- Proprietary market-sizing model (historical 2020–2025; forecast 2026–2032) with scenario toggles and sensitivity analyses.
- Competitive profiles and strategic positioning maps for incumbent and emerging suppliers.
- Regulatory matrix and red-team assessments of jurisdictional risks.
- Technology tracker covering sourcing, processing, and formulation innovations.
- Commercial heat maps and go-to-market playbooks by channel and use case.
- M&A screening framework and a prioritized target list based on strategic fit and integration complexity.
To preserve commercial value and drive direct engagement, detailed segment breakouts (regional, by type, by application) and the downloadable model are available exclusively through the PW Consulting report portal.
Practical Next Steps for 2026 Decision-Makers
-
Immediate (0–3 months): commission a regulatory exposure audit of your keratin-containing SKUs; validate supplier documentation and perform a claims risk review.
-
Near-term (3–9 months): run scenario tests using our market model to inform 2026 budget allocations for R&D, capacity, and strategic partnerships; prioritize one or two pilot reformulations to mitigate regulatory exposure.
-
Medium-term (9–18 months): pursue strategic supply agreements or bolt-on M&A to secure raw-material traceability, peptide engineering capability, or medical-channel access.
Concluding Perspective
The keratin market in 2026 sits at the intersection of robust demand growth — underpinned by personal care and therapeutic applications — and an evolving regulatory and sustainability landscape that penalizes inaction. Our central forecast shows continued expansion at a mid-single-digit CAGR, creating attractive returns for firms that can combine technical differentiation with regulatory foresight and supply-chain resilience. At the same time, moderate market concentration signals an opening for focused entrants that offer provenance, clinical validation, or cost-effective alternatives.
PW Consulting’s full Keratin Market Report delivers the quantitative backbone and qualitative insight to turn these signals into executable strategies. For access to the detailed segment tables, the full financial model, and bespoke advisory options to support 2026 planning, please consult the PW Consulting report access page or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Keratin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com