

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Antipyretic & Analgesic Market to Reach USD 70.62 Million by 2032

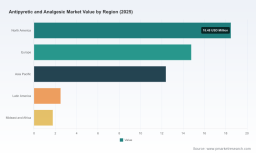
Antipyretic & Analgesic Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market intelligence on the Antipyretic & Analgesic sector uses 2025 as the base year and examines historical trends from 2020–2025, with a forward-looking forecast covering 2026–2032. The global market demonstrated steady expansion through the 2020s, rising from under USD 40 million (2020) to roughly USD 50 million in 2025, and our modeling projects continued growth to an estimated market size north of USD 70 million by 2032 under a mid‑case trajectory. This path reflects a compounded annual growth rate (CAGR) for the forecast period of approximately 5.09%.
Antipyretic and Analgesic Market
For senior executives evaluating resource allocation, portfolio moves, or M&A activity in 2026, these headline dynamics signal a market that is mature but still offers pockets of profitable expansion—provided companies align strategy to regulatory risk, supply‑chain realities, and emergent clinical and product innovation.
Antipyretic and Analgesic Market
Why this intelligence matters for 2026 corporate strategy
- Timing capital and M&A moves: With a mid‑single digit CAGR and an uneven growth runway across product forms and channels, 2026 is a window to consolidate assets, selectively acquire API/finished-dose capacity, or invest in differentiated formulations ahead of expected demand inflection points.
- Regulatory and quality risk management: High‑visibility recalls and label initiatives in 2025–2026 elevate regulatory premium; proactive remediation, labeling strategies, and physician outreach programs will materially affect market access and brand trust.
- Portfolio prioritization: Companies must decide whether to double down on established mass‑market OTC brands, pursue Rx‑to‑OTC switches, or invest in differentiated non‑opioid analgesics that can command premium positioning.
- Supply‑chain and manufacturing decisions: API capacity moves and episodic contamination recalls underscore the need for dual sourcing, regional manufacturing footprints, and supplier oversight as core to continuity and cost control.
Market dynamics shaping 2026 strategy
The Antipyretic & Analgesic market is being pulled in three directions simultaneously: steady baseline demand for symptomatic fever and pain relief; selective premiumization and formulation innovation; and episodic regulatory and safety shocks that reallocate demand and create short‑run volatility.
Antipyretic and Analgesic Market
- Growth fundamentals: Demographic trends, greater OTC self‑care adoption in emerging markets, and a continued focus on non‑opioid pain management sustain baseline expansion. The overall market trajectory to 2032 embodies these structural tailwinds while remaining sensitive to regulatory signals.
- Regulatory headwinds: A notable 2025–2026 development is the initiation of label review processes by the US regulator for acetaminophen products following safety communications. Label adjustments and physician advisories can depress demand in sensitive sub‑segments and shift prescribing behavior; companies should prepare for phased impacts rather than an immediate demand collapse.
- Quality and recall shocks: Recent class II recalls involving acetaminophen and naproxen formulations (late 2025 and mid‑2026) highlight persistent execution risk in packaging and chemical control. These events produce short‑term market share swings and long‑term reputational effects, emphasizing the importance of end‑to‑end quality systems and rapid crisis communication playbooks.
- Supply‑side capacity: Strategic investments by major chemical suppliers to expand API capacity—particularly for widely used actives—have materially improved supply stability since the early 2020s. Firms that secure offtake agreements or co‑invest in capacity gain a measurable competitive cost and reliability advantage.
- Innovation pressure: The approval of a first‑in‑class non‑opioid oral analgesic in early 2025 introduces a new competitive axis: novel mechanisms that can displace legacy actives in moderate‑to‑severe pain indications. This shifts the R&D calculus for incumbents: defend, partner, or pivot.
Competitive landscape — mapped for action
We mapped the competitive set across four archetypes—global consumer health brands, generics manufacturers, API producers, and platform innovators—and profiled a set of incumbent and emergent players critical to 2026 planning:
- Global consumer health leaders (e.g., large established CPG/consumer health firms) maintain power through branded trust, broad retail distribution, and marketing scale. Their primary advantage is brand equity in OTC channels and strong relationships with retailers and wholesalers.
- Large generics and specialty pharma provide cost competitiveness and scale for both OTC and prescription segments. Their playbook centers on manufacturing efficiency and breadth of dosage forms.
- API and CDMO suppliers are strategic counter‑parties: ownership or long‑term supply agreements with major API makers materially reduce procurement risk and can protect margins.
- Platform/innovation entrants are introducing differentiated chemistries and formulations that target unmet needs (e.g., first‑in‑class non‑opioid analgesics). These entrants change the competitive equation in targeted indications, even if their initial commercial footprint is specialist and modest.
Representative companies we analyzed include legacy consumer brands, global generics manufacturers, API producers, and the new clinical entrant with an approved non‑opioid analgesic. Our competitive benchmarking evaluates go‑to‑market models, manufacturing footprints, quality incident histories, pipeline novelty, and channel strengths to reveal where advantage is concentrated. Notably, the market structure remains moderately fragmented: the top three players collectively hold less than one‑third of the market, and the top five account for roughly one‑third—creating room for both scale plays and nimble innovators.
What the full report delivers — practical, executable modules
This research is designed for corporate strategists, business unit leaders, BD teams, and private equity investors who need numbers they can act upon. Core deliverables include:
- Market sizing and CAGR models (2020–2032) with adjustable assumptions for pricing, channel mix, and substitution effects.
- Scenario analysis (regulatory stress, product recall shocks, and accelerated innovation uptake) with P&L and volume impacts translated into NPV sensitivities.
- A regulatory & safety matrix that maps upcoming label changes, recall likelihood by product class, and mitigation playbooks for market access teams.
- Competitive benchmarking dossiers for the leading global players, generics manufacturers, and API suppliers—covering strategy, capacity, quality history, and strategic options.
- M&A target screening and valuation heuristics tailored to 2026 market dynamics, including earn‑out structuring and integration risk checklists.
- Go‑to‑market playbooks for premiumization, Rx‑to‑OTC pathways, retail alliance formation, and digital channel acceleration.
- Operational toolkit: supplier risk scorecards, dual‑sourcing templates, and recall response protocols to shorten time‑to‑recovery and preserve brand trust.
We intentionally provide this overview as a strategic "trailer"—showcasing analytical depth and decision‑oriented outputs while withholding granular sub‑segment tables and full company share tables to preserve the commercial value of the full deliverable. The complete dataset and financial models are available in the full report and accompanying Excel workbook.
How to convert insight into 2026 action — recommended agenda
- Immediate (0–6 months): Run a rapid regulatory impact stress test using the report’s label‑change scenarios; prioritize risk mitigations (label claims, communication plans, and physician engagement) for actives with elevated scrutiny.
- Near term (6–12 months): Reassess supplier contracts and secure capacity through offtake or equity partnerships, focusing on minimizes single‑supplier exposure for critical APIs and finished dose manufacturing.
- Medium term (12–24 months): Execute targeted M&A or JV plays to acquire cost‑competitive API capacity or differentiated formulations; use scenario valuations from our models to size bids and structure contingent payments.
- Product strategy: Segment the portfolio into cash‑flow engines (core OTC brands), defensive investments (quality/labeling upgrades), and optionality plays (novel non‑opioid formulations or specialty Rx indications). Prioritize launches that can be protected by formulation IP or premium delivery formats.
- Commercial execution: Reinforce retail and digital channel programs to capture premiumization and convenience trends; calibrate pricing models to preserve margins in the face of rising raw‑material and compliance costs.
- Innovation & partnerships: Consider partnerships with clinical innovators or licensing of novel analgesics where internal R&D investment is not feasible—this can be the fastest route to diversify beyond legacy actives.
Closing — why PW Consulting’s report is the practical edge
For executives preparing 2026 budgets, negotiating M&A, or standing up regulatory response teams, our Antipyretic & Analgesic market study translates macro growth (historical and forecast), regulatory inflection points, and competitive posture into executable choices. The market’s steady expansion—against a backdrop of episodic regulatory and quality shocks—creates high value for disciplined, forward‑looking decisions. Our full report provides the granular tables, country and channel splits, company market shares, and downloadable modeling tools you need to operationalize strategy.
To access the complete market tables, per‑company market share assignments, and the interactive financial model that underpins the scenarios summarized above, please consult the PW Consulting report package. The full dataset is the difference between a plausible plan and a winning one in 2026.
For detailed analysis of this topic, please visit the official page: Antipyretic and Analgesic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com