

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Denatonium Benzoate Anhydrous Market to Reach USD 276.07M by 2032 at 5.8% CAGR

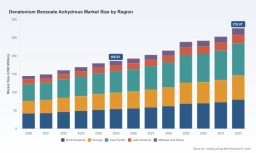
Denatonium Benzoate Anhydrous Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a concise yet high-fidelity preview of our latest Denatonium Benzoate Anhydrous market study. This briefing is tailored to corporate leaders, strategy teams, and investment committees preparing decisions in 2026. It demonstrates the analytical depth and operational utility of the full report while preserving the premium, segment-level intelligence that drives competitive positioning—intentionally withheld here to direct stakeholders to the full publication for transaction-grade detail.
Denatonium Benzoate Anhydrous Market
Why this market matters for 2026
- Denatonium benzoate remains the preeminent aversive agent and denaturant across a range of industrial, pharmaceutical, and consumer applications. Its unique functional role gives the product a defensive demand base even in cyclical downturns, while pockets of above-market growth arise from adjacent product innovations and regulatory shifts.
- From a macro perspective, the market demonstrates steady expansion: historical global revenues rose from USD 144.8 Million in 2020 to USD 186.61 Million in 2025. Our forecast conservatively projects continued growth across 2026–2032 at a compound annual growth rate (CAGR) of 5.8%, reaching USD 276.07 Million by 2032.
- For companies making 2026-era strategic choices—capacity expansion, vertical integration, product development, or M&A—these dynamics imply that timing, route-to-market, and product grade strategy will determine whether investments deliver premium returns or subscale exposure.
Market trajectory and the underlying drivers
The market’s historical performance (2020–2025) reflects a blend of stable base demand and selective upside from regulatory and product use-case shifts. Between 2025 and the early forecast years, the market is expected to pass the USD 190–200 Million inflection point and continue upward toward USD 276.07 Million by 2032 under baseline assumptions. Key drivers include:
Denatonium Benzoate Anhydrous Market
- Regulatory enforcement and safer‑use mandates that increase demand for aversive agents in household and industrial formulations.
- Product-grade diversification—different grades for pharmaceutical, cosmetic, and industrial applications—supporting premium pricing in specialty niches.
- Supply-side innovation, including biotechnological production routes, that can lower cost curves for select producers and enable margin expansion or aggressive pricing strategies.
- Consolidation trends among chemical suppliers, evidenced by the market’s moderate concentration metrics (CR3 ~35.4% and CR5 ~42.7%), which create opportunities for scale-driven differentiation but also preserve space for agile niche players.
What this means for 2026 corporate strategy
Decisions made in 2026 will be shaped by the market’s transition from recovery to structural growth. Executives should prioritize three pillars:
Denatonium Benzoate Anhydrous Market
- Portfolio granularity: Different end‑use grades and formats (powders, granules, specialty preparations) have materially different margin profiles and regulatory footprints. Strategic focus should be on aligning product‑grade mix to the company’s distribution strength and regulatory capabilities.
- Supply resilience: With limited global concentration at the top, buyers can pursue dual‑sourcing, backward integration, or strategic partnerships to secure continuity and negotiate more favorable cost terms as volumes grow.
- Regulatory and go‑to‑market agility: Regulatory shifts can rapidly change demand patterns. Firms that embed regulatory intelligence and rapid reformulation/customization into their launch processes will capture share from slower incumbents.
Report contents — practical tools included
The full PW Consulting report (base year 2025; historical coverage 2020–2025; forecast horizon 2026–2032) is engineered for operational decision-making. Highlights include:
- Top‑line and price forecasts (USD Million), including year-by-year market sizing and baseline/alternative scenarios calibrated to raw material, regulatory, and demand shocks.
- Demand drivers matrix linking end‑use markets to adoption levers and sensitivity analyses designed for scenario planning.
- Supply‑side model mapping global capacity, technology routes (including biotech manufacturing), lead times, and cost benchmarks to identify bottlenecks and margin pools.
- Commercial playbooks: go‑to‑market strategies for manufacturers, distributors, and private label players, with checklists for quality/grade certification, labeling, and regulatory dossiers.
- Valuation and transaction support: M&A screening rubric, target scorecards, and synergy templates for bolt‑on and platform deals.
- Supplier evaluation and a procurement negotiation toolkit—practical templates and KPIs to improve purchasing outcomes and secure supply resilience.
Note: this preview intentionally omits segment-level numerical splits (regional, application, and type percentages/values). Those granular tables and proprietary scorecards are proprietary to the full report and remain essential for executional decisions.
Competitive landscape — who matters and why
The competitive set is balanced between established global players and specialized regional manufacturers and distributors. The structure (CR3 ~35.4%, CR5 ~42.7%) suggests moderate concentration: market leadership exists but does not preclude competition from nimble or specialized entrants.
- Johnson Matthey (London, UK) — Operating under an internationally recognized brand, their Bitrex product is the reference standard for bitterness and denaturation. Their incumbent position is strengthened by brand recognition, integrated quality systems, and established distribution into regulated markets. Strategic implications: competitors must either differentiate on cost, specialty grades, or service to displace such incumbents in regulated accounts.
- Haihang Industry (Jinan, China) — A producer focused on CAS‑specified material for pharmaceutical and industrial applications. Their scale and local supply chain advantages make them a natural partner for price‑sensitive or volume buyers seeking reliability in Asian supply chains.
- Zhejiang Synose Tech (Jinhua, China) — Manufactures multiple pharmacopoeia‑grade variants for cosmetics and pharmaceuticals. Strength lies in regulatory compliance capabilities and diversified grade offerings, attractive to customers requiring certified materials.
- Zhengzhou Beth Food Additive (Zhengzhou, China) — Positions the product in food‑adjacent and additive markets, exploiting formulators who need food‑grade or food‑adjacent bittering agents.
- ECSA Chemicals (Lausanne, Switzerland) — A distributor specializing in bulk formats and logistics to European markets; valuable for manufacturers or buyers who lack direct importing footprints and need secure supply in premium markets.
- Shanxi Laike Bio‑Engineering (Shanxi, China) — Represents an alternative production route via biotech processes. If their commercially scalable processes reduce cost or environmental footprint, they could be a disruptive force in selected niches.
Collectively, these players illustrate the different competitive vectors: brand/quality leadership, low‑cost scale supply, regulatory compliance for sensitive end‑uses, distribution/logistics specialization, and process innovation. For decision-makers in 2026, the critical task is to map where your firm sits along these vectors and to choose a compensating strategy — e.g., premiumization, cost leadership, channel control, or technology differentiation.
Investment, M&A and partnership opportunities
Given the market’s steady CAGR of 5.8% and the forecast trajectory into 2032, the market is attractive for targeted investments rather than broad, undifferentiated plays. Practical opportunities include:
- Acquiring regional or specialty producers to secure grade diversity and shorten time‑to‑market for regulated customers.
- Partnering with biotech producers to pilot lower‑cost or greener production routes that can be scaled selectively for margin improvement.
- Investing in downstream formulation capabilities (e.g., premixed denaturants or custom blends) to capture higher value in customer supply chains.
Risks and regulatory considerations
While demand fundamentals are supportive, three risk vectors require active mitigation in 2026 planning:
- Regulatory shifts: Changes in denaturant approvals or labeling standards can rapidly re‑segment demand. Maintain a regulatory watchlist and contingency reformulation budget.
- Raw material volatility: Price shocks in feedstocks or energy can compress margins; long‑term contracts or hedging strategies should be evaluated.
- Quality and certification risk: For pharmaceutical and cosmetic customers, lapses in certification can result in lost contracts. Investment in quality systems is non‑optional for suppliers targeting premium channels.
How to use this preview and next steps
This brief demonstrates the strategic insights available in the full PW Consulting Denatonium Benzoate Anhydrous Market report, which provides the granular, transaction‑grade analysis required for 2026 decision-making: full regional and application-level forecasts, supplier scorecards, price modeling, and M&A screening templates. The full dataset enables precise scenario modeling (e.g., incremental capacity vs. demand sensitivity), which is essential for capital allocation and negotiation strategies.
For leadership teams preparing budgets, CAPEX proposals, or acquisition mandates in 2026, the two immediate actions we recommend are:
- Commission the full report to obtain the segment-level tables and supplier scorecards needed to run investment return simulations and procurement negotiations.
- Use the report’s supply model and commercial playbooks to stress‑test your current supplier base and identify immediate quick‑wins (dual sourcing, grade rationalization, or channel consolidation) that improve resilience and margins within 6–12 months.
Closing
Denatonium benzoate anhydrous sits at the intersection of regulatory necessity and niche performance chemistry. Our analysis shows a market that is predictable at the macro level but rich in micro opportunities and risks—exactly the environment where disciplined strategy, operational execution, and targeted investments create disproportionate value. To convert these insights into executable plans for 2026, PW Consulting’s full report and accompanying models are the necessary next step.
For detailed analysis of this topic, please visit the official page: Denatonium Benzoate Anhydrous Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com