

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Air Deodorizer & Sterilizer Market to reach USD 13.42B by 2032 at 8.1% CAGR

Air Deodorizer and Sterilizer Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a focused strategic preview of our comprehensive Air Deodorizer and Sterilizer Market study (base year 2025). This briefing synthesizes the macro trajectory, competitive dynamics, regulatory inflection points, and the high‑impact levers that corporate leaders must prioritize in 2026. Consider this a strategic trailer: it demonstrates the analytical depth that underpins our full study while intentionally withholding granular segment tables to prompt direct engagement with the source report for transaction‑grade data.
Air Deodorizer And Sterilizer Market
Macro Trajectory: Market Momentum and What It Means
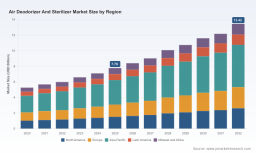
The global market for air deodorization and sterilization has moved from niche adoption to mainstream capital planning over the past half‑decade. Measured in USD (Billion), the market expanded from approximately 5.27 in 2020 to around 7.78 in 2025 and is projected to reach roughly 13.42 by 2032. This trajectory represents a compound annual growth rate (CAGR) of 8.1% over the forecast window, reflecting persistent demand driven by healthcare requirements, workplace health priorities, hospitality recovery, and heightened consumer awareness of indoor air quality (IAQ).
Air Deodorizer And Sterilizer Market
For corporate decision‑makers, that growth profile is more than a headline. It defines the envelope within which product roadmaps, manufacturing investments, channel strategies, and M&A activity must be calibrated. A sustained ~8% CAGR supports multi‑year investments in next‑generation sterilization technologies (UVC LED, plasma, advanced filtration), but it also requires discipline: not every product variant or regional push will scale proportionately. The full report contains deterministic forecasts, scenario variants, and sensitivity analyses that translate this headline CAGR into actionable revenue curves and break‑even horizons for specific product archetypes.
Air Deodorizer And Sterilizer Market
Why 2026 Is a Strategic Inflection Point
- Capital allocation windows are opening: With 2026 marking the transition from recovery to sustained growth for several end markets, firms face decisions about ramping production lines, dedicating R&D budgets to sterilization vs. deodorization features, and prioritizing certification pathways for medical use.
- Regulatory and certification gates matter: Medical‑grade clearances and food‑safety certifications materially expand addressable markets but also extend time‑to‑market and capex requirements.
- Channel economics are shifting: The interplay between direct healthcare procurement, commercial HVAC integration, and consumer retail is reshaping pricing power and margins.
In practical terms: 2026 is the year to decide whether to scale, partner, or exit specific subsegments. Our report equips executives with the scenario planning and economic models required to take those decisions with confidence.
Report Coverage: Operational Intelligence You Can Use
PW Consulting’s full study contains the following practitioner‑oriented deliverables (high level):
- Comprehensive market sizing and forecasts (2020–2032) with baseline and stress scenarios, including forward curves by product archetype and adoption phase.
- Granular segmentation (by region, by device type, by end application) with growth velocity matrices—note: this preview deliberately omits those tables to preserve the value of the full dataset.
- Technology landscape map: evaluation of UVC (including UVC LED), plasma, HEPA/filtration hybrids, photocatalytic oxidation and emerging innovations—each assessed for efficacy, cost, certification burden and deployment use cases.
- Regulatory and compliance playbook tailored to medical, commercial and food‑service channels (including certification timelines, lab protocols and procurement requirements).
- Competitive benchmarking: validated vendor scorecards, capability matrices, go‑to‑market archetypes, and prioritized partnership targets.
- Go‑to‑market templates for OEMs, integrators and channel partners: pricing models, pilot frameworks, procurement tender language and KPI dashboards for post‑deployment validation.
- M&A and partnership heatmap: valuation multiples, strategic rationale for bolt‑on acquisitions, and checkpoints for rapid integration.
- Supply‑chain stress tests and component roadmap: critical inputs, lead‑time exposures, and recommended dual‑source strategies for high‑risk parts.
These deliverables are designed to convert market projections into executable plans: where to deploy capital, which certifications to prioritize, how to price for hospital tenders versus commercial HVAC channels, and how to structure distribution partnerships for rapid scale.
Competitive Landscape: Strategic Implications of Core Players
The competitive structure is characterized by a mix of specialized technology providers and large diversified industrial OEMs. The market concentration metrics indicate meaningful leader presence—our analysis shows that the top three firms hold a significant share of the market, while the top five consolidate a further portion of industry revenue—highlighting an environment where scale and certification credentials create durable advantages.
- Sanuvox Technologies (Montreal, Canada): A specialist in UV air purification and surface disinfection with solutions positioned for institutional healthcare. Sanuvox’s patented UV architectures and hospital deployments make it a first mover for clients prioritizing validated pathogen inactivation.
- Camfil (Stockholm, Sweden): Renowned for advanced filtration and high‑containment production capacity, Camfil is strategically placed to serve hospital, lab and controlled environment projects where filtration performance and supply reassurance matter.
- Novaerus / WellAir (Charlotte, NC): A leader in portable plasma air disinfection with FDA 510(k) clearances for certain product lines, enabling direct access to healthcare procurement channels that require medical device classification.
- Trion (Peachtree City, GA): Focused on commercial IAQ solutions and attractive to integrators who value modular systems for large facilities.
- Panasonic and Daikin (Osaka, Japan): Large OEMs with R&D scale and broad distribution; their investments in proprietary deodorization (nanoe™, Streamer) and plug‑and‑play sterilization products position them to capture both consumer and commercial segments rapidly.
- IQAir and Blueair (Switzerland/Stockholm): Brands that emphasize HEPA performance and consumer/medical certifications, respectively—important for customers prioritizing particle removal and validated filtration efficacy.
Recent corporate actions further crystallize market direction: strategic distribution partnerships, product launches featuring real‑time IAQ sensing and UVC LED sterilization, and industry recognition that reinforces brand trust. Each of these moves alters channel dynamics and shortens the path to market for differentiated products.
Regulatory, Certification and Supply Considerations
Regulation and certification materially affect access to high‑value segments. Notable compliance and certification dynamics to factor into 2026 plans include the following:
- Food safety and antibacterial deodorization certifications can unlock hospitality and food‑service procurement pipelines.
- Medical device clearances create exclusive procurement corridors in hospitals but require sustained clinical validation and regulatory engineering investment.
- Zero‑ozone and regional air quality compliance regimes impose design constraints and influence component selection and manufacturing locations.
- Manufacturing scale, exemplified by advanced filtration production lines, is a competitive moat—firms that secure capacity early can protect margins when demand surges.
Our full report includes a decision matrix mapping certification choices to forecasted incremental addressable revenue and payback periods—an indispensable tool when deciding whether to fast‑track clinical trials or prioritize retail rollouts.
Actionable Strategic Recommendations for 2026
- Prioritize certification pathways by segment economics: For companies targeting healthcare, invest in medical‑grade clearance early. For hospitality and consumer markets, HACCP and food‑safety recognitions may deliver faster commercial adoption with lower regulatory cost.
- Match technology to channel economics: UVC LED and plasma offer faster differentiation but can carry higher upfront R&D and component scarcity risks; HEPA and filtration hybrids scale more predictably through existing HVAC channels.
- Lock capacity and diversify suppliers: Secure production capacity for critical filters and optics; mitigate lead times through dual sourcing and nearshoring where appropriate.
- Design channel‑specific value propositions: Build discrete sales plays for hospital procurement, wholesale HVAC integrators, and consumer retail—with tailored pricing, warranty, and service models for each.
- Pursue targeted partnerships and bolt‑on M&A: Use partnership frameworks to accelerate distribution, and consider small acquisitions to acquire certifications, distribution access or specialized IP.
Each recommendation is supported by quantified ROI scenarios in the full study—models that show how incremental investments in certification, production capacity or channel development translate into NPV under different adoption curves.
Risk Radar and Contingency Planning
Key risks to monitor include component supply disruption, changes in regional regulatory standards, and the emergence of alternative disinfection modalities that shift adoption curves. The report contains stress test outputs that quantify revenue and margin impacts under late‑cycle component shortages and accelerated regulatory change—allowing leaders to create contingency budgets and flexible supply contracts.
Next Steps
This preview outlines the strategic terrain for the Air Deodorizer and Sterilizer market as companies prepare to act in 2026. For procurement teams, R&D leaders and corporate strategists, the full PW Consulting report provides the granular tables, vendor share data, and executable playbooks necessary to move from insight to action. Our dataset includes the full segmentation by region, type and application, plus vendor scorecards, pricing curves and scenario models that are intentionally withheld from this preview.
To access the complete intelligence suite—including deterministic revenue tables, segmental growth drivers, and step‑by‑step implementation templates—please refer to the detailed report page. PW Consulting stands ready to support bespoke advisory and implementation workstreams that translate these findings into measurable outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Air Deodorizer And Sterilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com