

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Packaging Market Outlook 2026-2032 — 4.5% CAGR, Asia-Pacific Dominates

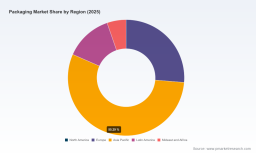
Packaging Market 2026: Strategic Preview for Executive Decision-Making
As global supply chains realign and sustainability regulations accelerate, 2026 will be a pivotal year for packaging executives shaping product portfolios, sourcing strategies, and M&A pipelines. PW Consulting’s latest Packaging Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro trajectories, regulatory inflection points, raw material dynamics, and competitive intent into an operationally oriented intelligence pack designed to inform board-level decisions and 12–36 month implementation plans.
Packaging Market
Market at a Glance — Direction, Scale, and Momentum
- Market scale and trajectory: The global packaging market, measured at the report’s base year (2025), sits at approximately USD 2.15 trillion (reporting in USD, revenue unit: Million). Our forecast path projects the market to expand at a compound annual growth rate (CAGR) of roughly 4.5% through 2032, reaching the low‑to‑mid USD 3.4 trillion range by the end of the forecast horizon.
- Recent volatility and recovery: Historical dynamics (2020–2025) show episodic contraction and rebound tied to raw material price swings and pandemic-related demand shifts. The forecast period assumes normalization of demand patterns, continued premiumization in certain end‑use categories, and a progressive shift toward higher-value (and higher-margin) sustainable solutions.
- Market structure: Concentration remains relatively low: the top three firms account for under one quarter of the market and the top five for roughly one quarter (CR3 ≈ 24.6%; CR5 ≈ 26.2%). This structural profile favors continued competitive intensity, niche specialization, and frequent cross-border M&A.
Why This Study Matters for 2026 Corporate Strategy
Executives entering 2026 face simultaneous pressures: tighter recycled-content rules, state and regional EPR (extended producer responsibility) rollouts, and raw material cost pass‑throughs. This study translates those pressures into decision-grade insights across four corporate imperatives:
Packaging Market
- Regulatory readiness: The report quantifies the compliance exposure of typical product portfolios under emerging frameworks (e.g., EU PPWR implementation timelines and US state-level EPR advances), and models cost-to-comply across alternative packaging architectures.
- Supply‑chain resilience: We map input-price sensitivity (pulp, containerboard, polymers, metals) to supplier concentration, inventory policies, and logistics bottlenecks, creating hedging playbooks that are actionable in procurement and treasury.
- Portfolio optimization: Using scenario-based profitability overlays, the study ranks packaging formats and technologies by risk-adjusted margin contribution across five strategic scenarios — useful for SKU rationalization and capex prioritization.
- M&A and partnership targeting: Given the dispersed market and steady mid-single-digit growth, inorganic growth remains a primary lever. Our screening identifies target archetypes and integration playbooks for both bolt-on and transformational transactions.
What’s Inside the Report — Practical, Executable Content
The study is deliberately tactical. Beyond headline market sizing, it contains:
Packaging Market
- Methodology appendix explaining base-year normalization (2025) and forecast assumptions for 2026–2032, including sensitivity tests tied to raw material price shocks and regulatory adoption timing.
- Segment-level scenario matrices (accessible in full report) that translate demand shifts into margin and cash‑flow implications without leaking competitive subsegment shares in this preview.
- Regulatory impact modeling: cost-to-comply calculators and a compliance roadmap for EU PPWR and major US state EPR laws, with timelines and enforcement risk assessments tailored to brand owners and CPG manufacturers.
- Procurement playbook: indexed supplier scorecards, contract clauses to manage pass-throughs, and a short-list of alternative feedstocks and material substitutions evaluated for technical and sustainability viability.
- Technology and automation ROI templates for packaging lines, including break‑even analyses for retrofit vs. greenfield automation investments.
- Commercial go-to-market guides: channel strategies for converting sustainability claims into price realization, retailer negotiation levers, and pilot frameworks for packaging-as-a-service pilots.
- Detailed competitor profiles and deal‑tracker (high‑level) for the largest technology and material suppliers, with strategic implications for partnerships and co‑innovation.
Competitive Landscape — Who’s Shaping 2026?
The market’s low concentration feeds vigorous strategic maneuvering. The report provides qualitative and actionable analysis of leading players and their likely plays in 2026:
- Amcor plc (HQ: Switzerland) — Amcor’s expanded portfolio (post-merger integrations and product innovation) positions it as a scale player in flexible and rigid formats. Strategic emphasis: modular closures and cost-performance closures designed to lower total system cost for large CPG customers. Watch for continued integration of acquired assets and program-level contracts that lock in multi-year volumes.
- Sealed Air Corporation (HQ: United States) — Focused on protective and food-safety packaging, Sealed Air is doubling down on automation and recycle-ready formats. Recent trade-show presence and product introductions signal a two‑track play: premium protective solutions for ecommerce and compliance-driven food packaging lines aimed at circularity targets.
- Smurfit Westrock (HQ: Ireland) — A leader in paper-based and corrugated solutions, Smurfit Westrock is leveraging recycled fiber and circular-economy narratives to win retailer shelf space. Their trade-show activity underscores investments in productivity and sustainable substrates that reduce scope‑3 exposure for customers.
- Sonoco Products Company (HQ: United States) — Sonoco’s breadth across paper, metal, and plastic gives it flexibility to hybridize solutions for customers seeking transitional pathways away from fossil-based plastics. Expect continued expansion in metal packaging and integrated end‑to‑end supply offerings.
- Huhtamaki Oyj (HQ: Finland) — A specialist in food‑on‑the‑go and mono-material solutions, Huhtamaki is positioned to capture convenience-led demand while meeting stricter recyclability criteria. Their investments in mono-material technologies make them a likely partner for fast-moving foodservice brands facing EPR obligations.
Recent market activity underscores these strategic directions: trade-show launches, product rollouts focused on recyclability and cost efficiency, and public-facing sustainability commitments. The EU PPWR and accelerating US EPR laws are not theoretical risks — they are shaping product roadmaps and go‑to‑market timing in real time.
Regulatory and Raw Material Dynamics — The Twin Speed Factors
Two sets of external variables will disproportionately influence 2026 outcomes:
- Regulations shaping demand and cost: The EU Packaging and Packaging Waste Regulation (PPWR) moved into force in early 2025 and becomes generally applicable in mid‑2026, introducing recycled-content targets and restrictions on certain formats. Meanwhile, US states (including California) are tightening reporting and EPR obligations with 2026 compliance milestones. These measures create asymmetric cost exposure across formats and geographies and will accelerate substitution where viable alternatives exist.
- Raw-material price pressure: Paper and containerboard prices resumed an upward trajectory in 2025, and producer-price indices for pulp and allied products remain volatile. These trends magnify the importance of procurement agility: near-term margin recovery hinges on contract design, captive recycling programs, and selective pass-through mechanisms with brand customers.
Strategic Playbook — Practical Moves for 2026
Based on the synthesis of macro trends, regulatory calendars, and competitor moves, PW Consulting recommends a prioritized, time‑bound playbook for 2026:
- Immediate (0–6 months): Conduct a regulatory exposure audit by SKU and jurisdiction; implement minimum viable compliance packaging changes for SKUs with the highest near‑term enforcement risk.
- Short term (6–18 months): Execute procurement hedges with indexed contracts and strategic peering with fiber and plastics recyclers; pursue pilot mono‑material conversions on high-velocity SKUs to reduce complexity and prepare for recyclability mandates.
- Medium term (18–36 months): Accelerate automation retrofits tied to labor and OEE gains; pursue bolt-on acquisitions that fill capability gaps in sustainable substrates or automated secondary packaging; commit to measurable scope‑3 reductions with validated third‑party metrics to secure retailer and investor trust.
- Commercial: Rework commercial agreements to enable sustainability investments (e.g., shared-cost CAPEX models) and enable premium capture for demonstrably lower lifecycle-impact packaging.
What This Preview Withholds — And Where to Find It
Consistent with our “trailer” approach, this article surfaces directionally the macro market sizing, growth trajectory, concentration metrics, competitive posture, and regulatory context that will drive boardroom decisions in 2026. To preserve the strategic value of the complete intelligence set — including granular segment economics, region-by-region demand curves, SKU-level margin simulations, and proprietary target lists — PW Consulting directs executives to the full report and accompanying datasets, which provide the numerical and model detail required for transaction diligence and operational planning.
Conclusion — Positioning for a Compliance‑and‑Innovation Economy
2026 is shaping up to be a year of consequential choices for packaging leaders: retrofit or replace, buy or build, standardize or customize. The market’s steady mid-single-digit growth masks substantial redistribution of value toward companies that can de‑risk supply chains, deliver verified circular solutions, and monetize sustainability through differentiated service models. PW Consulting’s Packaging Market 2026–2032 study is designed to translate those shifts into executable plans — from procurement and product development to M&A and commercial negotiation — so that executives can move rapidly from regulatory reaction to strategic advantage.
For the full data tables, scenario models, and company playbooks referenced here, access the complete report on the PW Consulting website — it contains the operative granularity required to convert insight into impact.
For detailed analysis of this topic, please visit the official page: Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com