

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Motor Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Motor Market 2026: Strategic Outlook and Action Playbook
Executive summary
As global electrification and automation accelerate, the motor market sits at an inflection point that will define industrial competitiveness and mobility strategies for the rest of the decade. Our Motor Market study, with base year 2025 and a historical window covering 2020–2025, projects the market to expand from an estimated USD 215.0 Million in 2025 to approximately USD 344.8 Million by 2032. This trajectory implies a compound annual growth rate (CAGR) of 6.98% across the forecast period (2026–2032). For corporate leaders making 2026 investment and portfolio choices, this study translates those headline numbers into measurable strategic options — but in this introduction we intentionally surface strategic insights while withholding the granular segment tables to encourage direct engagement with the full report.
Motor Market
Why the 2026 decision window matters
2026 is not merely another year on the growth curve. It is the first year of the forecast period and a practical decision point for capital allocation, supply-chain reorientation, and R&D prioritization. Between 2020 and 2025 the market expanded materially — our baseline grew from roughly USD 163.15 Million in 2020 to USD 215.0 Million in 2025 — demonstrating both resilience and structural momentum. The step-change projected for 2026 (to about USD 231.54 Million) signals that investments initiated in 2026 will capture the earliest portion of compounding returns that drive value through 2032.
Motor Market
Key macro implications for strategy
-
Growth with concentration: Despite healthy market growth, the competitive landscape remains fragmented. The top-three and top-five firms together account for approximately mid‑20 percent market shares (CR3 ≈ 24.6%, CR5 ≈ 26.2%). That fragmentation means scale matters but so does agility — there is room both for large incumbents to consolidate value and for focused challengers to win via niche specialization.
Motor Market -
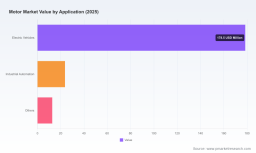
Demand mix is shifting: Electrification of mobility and rising automation in manufacturing are dominant demand drivers. While we will not disclose the full split here, electric vehicles are the single largest end-market in the base-year construct; industrial automation and other sectors represent material, differentiated growth pockets. That split should influence product roadmaps and go-to-market models.
-
Materials and policy risk are now a strategic headwind: Rare earths, copper, aluminium and other critical inputs are central to product cost, technology choice and supply security. Recent regulatory moves — notably the EU Critical Raw Materials Act and escalated export-controls on rare earths — change how companies must model sourcing and localization risk.
Market dynamics that will shape winners and losers
Understanding the interplay of raw materials, technology cycles and policy is the axis on which near-term choices will compound into long-term advantage.
-
Raw material supply geometry: Demand for rare earth elements is set to surge in Europe and globally as permanent-magnet motor content rises with electrification. Policymakers in Europe are pursuing diversification and local aggregation of critical materials, while other jurisdictions have tightened export controls — a dynamic that can inflate procurement costs, delay product launches or force redesigns.
-
Regulatory architecture: The EU requirement to limit single-country dependency and the launch of centralized material-data infrastructures (e.g., the EU Critical Raw Materials Centre scheduled for launch in 2026) create both compliance obligations and opportunities to secure preferential project pipelines for firms that can demonstrate resilient sourcing.
-
Technology substitution and product mix: Innovations in motor topologies (e.g., synchronous reluctance, hairpin and S-winding technologies, magnetless designs) change the value equation between performance and material dependency. Companies that map expected material constraints into alternate architectures will preserve margins while meeting customer performance thresholds.
-
Price and efficiency sensitivity: A 10MW synchronous motor illustrates the scale of raw-material exposure (tons of copper, hundreds of kilograms of aluminium), underscoring why procurement strategies and engineering choices must be integrated. Small percentage gains in efficiency or reductions in rare-earth intensity can produce outsized commercial returns at scale.
Competitive landscape — what the leading players are doing
The market is being actively contested along three vectors: technology leadership (motor topology and manufacturing), program wins with OEMs (especially in EV platforms), and localized production footprints. Highlights from leading companies and recent developments illuminate tactical moves to watch in 2026:
-
ABB Ltd (Zurich) — continues to place bets on high-efficiency AC and synchronous reluctance motors, amplifying capabilities through demonstration facilities (for example, a new Berlin center opened in late 2025). Their strategy emphasizes combined efficiency and sustainability narratives for industrial automation and mobility customers.
-
Siemens AG (Munich) — retains emphasis on premium AC and DC motors for industrial drives and renewable-generation applications. Expect Siemens to press into integrated drive systems and services, targeting higher gross margins per installed base.
-
Nidec (Kyoto) — focuses on precision DC, e-axles and servo solutions for automotive and robotics; they remain an innovation nucleus for compact, high-density motor designs aligned with EV architectures.
-
WEG S.A. (Brazil) — leverages robust 3-phase AC platforms for heavy industries and energy markets, where durability and low total cost of ownership are competitive differentiators.
-
Regal Rexnord and Bosch Rexroth — pursue breadth in AC/DC and motion-control suites, respectively, prioritizing integrated solutions for HVAC, industrial automation and factory modernization.
-
BorgWarner — has accelerated its automotive focus through recent product awards and program wins across Asia and Korea, including hairpin and S-winding technologies for hybrid and high-voltage EV platforms; these contracts and rolling production phases (through 2027) are exemplar of program-driven scaling strategies in the e-mobility segment.
-
Toshiba and Hyundai Electric — continue to hold positions in large industrial and medium/high-voltage motor markets where utility and heavy-industry specifications dominate procurement decisions.
What the full report delivers (practical, transaction-ready content)
Our Motor Market study is designed for executive teams, corporate development groups, and product leaders who need actionable outputs for 2026 strategy cycles. Deliverables include:
- Transparent market-sizing and growth scenarios with sensitivity testing against commodity price and policy shocks;
- Supply-chain maps and tiered supplier scorecards that quantify single-source exposure and re-shoring opportunity;
- Technology roadmaps comparing magnet-intensive vs. magnet-lean architectures, with R&D timelines and cost-per-performance curves;
- Commercial playbooks: partner archetypes, OEM engagement templates, and service-led monetization models;
- M&A and JV scouting lists with fit/gap diagnostics and prioritized integration checklists;
- Regulatory impact models tailored to regional policy regimes and export-control scenarios;
- Customizable dashboards for scenario-driven capital allocation and product launch sequencing.
Recommended 2026 actions — a concise playbook
For leadership teams preparing 2026 budgets and roadmaps, we advise a balanced set of moves that protect margins, accelerate time-to-market, and hedge material risk:
-
Prioritize program-backed product investments: Allocate incremental capex to programs with signed OEM commitments or high-probability commercial pipelines to shorten payback cycles.
-
Localize critical inputs selectively: Use a risk-weighted framework to decide where to localize rare-earth processing or copper-intensive sub-assembly, focusing on regions with favorable regulatory incentives or customer proximity.
-
Adopt flexible engineering platforms: Invest in motor architectures that allow magnet substitution or different winding technologies without full redesigns, thereby protecting product roadmaps from material supply shocks.
-
Lock strategic partnerships: Pursue joint-ventures with material refiners, coil and stator assemblers, or software integrators to capture margin and secure supply continuity.
-
Instrument scenario planning: Use Monte Carlo–style modelling for commodity and regulatory shocks to set trigger points for hedging, capex deferments or accelerated rollouts.
-
Scan for opportunistic consolidation: Given the fragmented nature of the market, target tuck‑ins that add proprietary technologies, fill geographic gaps, or accelerate time to major OEM programs.
Conclusion and next step
The market's growth trajectory through 2032 is clear and strategically meaningful: structural demand from electrification and automation, combined with material and policy pressures, creates a landscape of both risk and disproportionate opportunity. The CR3 and CR5 figures illustrate a fragmented competitive terrain where disciplined scale and focused differentiation both pay. Our full Motor Market report converts the headline growth (CAGR 6.98% for 2026–2032) into executable recommendations, prioritized deal lists, and quantified risk mitigations — including the segment-level data, regional playbooks and sensitivity matrices that we have intentionally withheld here to maintain this piece as a strategic prelude.
To access the complete dataset, granular segment breakdowns, customizable dashboards and the full set of playbooks for 2026 execution, please refer to the Motor Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com