

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Banknote-Printing Machine Market to reach USD 333.3 Million by 2032 at 10.4% CAGR
By pmarketresearch, 2026-07-13
Banknote-Printing Machine Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused introduction to our latest Banknote-Printing Machine Market study. This briefing synthesizes the structural trajectory, competitive dynamics, and tactical implications that should inform procurement, capital planning, and partnership strategies in 2026. It intentionally showcases the analytical depth and decision-grade frameworks contained in the full report while withholding detailed sub-segment tables and proprietary breakouts—designed to invite direct engagement with the full study for operational execution.
Banknote-Printing Machine Market
Why this market matters in 2026
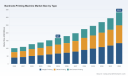
The banknote-printing machine market has moved from a niche, capacity-focused sector into a strategic industrial sub-market at the intersection of sovereign finance, security technology, and advanced manufacturing. On the macro scale, the market expanded from roughly USD 101.8 Million in 2020 to about USD 167.0 Million in our base year (2025), and our projections indicate continued momentum through the forecast window (2026–2032), culminating near USD 333.3 Million by 2032 at a compound annual growth rate of 10.4%. That rate embeds both recurring replacement cycles for central banks and accelerations tied to technology refresh, polymer adoption, and higher-security feature demand.
Banknote-Printing Machine Market
Core demand drivers and structural dynamics
- Sovereign lifecycle and capacity planning: Central banks and large security printers operate on long lead times and multi-year modernization plans. Public modernization programs and multi-year print orders materially shape near-term OEM order books and service revenues.
- Security innovation vs. cost pressure: The paradox of this market is that rising security requirements (new features, hybrid substrates, enhanced inspection systems) increase per-unit complexity and cost, yet budget pressures on currency issuers push for more efficient lines and lower total cost of ownership.
- Technology convergence: Integrations across intaglio, offset, screen, and web-fed hybrid lines—combined with inline inspection, digital controls, and automated convertors—are shifting value from single-process machines to platform-based production lines that support shorter changeover times and higher uptime.
- Regulatory and strategic tailwinds: Recent procurement decisions and strategic modernization initiatives by major sovereign printers have created a pull for new equipment and aftermarket services. Industry conferences and awards continue to codify innovations that accelerate adoption, while procurement cycles at major issuers create discrete opportunities for suppliers.
- Concentration and supplier economics: The market exhibits meaningful concentration—our study measures a top-three concentration near the mid-50 percent range and a top-five near the low-70 percent range—implying an oligopolistic supplier structure with differentiated scale and aftermarket advantages.
Technology and product evolution
From equipment design to plant engineering and inline quality assurance, the evolution in this sector is practical rather than speculative: tighter tolerances, enhanced process automation, and modular architectures that let operators combine security printing processes in flexible lines. These shifts favor manufacturers that can offer integrated solutions—machines plus plant-level engineering and digital services—over isolated press sellers. Expect procurement criteria to increasingly reward lifecycle services (predictive maintenance, retrofitability, spare-part pools) as well as cybersecurity and compliance features embedded in control systems.
Banknote-Printing Machine Market
Competitive landscape: players to watch
The competitive map is shaped by a handful of legacy players and specialized OEMs that combine press engineering with high-security expertise. Our full report contains comparative vendor scorecards; below is a synthesized qualitative view of principal competitors and recent market signals that are critical for 2026 planning.
- Koenig & Bauer Banknote Solutions (Lausanne, Switzerland)
Koenig & Bauer is positioned as a high-security specialist, offering integrated screen and offset systems and end-to-end production lines. Its strengths are engineering depth for banknote-specific requirements and a track record of trade-fair innovation signaling. For buyers, Koenig & Bauer is often a go-to when complete line integration and legacy compatibility matter. - Komori Corporation (Tokyo, Japan)
Komori’s CURRENCY Series and combination multiprocess machines have global reach and an installed base across many markets. Komori’s credentials include supplying mission-critical systems for national currency projects and recent high-profile orders for major sovereign printers. Its scale and technology leadership make it a preferred partner where long-term support and large-system delivery reliability are prioritized. - Giesecke+Devrient (Munich, Germany)
G+D combines machine supply with high-tech plant engineering and consulting services, which is valuable where process design and quality inspection are decisive. G+D’s offerings lean into end-to-end delivery—equipment, software, and operational know-how—making it adept at complex modernization projects. - De La Rue (Basingstoke, United Kingdom)
De La Rue, with its long-established security-printing capabilities and equipment lineage, remains a full-solution provider including substrate expertise. Their capabilities are often tapped where integrated supply—from design to execution—is required, including polymer transitions and production technique dissemination in regional markets. - Goebel Capital GmbH, SPS TechnoScreen, Pasaban
These specialized OEMs (hybrid web-fed systems, cylinder screen presses, paper converting and sheeting equipment) play crucial roles in niche elements of the production chain. Their value is in modularity, specialized process performance, and the ability to supply retrofits and ancillary plant equipment that increase line throughput or support substrate transitions.
Recent market signals — reading the tea leaves
- Mid-2020s procurement and modernization plans among major sovereign printers have continued to drive equipment demand and aftermarket services. Prime examples include large-system orders awarded in 2025 and strategic equipment roadmaps published by national printers that prioritize efficiency improvements.
- Trade shows and industry awards during 2025–2026 have highlighted both incremental and step-change innovations in substrates, security features, and production ergonomics—indicating that buyers are actively benchmarking new technologies.
- Plant-level modernization programs emphasize that opportunity lies as much in engineering services, retrofit capability, and quality inspection systems as in the sale of new presses. This widens the addressable services market for suppliers with systems-integration capabilities.
Implications for 2026 corporate decisions
For corporate leaders—OEMs, security printers, central banks, and investors—the next 12–18 months are pivotal. Below are high-level strategic takeaways to guide 2026 decisions; the full report converts each into actionable roadmaps and templates.
- Procurement strategy must be lifecycle-aware: Evaluate suppliers on total cost of ownership, retrofitability, and aftermarket coverage, not only on capex price. Insist on demonstrable field data for uptime, mean time to repair, and spare-part logistics.
- Partnerships trump point-solutions: Seek vendors capable of delivering combined equipment-and-engineering solutions. Where capacity constraints or specialized substrates are in play, a converged supplier can reduce project risk and shorten time-to-production.
- Mitigate concentration risk: The market’s top-firm concentration creates supplier dependency risks. Structuring procurement to include second-source options, licensable technology, or performance-based contracts can lower supply-chain vulnerability.
- Capitalize on retrofit and services growth: For OEMs and service providers, investing in predictive maintenance, digital spare-part catalogs, and modular retrofit kits is the most direct path to recurring, higher-margin revenue.
- Policy and program timing matters: Align sales and investment pipelines with sovereign procurement cycles and modernization programs—these create discrete peaks in demand and influence capacity planning.
What our report delivers (practical content)
The full PW Consulting study is highly operational and built for decision-making. Key deliverables include:
- Market sizing and 2026–2032 forecast models with scenario sensitivity and unit economics calibrated to different modernization pathways;
- Vendor due-diligence templates and comparative scorecards covering technology, service footprint, financial strength, and incumbent risk;
- CapEx budgeting tools and procurement negotiation playbooks, including RFP checklists and contractual clauses to safeguard uptime and IP;
- M&A and partnership blueprints—target screen criteria, valuation levers for bolt-on services, and integration planning checklists;
- Operational readiness matrices for central banks and large printers—plant-engineering best practices, retrofit sequencing, and quality-inspection baseline expectations;
- Risk registers for supply-chain, regulatory, and cybersecurity exposures with mitigations and contingency cost models.
Closing: how to use this briefing in 2026
Use this briefing to orient your 2026 strategic priorities: align procurement calendars to sovereign modernization timelines, re-weight supplier assessments toward lifecycle services, and prepare for selective investments in retrofit and digital service capabilities. The landscape favors integrated suppliers and service-led business models, yet concentration in supplier share creates both opportunity and risk for buyers and investors.
PW Consulting’s full Banknote-Printing Machine Market report converts these insights into the analytic assets decision-makers need—forecast models, vendor scorecards, procurement playbooks, and executable roadmaps. For teams preparing CapEx proposals, vendor negotiations, or M&A screens in 2026, the study is structured as an operational toolkit rather than a purely descriptive market review.
To access the complete analysis, detailed supplier benchmarking, and the ready-to-use templates that underpin these recommendations, visit the PW Consulting research portal and request the Banknote-Printing Machine Market report package.
For detailed analysis of this topic, please visit the official page: Banknote-Printing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Image Capture Cards Market to hit USD 3,160M by 2032 — 9.8% CAGR
By pmarketresearch, 2026-07-13
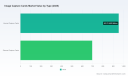
Image Capture Cards Market — 2026 Strategic Brief (PW Consulting)
As enterprises plan capital allocation, product roadmaps, and go-to-market moves for 2026, the Image Capture Cards market presents a compelling mix of sustained growth, concentrated incumbent power, and material operational risk. Our latest study — grounded in a 2020–2025 historical backbone and a 2026–2032 forecast horizon — documents a robust structural expansion driven by multimedia proliferation across gaming, streaming, professional AV, medical imaging, conferencing and security workflows. The market has progressed from under a billion USD in 2020 to roughly USD 1.65 billion in our 2025 base year and is projected to continue growing at a near-double-digit compound annual growth rate (~9.8%) through the forecast window, reaching multibillion-dollar scale by 2032. This brief explains why that trajectory matters for strategic choices in 2026 and which levers senior executives should prioritize.
Image Capture Cards Market
Why this report is a must-read for 2026 decision makers
-
Actionable signal in a noisy market: We translate macro growth into decision-ready implications for R&D prioritization, channel strategy, and pricing models, without overreliance on vendor anecdotes.
Image Capture Cards Market -
Risk-to-reward mapping: The study overlays demand growth with supply fragility — enabling procurement and product leaders to align inventory, qualify alternate suppliers, and quantify retention cost for premium positioning.
Image Capture Cards Market -
Competitive posture diagnostics: You’ll get a pragmatic read on where to defend, where to attack, and where consolidation is likely to accelerate — key for M&A and strategic partnerships in 2026.
-
Compliance and architecture playbook: For enterprises deploying capture technology into regulated environments, the report gives a design checklist for data localization and privacy-safe ingestion pipelines.
Report contents — practical elements (teaser)
-
Market sizing and trajectory: Clear historical base (2020–2025) and scenario-modeled forecasts for 2026–2032 that quantify upside/downside under alternative adoption and supply assumptions.
-
Demand-side use-case deep dives: Comparative economics and integration complexity across primary end markets to help prioritize product features and certification efforts.
-
Technology and product taxonomy: Objective breakdown of form factors (PCIe, USB, M.2), I/O standards (SDI/HDMI/12G, frame-rate and color-depth trade-offs), and emerging architectures (FPGA, ASIC, SoC-based capture acceleration).
-
Supplier risk matrix: Lead-time sensitivity, concentration of advanced-foundry exposure, and component-level bottleneck scenarios with mitigations and contingency cost estimates.
-
Commercial playbooks: Recommended pricing frameworks, tiered warranty/service models, and channel incentive structures designed to defend premium ASPs while accommodating low-cost OEM pressure.
-
Competitive profiles and scenario-ready M&A watchlist: Strategic positioning, product roadmaps, and acquisition fit analyses for leading incumbents and high-potential challengers.
-
Decision-support assets: Excel-based TCO and ROI models, supplier selection scorecards, and a 12–36 month tactical rollout planner.
Key market dynamics shaping 2026 strategy
-
Structural demand growth vs. commoditization pressure — The market’s near-10% CAGR masks heterogenous unit- and value-growth dynamics. Higher-end professional capture solutions tied to broadcast, medical and pro AV remain a margin pool where innovation (e.g., multi-channel, low-latency 4K/8K capture) yields pricing power, while entry-level streaming/gaming capture is increasingly contested by low-cost OEMs. Strategic implication: protect premium tiers with integrated software/services and shorten new-product cycles to stay ahead of low-cost cannibalization.
-
Supply-chain fragility is now a business strategy variable — The semiconductor disruptions of 2021–2022 exposed concentrated foundry dependencies and long lead times for specialized capture ASICs and high-speed SerDes components. For 2026, companies must treat advanced component access as a strategic asset: dual-sourcing, design-for-availability (DFx), and pre-allocated capacity agreements will materially alter time-to-market and gross margin outcomes.
-
Regulatory and data-localization complexities — Increasingly stringent data localization and privacy rules in multiple jurisdictions are influencing system architecture decisions for video ingestion and edge processing. Enterprises purchasing capture solutions need to evaluate whether vendors can offer localized firmware, on-prem ingest with controlled telemetry, and contractual guarantees to avoid regulatory friction.
-
Concentration and competitive balance — The market demonstrates moderate-to-high concentration among several established vendors, creating an environment where nimble challengers and aggressive OEMs can win share through price, niche performance advantages, or bundled ecosystems. We identify tactical windows for partnerships and tuck-in acquisitions that can accelerate enterprise reach or technical capability.
Reading the competitive landscape
-
Magewell (Nanjing) — Strategic posture: product-led with a broad capture family across PCIe, USB and M.2. Strengths include a wide validated device matrix and a steady cadence of product launches (notably a high-bandwidth USB Capture SDI 4K Pro announced at NAB 2025). Implication: Magewell is positioned to defend professional and prosumer customers who value interoperability and rapid integration; competitors must match software ecosystem compatibility to compete effectively.
-
Datapath (Derby, UK) — Strategic posture: high-performance multi-channel capture for complex AV installations. Strengths lie in multi-input scalability and enterprise-grade support. Implication: Datapath is the default for high-density, mission-critical deployments; new entrants should target adjacent value-adds such as integrated analytics to unbundle share.
-
Blackmagic Design (Melbourne) — Strategic posture: strong appeal to creative professionals with high-fidelity DeckLink PCIe cards supporting up to 8K workflows. Strengths include brand-recognition in production ecosystems and a product set that spans ingest/playback. Implication: Blackmagic’s positioning creates a premium benchmark; rivals must either match technical specs or pivot to specialized vertical integrations (e.g., medical imaging certifications).
-
Anyoyo (China) — Strategic posture: cost-competitive USB capture cards targeted at streaming and gaming. Strengths include aggressive price points and fast time-to-market. Implication: They continue to compress entry-level margins; incumbents will need service differentiation or channel exclusivity to preserve ASPs at the lower end.
Strategic priorities for 2026 (recommended actions)
-
Secure critical components now — Negotiate capacity or long-lead commitments for any ASICs, high-speed SerDes, and specialized FPGA capacity that underpin next-generation capture features. Model the P&L implications of pre-booking versus spot procurement across high/low demand scenarios.
-
Productize software and services — Bundle capture hardware with firmware-driven differentiation, cloud connectors, and latency-optimized SDKs to create recurring revenue and increase switching costs.
-
Adopt a two-track GTM — Maintain channel breadth for volume capture devices while deploying a direct, solution-sales team for enterprise and regulated verticals that require certification and customization. Use tiered warranties and support SLAs as monetizable levers.
-
Pursue targeted M&A or partnerships — Prioritize acquisitions that fill gaps in software, AI-driven analytics, or regional compliance capabilities. For pure-play hardware vendors, partnering with CDN/cloud or UC-platform providers accelerates market penetration for latencysensitive applications.
-
Invest in compliance-by-design — For enterprise customers operating across jurisdictions, offer deployment templates and contractual commitments that address data residency, firmware auditability, and telemetry minimization.
-
Differentiate through performance certs — Invest in independent third-party validation (latency, color fidelity, multi-channel sync) to create defensible procurement advantages for broadcast and medical buyers.
How PW Consulting’s report supports execution
-
Scenario-ready market models: Translate the study’s growth trajectories and supply scenarios into bespoke forecasts for your product lines or geographic priorities.
-
Supplier-risk heatmap: Rapidly identify single points of failure and quantify mitigation costs under three sourcing strategies.
-
Commercial playbooks: Pre-built pricing ladders, warranty structures and channel commission templates calibrated to maintain revenue per unit in an increasingly price-sensitive environment.
-
M&A screening filters: Priority criteria and scorecards derived from technical fit, go-to-market synergies, and integration risk to accelerate 90-day diligence.
In short, the Image Capture Cards market offers compelling upside for firms that combine product differentiation with pragmatic supply-chain strategy and regulatory-aware deployment architectures. The market’s near-term expansion is clear from our base-year and forecast figures, but value capture in 2026 will be uneven: winners will be those who insulate critical inputs, monetize software and services, and make disciplined channel and M&A choices.
This brief surfaces the strategic thrusts and near-term actions. For the granular breakdowns, proprietary segmentation, and the suite of decision-support tools referenced above, access the full PW Consulting report and interactive models on our site. The report will provide the detailed segment economics and downloadable assets you need to convert the market’s growth into sustainable enterprise advantage.
For detailed analysis of this topic, please visit the official page: Image Capture Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Illite Market 2026 Strategic Brief: Navigating Growth, Supply Risk, and High‑Value Applications
Executive snapshot
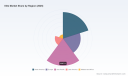
As companies prepare strategic decisions for 2026, the illite market is entering a phase characterized by steady expansion, selective premiumization and evolving supply‑chain risk. Our PW Consulting Illite Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — projects clear, actionable inflection points for procurement leaders, product strategists, and corporate development teams. The global market has expanded consistently during the historical window and, under our baseline projection, continues on a multiyear growth path driven by higher‑value industrial applications and disciplined downstream adoption. Over the forecast period, the market trajectory corresponds to a compound annual growth rate of 6.98% — a pace that supports prioritized investment but that also exposes firms to concentration and regulatory vectors that will shape winners and laggards.
Illite Market
Why 2026 is a decisive year
-
Base‑year calibration: 2025 serves as the analytical base year in our study, reflecting the most recent structural shifts in supply, demand and policy.
Illite Market -
Transition to premium applications: Illite’s role is evolving beyond commodity filler uses toward higher‑margin segments where surface treatment, particle engineering and trace impurity control materially impact value capture.
Illite Market -
Policy and trade inflection points: Multiple regulatory drivers — from tariff regimes to evolving waste shipment rules and export controls — are reshaping the economics and resilience requirements of global procurement strategies.
Market trajectory — a concise data view
Under the baseline forecast, the global illite market grows from a mid‑hundreds USD million scale in 2025 and reaches several hundreds of millions by the end of the 2026–2032 horizon. The forecast incorporates macro demand catalysts in electronics, specialty coatings and advanced manufacturing, and assumes continued industrial recovery across key end markets. The 6.98% CAGR we report for the forecast period signals a market that is attractive for targeted capacity expansion and premium product development, while remaining sensitive to shifts in upstream supply composition and trade policy.
What the PW Consulting report contains (practical, actionable deliverables)
-
High‑resolution forecasting: Granular, scenario‑based projections across our forecast horizon with bottoms‑up demand drivers, sensitivity ranges and clear assumptions — designed to be plugged directly into investment and procurement models.
-
Commercial playbooks: Go‑to market and pricing frameworks for manufacturers and distributors that map product attributes (purity, micronization, surface treatment) to achievable margin tiers and channel strategies.
-
Supply‑chain mapping: A proprietary supplier map and tiering model that identifies sourcing risk nodes, near‑term capacity constraints, and logistical choke points — coupled with tactical levers for resilience (dual sourcing, geographic hedging, and strategic inventory).
-
Regulatory impact matrix: Practical assessments of tariffs, waste shipment rules and export controls, with scenario playbooks that translate regulatory moves into procurement, compliance and contract strategies.
-
M&A and partnership guidance: Screening criteria for target selection, valuation sensitivity to feedstock quality and processing prowess, and integration checklists for bolt‑on and capability acquisitions.
-
Technical appendix: Evaluation protocols for product qualification in sensitive end uses (e.g., electronics and cosmetics), including recommended test methods and acceptance thresholds to accelerate qualification cycles.
Competitive landscape — who to watch
The illite sector remains fragmented at the producer level with a modest level of concentration among larger suppliers. Our competitive analysis focuses on a mix of vertically integrated miners, regional specialists and value‑added processors. Notable players covered in the study include:
-
Chengde Rehe Mining (Chengde, Hebei Province, China) — Primary producer and processor offering natural illite ore and powder products across industrial, cosmetic and feed applications. Website: http://blcitu.com.cn
-
Yonggung Illite (Yonggung, South Korea) — Specialist producer focused on high‑purity grades tailored for coatings, rubber and plastics.
-
Sunwoo Illite (South Korea) — Manufacturer and distributor supplying mineral products across multiple industrial sectors with regional distribution strength.
-
Guangzhou Teamgo (Guangzhou, Guangdong Province, China) — Supplier of illite powders and related mineral products under the Teamgo brand. Website: http://www.teamgo.com.cn/
-
Lingshou County Antai Mining (Lingshou County, Hebei Province, China) — Producer of mica powders and illite‑based products offering full‑service capabilities. Website: http://www.antaiky.com
-
Chifeng Hengyuan Mineral (Chifeng, Inner Mongolia, China) — Active supplier of mineral products for industrial applications.
-
Hebei Jing Hang Mineral (Shijiazhuang, Hebei Province, China) — Producer of mineral powders including illite. Website: http://jinghangkc.cn
-
Micron Solutions (United States) — Supplier of micronized mineral products, including illite, for specialty applications. Website: www.micronsolutions.com
Market concentration metrics in our analysis show a low to moderate aggregation at the top (CR3 and CR5 measures are included in the report), indicating ample room for consolidation and premium differentiation — but also signaling potential supply consolidation risks for buyers focused on narrow specifications.
Recent market moves and why they matter
-
Product innovation: Several companies have launched surface‑modified or eco‑engineered illite variants that enable new performance claims in coatings and UV resistance — accelerating upstream requirements for suppliers to offer treated powders rather than raw ore.
- M&A and capacity shifts: Acquisition activity and capacity expansions targeted at premium, high‑purity powders are reshaping the supply map for pharmaceutical and cosmetic customers; such moves materially shorten qualification timelines for vertically integrated buyers.
- Regional production strategies: Mining expansions in Southeast Asia and new proprietary synthetic processes in Europe are diversifying the sources available to sensitive end users and changing freight and inventory calculus for global buyers.
Strategic implications for 2026 decision‑makers
-
Procurement: Move from spot sourcing to a tiered contracting model. Secure continuity with framework agreements that include quality gates and escalation mechanisms tied to surface‑treatment capabilities. Incorporate lead‑time premiums and clause templates for regulatory shocks.
-
Product development: Prioritize qualification of surface‑modified and micronized variants for higher‑margin applications. Small chemistry and formulation teams can unlock disproportionate value by co‑designing illite grades with suppliers.
-
Investment and M&A: Target assets that combine feedstock access with downstream processing (micronization, surface modification). Our financial models show that control over the value‑added processing step materially compresses time‑to‑market for premium product lines.
-
Regulatory posture: Build an early warning and contractual compliance playbook for tariff and export‑control scenarios. The EU waste shipment rules and evolving export regimes require preemptive reengineering of logistics and vendor qualification workflows.
-
Risk management: Quantify single‑point failures at the supplier and logistics level. Scenario exercises in the report translate supply disruption probabilities into inventory buffer and multi‑sourcing thresholds commensurate with application criticality.
Risk scenarios — what we model and how to use it
Our scenario suite models three pathways: base (steady growth at the reported CAGR), conservative (downside shocks from trade measures and demand softening) and accelerated premiumization (stronger adoption in electronics and cosmetics). For each scenario we provide procurement actions, capex triggers, and KPI dashboards that executives can adopt within 30–60 days to align budgets and contracts with likely outcomes.
How to use the full report
-
For procurement leaders: deploy the supplier map and resilience playbook to renegotiate tiered contracts and set certification milestones.
-
For product teams: use the technical appendix and qualification checklists to cut pilot cycles and reduce time‑to‑revenue for new formulations.
-
For strategy and M&A teams: the valuation sensitivity annex and target screening matrices support rapid target prioritization and fast‑track due diligence.
Final note — the trailer principle
This brief surfaces the analytical backbone and strategic recommendations from PW Consulting’s Illite Market study while intentionally withholding specific segment splits and proprietary tables from this preview. The full report contains the detailed regional and application breakdowns, supplier scorecards, transaction comparables, and downloadable forecast models that will allow your team to operationalize the insights above. If you are preparing sourcing, product or investment decisions for 2026, the full analysis will supply the exact figures, supplier rankings and contractual templates needed to move from strategy to execution.
To access the complete study, models and interactive supplier map, visit PW Consulting’s Illite Market page or contact our industry desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Illite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Camera Module Adhesives Market to Reach USD 523.27 Million in 2025
By pmarketresearch, 2026-07-13
Camera Module Adhesives Market — Strategic Preview for 2026 Decision-Makers
As companies calibrate strategies for 2026, the camera module adhesives market presents a distinct mix of steady growth, regulatory pressure and technology-driven product differentiation. PW Consulting’s forthcoming in-depth study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes primary research, cost and formulation analytics, and competitive intelligence to give procurement, R&D and corporate development leaders an operational roadmap for near-term and medium-term choices.
Camera Module Adhesives Market
Why this market matters in 2026
-
Durable, low-defect optical assemblies remain a gating factor for smartphone cameras, advanced ADAS/automotive cameras, and a widening set of industrial and medical imaging modules.
Camera Module Adhesives Market -
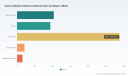
After five years of steady expansion, the overall market shows a clear upward trajectory — reflecting both higher per-module adhesive performance requirements and incremental unit demand from new end-markets. PW Consulting’s topline model pegs the global market at USD 523.3 Million in 2025, with a compound annual growth rate of 6.9% through the 2026–2032 forecast horizon.
Camera Module Adhesives Market -
The combination of material innovation (low-shrink, dual-cure chemistries), process acceleration (active alignment workflows), and regulatory reformulation (VOC limits, REACH/RoHS compliance) creates simultaneous risk and opportunity for material suppliers and OEMs.
What the 2026 strategist needs to know — high-level takeaways
-
Growth is predictable but selective: the market trajectory is upward and resilient to short-term end-market shocks, yet value accrues unevenly — premium formulations that enable higher throughput and reduced rework capture disproportionate margin.
-
Competitive positioning hinges on technical depth: suppliers that combine formulation expertise (UV/dual-cure, low-temperature systems) with application engineering for active alignment win design wins and lock in longer-term volume contracts.
-
Regulatory and trade dynamics are non-negotiable inputs: compliance and supply-chain locality will influence cost curves and customer selection criteria in 2026 more strongly than in prior cycles.
-
Market concentration is meaningful but not monopolistic: top suppliers account for a material share of global revenues, leaving room for differentiated entrants leveraging niche chemistries or service-led commercialization models.
How PW Consulting’s study helps executives make decisions in 2026
-
Prioritize capital allocation: our scenario-driven market sizing (base year 2025) and 6.9% CAGR projection enable CFOs to stress-test investment cases for capacity expansion, pilot R&D, or M&A.
-
Design procurement strategy: we map supply risk against tariff exposures and raw-material sourcing constraints, letting sourcing teams weigh localization versus global sourcing and identify near-term hedging priorities.
-
Inform product roadmap choices: R&D leaders receive a taxonomy of adhesive attributes with quantified performance trade-offs (cure speed vs. shrinkage vs. thermal stability) and suggested go/no-go thresholds for automotive-grade qualification.
-
Shape commercial tactics: the report translates technical differentials into commercial levers — value-based pricing, bundling of application engineering services, and warranty structures aligned to customers’ yield improvement targets.
What’s inside the report — actionable, practice-oriented content
-
Market model and scenarios: a base-case and two alternative scenarios through 2032, with sensitivity testing on unit mix, ASP trends, and regulatory cost pass-through assumptions.
-
Cost and formulation deep dives: bill-of-materials templates, margin waterfall analyses, and estimated incremental cost of compliance for reformulation to VOC/REACH/RoHS standards.
-
Supplier scorecards and heatmaps: qualitative and quantitative assessments across technical capability, scale, geographic footprint, regulatory readiness and partnering posture.
-
Competitive playbooks: battle-tested commercial strategies for suppliers and OEMs — from rapid qualification pilots to locked-in supply contracts with tiered pricing tied to yield metrics.
-
Regulatory risk matrix and compliance roadmap: actionable steps to adapt formulations, documentation and supply-chain traceability to meet EU General Safety Regulation, REACH, RoHS and other regional requirements.
-
Go-to-market templates for new chemistries: recommended pilot designs, qualification milestones, and OEE improvement KPIs to accelerate adoption in both consumer and automotive channels.
Competitive landscape — what to watch in 2026
-
Supplier differentiation is rooted in both chemistry and service. Market leaders maintain portfolios that span light-curable epoxies, dual-cure systems and low-temperature UV formulations — enabling them to support active alignment workflows and heat-sensitive assemblies.
-
Representative players earning strategic mentions in our analysis include established names with distinct advantages: a US-based innovator with strength in light-curable optical epoxies and recent product introductions focused on low-shrink active alignment; Japanese specialists with depth in insulating and camera-module adhesives tailored to fixed- and autofocus modules; German firms advancing dual-cure and UV systems for first-lens bonding in demanding environments; and legacy formulators offering low-temperature, UV-cure chemistries for sensitive assemblies.
-
Recent corporate actions signal tactical plays to watch: a lease renewal underscored a US supplier’s commitment to local operations (July 2025); a German adhesive manufacturer launched new dual-cure and UV products optimized for first-lens bonding (January 2026); and another US innovator announced a next-generation low-shrink active-alignment epoxy (May 2026). These moves illustrate a two-track dynamic — supply-side investments in both innovation and operational stability.
Regulatory, tariff and supply-chain factors shaping 2026 strategy
-
Regulatory tightening: the EU’s General Safety Regulation (effective July 2024) and ongoing REACH/RoHS enforcement accelerate reformulation and documentation requirements. Firms that front-load compliance see shorter qualification cycles with conservative automotive customers.
-
Tariff-driven cost recalibration: elevated duties on imported specialty resins and curing agents introduced in 2025 (notably in the US) are reshaping vendor selection and prompting some buyers to pursue near-shoring, dual sourcing, or qualified domestic alternatives.
-
Labor and compliance expense pressure: transforming solvent-based products into compliant low-VOC formulations increases both direct reformulation costs and indirect labor/compliance overhead — an input we explicitly model in supplier margin scenarios.
Strategic playbook — recommended actions for 2026
-
For OEMs and integrators: lock in design-win roadmaps tied to adhesive performance payoffs (throughput, yield, reliability). Negotiate performance-based supply agreements that share upside from yield improvements and protect against raw-material cost spikes.
-
For suppliers: prioritize modular go-to-market offers — combine differentiated chemistries with application engineering and qualification accelerators. Invest selectively in capacity where regulatory-favored geographies and customer clusters justify capital spend.
-
For investors and M&A teams: target assets that bring either scarce chemistries (e.g., fast-curing, low-shrink epoxies) or embedded application engineering relationships with OEMs; use PW Consulting’s supplier scorecards and concentration metrics to refine target lists and valuation assumptions.
-
Cross-cutting: build a regulatory-control tower to track REACH/RoHS/General Safety updates and to operationalize rapid reformulation pathways — this reduces time-to-market for compliant variants and limits revenue exposure from sudden regulatory enforcement.
Why PW Consulting’s intelligence is different
-
Integrated engineering-commercial lens: we marry lab-validated performance trade-off curves with commercial pricing and warranty constructs so teams can translate chemical improvements into wallet-share gains.
-
Actionable templates: rather than only high-level forecasting, the study includes supplier scorecards, cost build-up models and qualification playbooks ready to be adapted by procurement, R&D and BD teams.
-
Proven scenario methodology: our base case (anchored to 2025 data) and 6.9% CAGR forecast extends to 2032 and includes tailored downside/upside paths that reflect tariff shocks, rapid re-platforming to new module architectures, or sudden regulatory tightening.
Next step — where to find the missing details
This preview sketches the strategic contours that will determine winners and laggards through 2026. For confidentiality and clarity, this article intentionally omits granular regional and application split details that are included in the full study — data that executives rely on to justify capital projects, contract negotiations and M&A bids. Access to the complete PW Consulting Camera Module Adhesives Market report provides the full quantitative breakdowns, supplier-level scorecards, and downloadable scenario models that operational teams use to execute decisions with confidence.
Contact PW Consulting to obtain the complete report, request bespoke modeling for your product portfolio, or schedule a strategic briefing tailored to your role (procurement, R&D, corporate development). In a market growing from a mid-single-digit base into the early 2030s with a 6.9% CAGR, the difference between leading and lagging strategies will be set by how teams translate material science into predictable manufacturing and commercial advantage.
For detailed analysis of this topic, please visit the official page: Camera Module Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Tool Switches Market to Hit USD 1.21B by 2032 at 4.8% CAGR - PW Consulting
By pmarketresearch, 2026-07-13
Power Tool Switches Market: Strategic Outlook for 2026 — A PW Consulting Industry Preview
Why this briefing matters for 2026 decision-makers
As companies reset product roadmaps, procurement strategies, and M&A pipelines for 2026, the humble switch — the user interface and electrical gateway inside every power tool — is increasingly a strategic lever. This PW Consulting preview synthesizes macro trajectories, competitive posture, regulatory risk, and practical playbooks so senior leaders can prioritize near-term investments with confidence. We demonstrate the analytical depth behind our full study while deliberately withholding the granular segment matrices that are available in the complete report to preserve its commercial value.
Power Tool Switches Market
Market trajectory — the numbers that frame strategy
At the aggregate level, the Power Tool Switches market has shown steady expansion over the 2020–2025 historical window and remains on an upward path through our 2026–2032 forecast horizon. Using 2025 as the base year, the market recorded consistent year-on-year growth, and our modeling indicates a compound annual growth rate (CAGR) of approximately 4.8% across the forecast period. The total market value moves from mid-single-digit growth in the early 2020s into stronger absolute scale by the early 2030s, reflecting the twin forces of tool electrification and growing replacement/aftermarket activity. These macro dynamics make switches a non-trivial contributor to product profitability and customer experience for OEMs and aftermarket suppliers alike.
Power Tool Switches Market
Structural dynamics shaping supplier and OEM choices
-
Electrification and control complexity: The proliferation of brushless motors, higher-voltage battery platforms, and intelligent battery management pushes switches from simple mechanical contacts toward electronically mediated controls and integrated safety logic. Product teams must evaluate modular electronic switch solutions that can be tuned across multiple platforms.
Power Tool Switches Market -
Regulatory and compliance overlay: Safety standards such as UL 745 and IEC 62841 remain binding for hand‑held tools, while electromagnetic compatibility requirements (e.g., EN 55014-1) and regional conformity regimes continue to shape design and testing timelines. The UK/CE marking arrangements and recent compliance clarifications require procurement and product teams to bake certification timelines into launch plans.
-
Input-cost volatility: Reported fluctuations in steel and engineered plastics prices introduce margin risk for both branded OEMs and contract manufacturers. Cost engineering and supplier hedging are now operational priorities for 2026.
-
Market fragmentation and concentration: The competitive structure shows a moderate level of concentration — no single supplier dominates the global market. This fragmentation creates opportunities for specialization, vertical integration, and strategic partnerships, but it also requires disciplined supplier qualification to ensure reliability at scale.
-
Service and aftermarket economics: End‑user expectations for repairability and spare parts availability amplify the importance of interchangeability standards and robust distribution strategies for switches and modules.
Competitive landscape — what leading players are prioritizing
The vendor field spans global OEM powerhouses, premium system suppliers, value brands, and specialized switch manufacturers. High‑level positioning is as follows:
-
Bosch — Focuses on integrating robust trigger and electronic control switches into brushless cordless platforms, with emphasis on battery protection and system-level integration for professional-grade tools.
-
Makita — Leverages ergonomic variable-speed triggers and proprietary cordless ecosystems to retain platform loyalty; product teams emphasize user feel and system compatibility.
-
DeWalt (Stanley Black & Decker) — Emphasizes ruggedization and heavy-duty switch architectures for trade-focused tools, targeting durability under high duty cycles.
-
Milwaukee — Positions switches as part of a disruptive cordless systems strategy, engineering controls for professional workflows and rapid innovation cycles.
-
Hitachi Power Tools (Metabo HPT / HiKOKI) and Metabo — Prioritize long-term reliability and safety-focused switch designs for harsh environments.
-
Festool, Hilti — Target precision and premium construction markets where tight integration between switches and system-level tool controls is a differentiator.
-
Ryobi, Black & Decker — Compete on value and wide distribution, optimizing switch cost and usability for consumer and prosumer segments.
-
Ningbo CPX, FBelec, Superior Electric — Specialist suppliers and aftermarket-focused manufacturers that offer adaptable trigger modules, safety switches, and replacement parts across OEMs.
Tactically, leaders balance system integration (battery and motor electronics), ergonomic differentiation, and robust supply chains. Niche and specialty suppliers compete on certification speed, customization, and cost competitiveness.
What’s inside the PW Consulting Power Tool Switches report (practical deliverables)
The full study is built for operational use across R&D, procurement, corporate development, and distribution channels. Highlights include:
- Executive summary and strategic implications tailored to C-suite decision points.
- Historical market sizing (2020–2025) and forward-looking projections (2026–2032) with scenario variants anchored to a 4.8% baseline CAGR.
- Technology and product taxonomy that separates mechanical, electro-mechanical, and electronic switch families, with a feature‑function mapping for control, safety, and system compatibility.
- Supply‑chain and cost‑build breakdowns, including bill of materials sensitivity to steel and polymer price moves and supplier risk heat maps.
- Regulatory compliance checklist and recommended certification timelines for major markets.
- Vendor scorecards and competitive benchmarking that combine capability, scale, certification, and route‑to‑market metrics (detailed vendor-level scoring available in the full report).
- Go‑to‑market playbooks for OEMs, aftermarket suppliers, and private-label manufacturers with channel-specific commercial templates.
- M&A and partnership screening framework, including valuation levers, synergy maps, and a short list of targets by strategic archetype.
- Interactive dashboards and scenario simulators that let teams stress-test price, volume, and compliance assumptions (note: granular segment matrices and downloadable datasets are available in the paid version).
Actionable strategic priorities for 2026
-
Prioritize modular electronic switch platforms that enable rapid tuning across battery platforms and motor types; this reduces SKUs and accelerates time-to-market.
-
Embed compliance milestones (UL/IEC/EMC and market-specific conformity) into product development timelines to avoid launch slippage and costly redesigns.
-
Diversify supply sources and qualify second‑source suppliers to mitigate raw-material and geopolitical disruptions. For high-volume SKUs, bilateral hedging and longer-term purchase agreements can reduce margin volatility.
-
Invest selectively in smart-switch capabilities (diagnostics, usage telemetry, and predictive failure modes) where aftermarket monetization or fleet management value is clear.
-
Use the fragmentation of the supply base as a basis for strategic partnerships and tuck‑in M&A to secure critical competencies (e.g., integrated safety modules, battery‑aware controls).
-
Architect for serviceability: Design switch modules to be replaceable with clear spare‑parts channels and cross-reference tables to capture aftermarket revenue and prolong tool lifecycles.
How senior teams should use this report in 2026 boardrooms
For corporate strategy, the study is a decision-grade input for capital allocation and M&A thesis validation. For product management, it informs platform choices and certification roadmaps. For procurement, it is a benchmark for supplier qualification, total-cost modeling, and negotiation levers linked to raw-material exposure. Finally, for commercial teams, the report surfaces go-to-market segmentation and aftermarket opportunities that materially affect topline growth and margin mix.
Conclusion — the strategic value proposition
Power tool switches are no longer a commodity afterthought; they sit at the intersection of ergonomics, safety, electronics, and system integration. With a steady market expansion framed by a 4.8% CAGR and ongoing technology and regulatory complexity, the choices organizations make in 2026 about switch platform architecture, supplier partnerships, and compliance investment will have multi-year financial and competitive consequences. This PW Consulting preview demonstrates the range of analysis and practical tools that buyers of the full report will receive. For the detailed segmentation matrices, vendor scorecards, and interactive scenario workbooks that underpin board-level recommendations, access the full report on our website.
For detailed analysis of this topic, please visit the official page: Power Tool Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
3D Secure Market Poised for 11.78% CAGR to $2,325M by 2032 — PW Consulting Insight
By pmarketresearch, 2026-07-13
3D Secure Authentication Market — Strategic Briefing for 2026 Decisions
As digital commerce and regulatory demands converge, 3D Secure (3DS) authentication has transitioned from a technical add-on to a strategic control point for issuers, acquirers, merchants, and platform providers. This briefing previews our full PW Consulting market study on the 3D Secure Authentication Market (base year 2025) and explains why the analysis will be indispensable for enterprise decision-making in 2026. We present the macro trajectory, regulatory inflection points, competitive dynamics, and the practical levers C-suite and product leaders must act on — while reserving the granular segmentation and proprietary scorecards for the full report.
3D Secure Authentication Market
Why 3DS matters for 2026 strategy
-
Compliance meets conversion: EMV 3DS has become a primary mechanism for meeting Strong Customer Authentication (SCA) requirements in regulated markets while also shaping checkout friction and fraud economics. The decisions you make in 2026 about 3DS implementation will directly affect authorization rates, liability exposure, and customer experience.
3D Secure Authentication Market -
Market scale and momentum: The market is on a sustained growth trajectory. From the 2025 base year, the industry is projected to expand at an approximate compound annual growth rate (CAGR) of 11.78% through the forecast horizon, more than doubling in size by the end of the period. That pace implies both expanding opportunity and accelerating vendor activity — decisions taken in 2026 will determine whether your organization captures upside or incurs rework costs.
3D Secure Authentication Market -
Concentration and partner selection: The market shows meaningful concentration among a small number of certified vendors; top-tier providers maintain large shares of capability and channel relationships. A clear, defensible partner strategy is therefore required to balance cost, time-to-market and strategic independence.
Macro view: growth, timing and investment priorities
Our base-year analysis (2025) positions the 3DS authentication market as a mature but still fast-growing segment within payments security. The growth profile—driven by regulatory reinforcement, wider SDK adoption on mobile platforms, and an expanded set of use cases beyond pure card-not-present (CNP) transactions—creates a predictable investment window. Organizations should treat 2026 as a strategic inflection year in which to:
-
Finalize multi-vendor roadmaps for SDK and server components to support both mobile-first commerce and legacy integration.
-
Allocate budget for certified product upgrades and operational testing tied to the latest EMVCo bulletins and protocol clarifications.
-
Integrate 3DS decisions into broader payment modernization initiatives (tokenization, issuer scoring, fraud orchestration) to avoid duplicated effort and costs.
Regulatory and standards catalysts
Regulatory guidance continues to be a primary driver for enterprise adoption. Recent EMVCo releases in 2025 refined SDK and protocol specifications and clarified core functions relevant to SCA compliance. European regulatory bodies continue to recognise EMV 3DS as a valid SCA mechanism where implemented appropriately. For 2026 planning, enterprises must align product roadmaps and testing calendars to these specification bulletins to ensure uninterrupted certification, liability management and interoperability with card schemes.
Competitive landscape — what to watch
The market features a mix of specialized fintechs and incumbent security providers. Certification and interoperability are critical differentiators, so vendor profiles emphasize EMVCo-approved SDKs, ACS/DS and server components, and cross-scheme compatibility.
-
n software, Inc. (Chapel Hill, US): A supplier with recent EMVCo certifications across mobile SDKs and server builds; notable for rapid revision cycles aligned to EMVCo updates.
-
2C2P Pte Ltd (Singapore): A payments platform provider offering end-to-end certified server and ACS capabilities suited for regional processors and gateways.
-
3dsecure.io ApS (Aarhus, Denmark): A focused supplier of certified 3DS server solutions, positioned for integration with EU and global merchants emphasizing developer-friendly tooling.
-
A360 DOO BEOGRAD (Belgrade, Serbia): Emerging provider with certified DS and server offerings targeting cross-border service providers.
-
Adyen N.V. (Amsterdam, Netherlands): Global payments integrator delivering certified SDKs as part of a broader merchant acquirer and gateway service stack.
-
GPayments (Australia), Modirum, Netcetera, Thales Group, Entrust Corporation and SISA Information Security: A mix of specialists and large security vendors providing certified components or managed services; their strategies range from modular SDKs to fully managed ACS solutions.
Recent product approvals and EMVCo specification bulletins released in 2025 highlight an active compliance and product upgrade environment. Purchasers must therefore factor certification timelines and maintenance cycles into procurement and integration schedules.
What our full study includes (practical, actionable modules)
The full PW Consulting report is structured to move executive teams from awareness to implementation. Key deliverables include:
-
Market sizing and growth modeling — scenario-based forecasts to stress-test investment cases under differing regulatory and fraud-rate trajectories.
-
Vendor assessment framework — a scored matrix combining technical certification status, interoperability, deployment models (gateway, SDK, ACS, DS), regional support, and commercial terms. Note: proprietary vendor scores and detailed regional splits are available in the full report.
-
Integration playbooks — step-by-step guidance for SDK deployment (Android/iOS), server and ACS integration, testing, certification timelines, and fall-back mechanisms to preserve conversion.
-
MVP vs enterprise roadmap templates — recommended phasing for pilots, scale roll-outs, and migration from legacy 3DS versions to supported protocol baselines aligned with EMVCo bulletins.
-
Compliance checklist — practical SCA alignment activities, evidence requirements for regulators and auditors, and best practices for liability management with card schemes.
-
Commercial models & TCO — templated cost models for SaaS vs on-prem deployments, including vendor maintenance, certification renewals and operational testing costs over a multi-year horizon.
-
Operational KPIs and fraud-economic dashboards — recommended metrics to track authorization uplift, false declines, friction index, fraud loss per transaction and incremental revenue effects.
-
Negotiation playbook — contract clauses, SLAs, certification commitments and exit provisions to reduce vendor lock-in and minimize risk during upgrades.
Practical recommendations for 2026 planning cycles
-
Audit your current 3DS maturity against the latest EMVCo specification bulletins. Establish a certification calendar that accounts for SDK refreshes and server-level testing windows.
-
Adopt a modular implementation approach. Separate SDK, server/ACS, and orchestration layers to enable vendor substitution and selective upgrades without full-stack rewrites.
-
Design for mobile-first checkout. Prioritize SDKs validated on modern mobile OS versions and factor in session continuity across app/web environments.
-
Integrate fraud orchestration early. Use 3DS signals as part of a broader decisioning fabric combining device intelligence, issuer signals and third-party risk feeds to maximize friction reduction.
-
Negotiate certification commitments and upgrade paths with suppliers. Given the market’s concentration among certified providers, secure clear SLAs for protocol updates and re-certifications.
-
Measure business outcomes, not just technical compliance. Tie 3DS projects to authorization rates, dispute trends and checkout conversion metrics to justify ongoing investment.
What the PW Consulting “trailer” leaves for the full report
To preserve strategic advantage while delivering confident orientation, this briefing shares the market’s growth rate, concentration signals, and competitive context. The full PW Consulting 3D Secure Authentication Market report contains the granular regional and application-level splits, vendor scorecards, modeled TCOs, and downloadable procurement templates that enterprise teams require for execution. These datasets and proprietary analyses are intentionally withheld in this preview to ensure subscribers receive the actionable intelligence they need to move from planning to deployment with confidence.
Final note — timing and next steps
If your organization is budgeting or revising payments-security roadmaps in 2026, treat this year as a pivotal window for committing to certified implementations, negotiating vendor arrangements, and embedding 3DS signals into fraud decisioning and customer experience optimization. The market’s compound growth trajectory and concentrated vendor landscape mean early, disciplined action will secure disproportionate downstream benefits.
For teams ready to operationalize: the full report provides the step-by-step playbooks, vendor comparatives and forecast models required to prioritize projects, de-risk rollouts, and quantify ROI. PW Consulting stands ready to support tailored workshops, vendor selection facilitation and implementation oversight to convert this strategic briefing into measurable outcomes.
For detailed analysis of this topic, please visit the official page: 3D Secure Authentication Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ETFE Membrane Market Poised for 8.8% CAGR Through 2032
By pmarketresearch, 2026-07-13
ETFE Membrane Market: Strategic Imperatives for 2026
As an executive-level primer from PW Consulting, this paper distills the strategic value of our full ETFE Membrane Market study for decision-makers planning activity in 2026. The market has progressed from a modest niche into a commercially meaningful segment: worldwide ETFE membrane revenue rose materially across the 2020–2025 historical window (roughly doubling in that period) and reached an estimated USD 215.0 Million in our base year (2025). Under our base forecast the market grows at a compound annual growth rate (CAGR) of 8.8% through 2032, reaching approximately USD 409.1 Million by the end of the forecast horizon. These macro dynamics create immediate tactical questions for procurement, product development, project investors, and integrators. This note explains the actionable insights the full report delivers, the strategic choices it enables in 2026, and the competitive signals to monitor—while intentionally withholding detailed segment tables and regional splits to encourage review of the full analysis.
ETFE Membrane Market
Why this study matters for 2026 decision cycles
-
Timing for capital allocation: The market’s mid-single-digit-to-high-single-digit CAGR and doubling since 2020 signal a maturing product lifecycle. Firms evaluating factory expansions, line investments, or vertical integration need a granular timing view—knowing when demand density supports expansion is the core value this study supplies.
ETFE Membrane Market -
Supplier and feedstock risk management: ETFE is a specialty fluoropolymer whose upstream dynamics (resin capacity, proprietary grades, UV-stabilized chemistries) materially affect cost, lead times, and product differentiation. Strategic sourcing decisions in 2026 require scenario-tested supplier continuity plans—something the report maps in detail.
ETFE Membrane Market -
Regulatory and standards-driven adoption: Standardization (e.g., recent standards for tensioned membrane structures) and specification updates are shifting how designers and owners qualify ETFE systems. The report translates those changes into procurement checklists and acceptance criteria for 2026 tenders.
-
M&A and partnership sourcing: As the industry evolves, opportunities are emerging to buy capability (film manufacture) vs. capability to install (integrators and system houses). The analysis provides a decision framework to prioritize targets in 2026 based on integration value and risk.
What the full report delivers — practical, transaction-ready content
-
Market sizing and validated forecast model (base year 2025; forecast period 2026–2032) with scenario analysis (base, upside, downside) and sensitivity to resin pricing and project deployment rates.
-
Bottom-up project pipeline mapping: active and recently completed projects, near-term project wins, and a convertibility assessment that shows how much of the pipeline is likely to translate into procurement in 0–12, 12–36 and 36+ month windows.
-
Supply chain and cost-to-serve breakdowns: raw material inputs, conversion costs, logistics risk points, and margin waterfalls for film producers vs. system integrators.
-
Vendor due diligence templates and scorecards for sourcing teams—ready to plug into RFPs and supplier qualification processes.
-
Technology and product roadmap: evaluation of differentiated grades (UV-stabilized films, multi-layer constructions, coated finishes), including implications for lifecycle, warranties and total cost of ownership.
-
Regulatory impact assessment and compliance playbook aligned to recent standards affecting tensioned membranes and welded connections.
-
M&A screening and valuation sensitivity models calibrated to ETFE-specific KPIs (manufacturing utilization, film gauge mix, downstream installation capability).
Competitive landscape — who matters and what to watch in 2026
The market is characterized by specialized material suppliers, resin producers, and system integrators. Our report includes in-depth profiles, strategic intent assessment, and watch-lists for each firm. Highlights of the types of players covered:
-
Specialized film manufacturers with legacy expertise and branded product lines—monitor their capacity footprints, innovation pipelines (e.g., high-UV-resistance grades), and backward integration into resin sourcing.
-
Global fluoropolymer producers providing ETFE resins and specialty films—their resin supply strategies and licensing/partnership arrangements determine conversion economics and barrier-to-entry.
-
System integrators and tensile-structure specialists who combine film supply with engineering and installation services—these players shape specification choices and can capture downstream margin.
Specific names we track closely (report contains full vendor scorecards): NOWOFOL Kunststoffprodukte (long-standing film producer based in Germany), Dyneon GmbH/3M (resin and film technologies), Chemours (Tefzel ETFE resins), AGC (Fluon brand developments), Daikin (Neoflon and recent UV-resistant grades), Textiles Coated International (melt-extrusion manufacturing), and system houses such as Birdair, Novum Structures, and Enclos Tensile Structures. For procurement and alliance teams, the report outlines each firm’s strategic posture, capacity signals, product differentiation and potential partnership levers.
Recent industry dynamics to factor into 2026 plans
-
Product innovation: UV-resistant film variants introduced by leading manufacturers are changing life-cycle economics and warranty expectations. Such improvements influence specification decisions for sun-exposed roofs and façades.
-
Standards and certification: New technical standards for tensile membranes and welded ETFE connections have become active, shifting design practice and acceptance testing—critical for risk-averse owners and insurers.
-
Project precedent: High-visibility installations continue to validate ETFE’s value proposition for lightweight, translucent architecture; project wins by experienced integrators provide early revenue visibility for film producers.
Key strategic themes and recommended actions for 2026
-
De-risk upstream supply: Short-term (0–12 months) — execute multi-sourced resin agreements and prioritize suppliers with verified traceability and capacity commitments. Medium-term — consider strategic inventory cushions or toll-manufacturing partnerships to lock conversion capacity.
-
Differentiate through performance: Leverage UV-stable and multi-layer architectures for premium projects. In 2026, R&D roadmaps should focus on durability and aesthetic longevity to command higher margins.
-
Pre-qualify integrators: Owners and developers should run parallel technical and commercial pre-qualification processes to speed procurement cycles; PW Consulting’s scorecards can be adapted into RFP templates.
-
Capitalize on standards momentum: Use compliance to accelerate specification adoption in regulated markets; firms that certify products and train installers gain first-mover advantage where standards tighten procurement requirements.
-
Selective consolidation: Investors and strategic acquirers can prioritize targets that provide a clear path to capture downstream installation value or improve margin through scale in specialized film production.
-
Sustainability positioning: Develop recycled-content or closed-loop messaging where feasible—owners increasingly include lifecycle carbon and recyclability in selection criteria.
Methodological rigor and modelling approach
The full report uses a blended methodology: bottom-up validation of active project pipelines, top-down macro drivers (construction activity, architectural trends, greenhouse and stadium demand vectors), supplier capacity models and price trajectory simulation driven by resin cost scenarios. The base year is 2025 and the forecast period is 2026–2032, with revenue expressed in USD (Million). Our scenario framework tests outcomes under varying project conversion rates, product mix shifts, and regulatory adoption speeds—an essential tool for board-level stress-testing of investment cases in 2026.
How to operationalize the intelligence in 2026
-
Board briefing: Use the executive summary and pipeline convertibility matrix to distill timing and capital needs.
-
Procurement playbook: Deploy the supplier scorecards and RFP templates to reduce qualification time and lock terms before competing buyers increase demand.
-
R&D and product strategy: Align product development priorities to durability and ease-of-installation improvements that create premium positioning in tender processes.
-
M&A screening: Apply our valuation sensitivities and integration KPIs to prioritize bolt-on targets that accelerate access to projects and installation know-how.
Next steps — where to get the full intelligence
This briefing outlines the strategic contours and executive-level implications of the ETFE membrane opportunity for 2026. The full PW Consulting ETFE Membrane Market report contains the detailed segment models, regional and application splits, supplier share tables, and downloadable RFP and due-diligence templates that practitioners need to run procurement, invest, or restructure. To transition from strategic intent to operational action, schedule a tailored briefing with our team—PW Consulting will walk you through model interrogations, bespoke scenario runs, and an accelerated supplier selection process aligned to your 2026 milestones.
Contact PW Consulting to access the complete dataset, vendor scorecards and actionable templates that are intentionally summarized here to preserve the value of the full research package.
For detailed analysis of this topic, please visit the official page: ETFE Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vapor Chamber Market to Reach USD 5,790 Million by 2032 at 10.5% CAGR
By pmarketresearch, 2026-07-13
Vapor Chamber Market: Strategic Briefing for 2026 — Why This Study Will Shape Your Next Move
Executive snapshot
By 2025 the global vapor chamber market reached roughly USD 2,990 Million (base year: 2025). Our model projects a sustained compound annual growth rate (CAGR) of approximately 10.5% through the forecast window, positioning the market north of USD 5.7 Billion by 2032. For corporate leaders making capital allocation, product and supply-chain choices in 2026, this study is designed to translate that headline expansion into actionable priorities — without burying you in raw tables. Consider this article a trailer: it demonstrates the depth and practical orientation of the full PW Consulting analysis while preserving critical, high-value segmentation and unit-level intelligence for the full report access.
Vapor Chamber Market
Why 2026 is a strategic inflection point
- Demand geometry: Multiple end-markets (consumer electronics, data centers, automotive, aerospace, healthcare and industrial) are converging on higher thermal-performance requirements. This is no longer a niche heat-spreading technology: vapor chambers are moving from optional performance uplift to required enablers in designs constrained by power density and form factor.
- Supply-side transformation: Capacity investments and new product families introduced in late 2025–mid 2026 are materially reshaping manufacturing economics. Some suppliers have already announced multi-fold capacity expansions targeted at AI/ASIC and server cooling segments, tilting supplier bargaining power and time-to-market dynamics.
- Input-cost volatility and policy risk: The commodity cycle and trade policy interventions in 2025–2026 have amplified input-cost and sourcing risk for copper-heavy assemblies, requiring procurement playbooks that marry hedging, alternate material strategies, and nearshoring considerations.
What the PW Consulting study delivers (practical, transaction-ready intelligence)
This research goes beyond market-sizing and trend narration. It is a practitioner’s dossier for executives and deal teams preparing to compete or invest in vapor chamber value chains in 2026:
Vapor Chamber Market
- Investment-grade TAM and demand scenarios: base, upside and stress cases that reconcile end-market unit trajectories with thermal design adoption curves.
- Driver-based cost model: factory-level cost build-ups, sensitivity to copper and PCM inputs, labor and automation levers — stated as templates you can apply to your own BOMs (modeling worksheets included in the full deliverable).
- Supplier scorecards and capacity maps: production footprints, lead-time risk hot spots, and a dynamic supplier risk index calibrated for 2026 supply shocks.
- Product and IP segmentation playbook: how to prioritize standard, ultra-thin and embedded vapor chamber portfolios against OEM qualification cycles and regulatory constraints.
- Regulatory and qualification navigator: checklists and timelines for AEC-Q100, IATF 16949, ISO 13485 and other customer/OEM certification gates that commonly extend project timelines by 12–36 months.
- M&A and partnership playbook: valuation heuristics, bolt-on targets, JV structures and earn-out frameworks for consolidators and strategic buyers.
- Go-to-market tactical templates: OEM engagement sequences, design-win timelines, and pricing strategies for high-power vs. form-factor-sensitive segments.
Market dynamics that matter in 2026
The market’s macro trajectory is robust: with a mid-teens-ish expansion in absolute dollars expected over the forecast period, firms that move early to secure design wins and scale will capture asymmetric value. Key dynamics we explore in the report include:
Vapor Chamber Market
- Thermal performance ceilings: advances in vapor chamber geometry, wicking and ultra-thin manufacturing mean thermal solutions are being specified for power densities previously reserved for active liquid cooling. This drives differentiated product tiers and margin dispersion.
- Qualification and time-to-revenue friction: OEM qualification standards in automotive and medical markets (AEC-Q100, IATF 16949, ISO 13485) impose long lead-times and high test burdens; our analysis quantifies the typical investment and calendar impact per market.
- Commodity and trade-policy shock scenarios: 2025–2026 saw record copper price pressure and tariff actions that materially increased producers’ cost-of-goods and reshuffled cost-competitive geographies. The full report models several mitigations — from alloy substitution and plating strategies to procurement hedging and supplier diversification.
- Concentration and competitive structure: the vapor chamber market displays a low-to-moderate concentration structure; major incumbents collectively control a minority share, leaving room for niche specialists and high-volume OEM suppliers to expand through both organic and inorganic routes.
Competitive landscape — what you need to know now
Our competitive analysis synthesizes corporate positioning, product breadth, capability gaps and near-term strategic moves across the vendor ecosystem. Highlights include:
- Strategic capacity builders: Several Taiwanese and regional manufacturers have accelerated capacity additions aimed at AI-server, GPU and high-power compute segments. These moves materially change lead-time and scale economics for large OEM contracts.
- Product breadth and specialization: Market players differentiate on thickness (standard vs. ultra-thin), embedded designs, and integrated thermal-module solutions for specific end-markets (e.g., AI servers, foldable consumer devices, automotive power modules). Companies that bundle vapor chambers with thermal modules and system-level engineering services extract higher margin capture and longer-term customer stickiness.
- North-south technology transfer and cost arbitrage: Chinese manufacturers are increasingly competitive on 3D and thin-form vapor chambers, while US and Taiwanese firms emphasize integrated engineering services, IP protection and quality systems favored by tier-1 OEMs.
- Notable corporate developments: Recent public disclosures in early-to-mid 2026 show capacity buildouts, new high-spec product introductions and design guidance updates that together accelerate adoption for high-power applications. These are tracked in a dedicated timeline within the full report.
Regulatory, procurement and raw-material risk — practical implications
Regulatory compliance is not just a certification checkbox: it materially affects time-to-revenue and cost. Automotive- and medical-grade vapor chambers require rigorous qualification and test matrices, which our fieldwork shows commonly extend project schedules and necessitate capitalized testing budgets.
On the procurement side, record-level copper dynamics and tariff moves in mid-2025–2026 elevated raw-material cost exposure. Effective procurement strategies we model include dual-sourcing, long-term offtakes with indexation clauses, and selective pass-through pricing in OEM contracts. The report includes scenario outputs showing the P&L sensitivity of these strategies under different commodity and tariff shocks.
High-conviction plays for 2026
- Secure early design wins in high-growth, high-ASP segments (AI, data-center accelerators) where cycle-times compress margins less than consumer product channels.
- Invest in thin/embedded process IP or partner with a specialist — thin-form factor wins are conversion barriers that justify price premiums in handheld and mobile applications.
- Rebalance the supply chain: diversify sourcing of critical copper inputs and qualify geographically distinct contract manufacturers to mitigate tariff and logistics risk.
- Structure OEM contracts to share upstream commodity exposure and align incentives for scale: include step-up pricing bands and volume rebates tied to validated design wins.
- Prepare regulatory roadmaps early for automotive and medical programs to avoid late-stage rework that erodes margin and time-to-market.
Why PW Consulting’s vapor chamber study is different
We combine primary vendor interviews, factory tours, BOM-level cost models and OEM qualification-path mappings to produce an actionable blueprint. Instead of generic slices of demand by region and application, we translate market momentum into decision-support tools: scenario P&Ls, supplier risk indices, investment timelines and M&A targets prioritized by strategic fit and time-to-value.
How to use this briefing in 2026 strategic planning
- Board-level budgeting: use our downside and upside scenarios to stress capital plans and to set guardrails for capacity additions.
- Corporate development teams: prioritize M&A targets using our valuation premia that reflect IP ownership, design-win stickiness, and supplier footprint.
- Product and engineering leaders: adopt the report’s technology roadmap to align product launches with the OEM qualification cadence.
- Procurement and operations: implement the tactical sourcing and hedging templates to reduce COGS volatility and ensure continuity of supply during peak ramp periods.
Next steps — where to get the full playbook
This article intentionally omits proprietary segmentation matrices and unit-level forecasts that form the highest-value outputs in our research — these are available in the full PW Consulting Vapor Chamber Market report. The full deliverable contains detailed regional and application splits, supplier-by-supplier competitive scorecards, factory economics, and downloadable financial models designed for integration with your own planning systems.
For leadership teams prioritizing decisive action in 2026, this report is both a radar and a road-map: it identifies where the next design-wins and scale economies will appear, and it prescribes the commercial, operational and financial playbooks to capture them.
For detailed analysis of this topic, please visit the official page: Vapor Chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com