

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Banknote-Printing Machine Market to reach USD 333.3 Million by 2032 at 10.4% CAGR

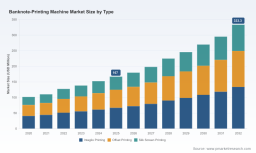
Banknote-Printing Machine Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused introduction to our latest Banknote-Printing Machine Market study. This briefing synthesizes the structural trajectory, competitive dynamics, and tactical implications that should inform procurement, capital planning, and partnership strategies in 2026. It intentionally showcases the analytical depth and decision-grade frameworks contained in the full report while withholding detailed sub-segment tables and proprietary breakouts—designed to invite direct engagement with the full study for operational execution.
Banknote-Printing Machine Market
Why this market matters in 2026
The banknote-printing machine market has moved from a niche, capacity-focused sector into a strategic industrial sub-market at the intersection of sovereign finance, security technology, and advanced manufacturing. On the macro scale, the market expanded from roughly USD 101.8 Million in 2020 to about USD 167.0 Million in our base year (2025), and our projections indicate continued momentum through the forecast window (2026–2032), culminating near USD 333.3 Million by 2032 at a compound annual growth rate of 10.4%. That rate embeds both recurring replacement cycles for central banks and accelerations tied to technology refresh, polymer adoption, and higher-security feature demand.
Banknote-Printing Machine Market
Core demand drivers and structural dynamics
- Sovereign lifecycle and capacity planning: Central banks and large security printers operate on long lead times and multi-year modernization plans. Public modernization programs and multi-year print orders materially shape near-term OEM order books and service revenues.
- Security innovation vs. cost pressure: The paradox of this market is that rising security requirements (new features, hybrid substrates, enhanced inspection systems) increase per-unit complexity and cost, yet budget pressures on currency issuers push for more efficient lines and lower total cost of ownership.
- Technology convergence: Integrations across intaglio, offset, screen, and web-fed hybrid lines—combined with inline inspection, digital controls, and automated convertors—are shifting value from single-process machines to platform-based production lines that support shorter changeover times and higher uptime.
- Regulatory and strategic tailwinds: Recent procurement decisions and strategic modernization initiatives by major sovereign printers have created a pull for new equipment and aftermarket services. Industry conferences and awards continue to codify innovations that accelerate adoption, while procurement cycles at major issuers create discrete opportunities for suppliers.
- Concentration and supplier economics: The market exhibits meaningful concentration—our study measures a top-three concentration near the mid-50 percent range and a top-five near the low-70 percent range—implying an oligopolistic supplier structure with differentiated scale and aftermarket advantages.
Technology and product evolution
From equipment design to plant engineering and inline quality assurance, the evolution in this sector is practical rather than speculative: tighter tolerances, enhanced process automation, and modular architectures that let operators combine security printing processes in flexible lines. These shifts favor manufacturers that can offer integrated solutions—machines plus plant-level engineering and digital services—over isolated press sellers. Expect procurement criteria to increasingly reward lifecycle services (predictive maintenance, retrofitability, spare-part pools) as well as cybersecurity and compliance features embedded in control systems.
Banknote-Printing Machine Market
Competitive landscape: players to watch
The competitive map is shaped by a handful of legacy players and specialized OEMs that combine press engineering with high-security expertise. Our full report contains comparative vendor scorecards; below is a synthesized qualitative view of principal competitors and recent market signals that are critical for 2026 planning.
- Koenig & Bauer Banknote Solutions (Lausanne, Switzerland)
Koenig & Bauer is positioned as a high-security specialist, offering integrated screen and offset systems and end-to-end production lines. Its strengths are engineering depth for banknote-specific requirements and a track record of trade-fair innovation signaling. For buyers, Koenig & Bauer is often a go-to when complete line integration and legacy compatibility matter. - Komori Corporation (Tokyo, Japan)
Komori’s CURRENCY Series and combination multiprocess machines have global reach and an installed base across many markets. Komori’s credentials include supplying mission-critical systems for national currency projects and recent high-profile orders for major sovereign printers. Its scale and technology leadership make it a preferred partner where long-term support and large-system delivery reliability are prioritized. - Giesecke+Devrient (Munich, Germany)
G+D combines machine supply with high-tech plant engineering and consulting services, which is valuable where process design and quality inspection are decisive. G+D’s offerings lean into end-to-end delivery—equipment, software, and operational know-how—making it adept at complex modernization projects. - De La Rue (Basingstoke, United Kingdom)
De La Rue, with its long-established security-printing capabilities and equipment lineage, remains a full-solution provider including substrate expertise. Their capabilities are often tapped where integrated supply—from design to execution—is required, including polymer transitions and production technique dissemination in regional markets. - Goebel Capital GmbH, SPS TechnoScreen, Pasaban
These specialized OEMs (hybrid web-fed systems, cylinder screen presses, paper converting and sheeting equipment) play crucial roles in niche elements of the production chain. Their value is in modularity, specialized process performance, and the ability to supply retrofits and ancillary plant equipment that increase line throughput or support substrate transitions.
Recent market signals — reading the tea leaves
- Mid-2020s procurement and modernization plans among major sovereign printers have continued to drive equipment demand and aftermarket services. Prime examples include large-system orders awarded in 2025 and strategic equipment roadmaps published by national printers that prioritize efficiency improvements.
- Trade shows and industry awards during 2025–2026 have highlighted both incremental and step-change innovations in substrates, security features, and production ergonomics—indicating that buyers are actively benchmarking new technologies.
- Plant-level modernization programs emphasize that opportunity lies as much in engineering services, retrofit capability, and quality inspection systems as in the sale of new presses. This widens the addressable services market for suppliers with systems-integration capabilities.
Implications for 2026 corporate decisions
For corporate leaders—OEMs, security printers, central banks, and investors—the next 12–18 months are pivotal. Below are high-level strategic takeaways to guide 2026 decisions; the full report converts each into actionable roadmaps and templates.
- Procurement strategy must be lifecycle-aware: Evaluate suppliers on total cost of ownership, retrofitability, and aftermarket coverage, not only on capex price. Insist on demonstrable field data for uptime, mean time to repair, and spare-part logistics.
- Partnerships trump point-solutions: Seek vendors capable of delivering combined equipment-and-engineering solutions. Where capacity constraints or specialized substrates are in play, a converged supplier can reduce project risk and shorten time-to-production.
- Mitigate concentration risk: The market’s top-firm concentration creates supplier dependency risks. Structuring procurement to include second-source options, licensable technology, or performance-based contracts can lower supply-chain vulnerability.
- Capitalize on retrofit and services growth: For OEMs and service providers, investing in predictive maintenance, digital spare-part catalogs, and modular retrofit kits is the most direct path to recurring, higher-margin revenue.
- Policy and program timing matters: Align sales and investment pipelines with sovereign procurement cycles and modernization programs—these create discrete peaks in demand and influence capacity planning.
What our report delivers (practical content)
The full PW Consulting study is highly operational and built for decision-making. Key deliverables include:
- Market sizing and 2026–2032 forecast models with scenario sensitivity and unit economics calibrated to different modernization pathways;
- Vendor due-diligence templates and comparative scorecards covering technology, service footprint, financial strength, and incumbent risk;
- CapEx budgeting tools and procurement negotiation playbooks, including RFP checklists and contractual clauses to safeguard uptime and IP;
- M&A and partnership blueprints—target screen criteria, valuation levers for bolt-on services, and integration planning checklists;
- Operational readiness matrices for central banks and large printers—plant-engineering best practices, retrofit sequencing, and quality-inspection baseline expectations;
- Risk registers for supply-chain, regulatory, and cybersecurity exposures with mitigations and contingency cost models.
Closing: how to use this briefing in 2026
Use this briefing to orient your 2026 strategic priorities: align procurement calendars to sovereign modernization timelines, re-weight supplier assessments toward lifecycle services, and prepare for selective investments in retrofit and digital service capabilities. The landscape favors integrated suppliers and service-led business models, yet concentration in supplier share creates both opportunity and risk for buyers and investors.
PW Consulting’s full Banknote-Printing Machine Market report converts these insights into the analytic assets decision-makers need—forecast models, vendor scorecards, procurement playbooks, and executable roadmaps. For teams preparing CapEx proposals, vendor negotiations, or M&A screens in 2026, the study is structured as an operational toolkit rather than a purely descriptive market review.
To access the complete analysis, detailed supplier benchmarking, and the ready-to-use templates that underpin these recommendations, visit the PW Consulting research portal and request the Banknote-Printing Machine Market report package.
For detailed analysis of this topic, please visit the official page: Banknote-Printing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com