

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hot Dogs & Sausages Market to Grow at a 3.01% CAGR (2026–2032)

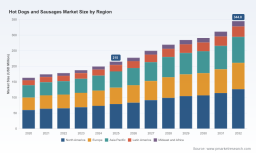
Hot Dogs and Sausages Market — Strategic Outlook for 2026 Corporate Decision‑Makers
PW Consulting’s Hot Dogs and Sausages Market introduction synthesizes proprietary modeling, public-sourced industry signals, and forward-looking scenario work to equip executives with the selective insights they need to act in 2026. The global market, measured on a 2025 base year, sits in the low hundreds of millions (USD, revenue unit: Million) and — under our baseline assumptions — grows at a compound annual growth rate (CAGR) of approximately 3.01% through the forecast horizon. By the end of the forecast window the model points to a material expansion in nominal market value, driven by a blend of volume resilience and premiumization.
Hot Dogs and Sausages Market
Why this study matters for decisions made in 2026
-
Timing matters: 2026 is the inflection point for several supply‑side capacity investments and integration plays that were initiated in 2024–2025. Companies that finalize sourcing, pricing and distribution choices now will be positioned to capture or defend share as new capacity and product flows come online later in the decade.
Hot Dogs and Sausages Market -
Commodity and feed volatility will shape margins. USDA projections for the 2026/27 U.S. corn crop indicate a reduction in output relative to the prior year and a projected season‑average price around USD 4.40/bushel. That dynamic tightens feed cost pass‑through opportunities and requires active hedging and procurement strategies from protein processors.
Hot Dogs and Sausages Market -
Protein supply trends matter. USDA projections to 2034 point to an overall increase in pork production during the projection period — a structural tailwind for sausage demand — but the benefit will be asymmetric across geographies and product tiers.
-
Standards and compliance create both constraints and defense mechanisms. Hot dogs are regulated under frankfurter standards of identity that specify allowable formulations and limits on mechanically separated meat; compliance is non‑negotiable and a regulatorily enforced source of brand differentiation.
-
Concentration and market dynamics. The category is meaningfully concentrated at the top: our market concentration metrics show that the top three and top five players control a majority share, creating advantages for scale but leaving tactical spaces for specialty and private‑label strategies.
-
Reputational exposure is a strategic risk. Recent recall activity in 2025 underscores how product integrity events can shift channel mix and accelerate retailer risk‑mitigation efforts, creating openings for trusted smaller brands and certified premium suppliers.
What the report contains — practical, transaction‑ready deliverables
-
Executive synthesis and investment thesis: a two‑page, board‑ready brief that maps risk/reward across the most likely 2026 strategic moves.
-
Market model and scenario engine: a dynamic forecast (2026–2032) built from bottom‑up SKU economics, trade flows and channel adoption assumptions, with three alternate macro scenarios (base, high growth, downside stress) ready for sensitivity analysis.
-
Supply‑side capacity map: plant‑level capacity, near‑term commissioning timelines and utilization scenarios (including a focused view on newly announced large builds and acquisitions).
-
Raw material risk matrix: corn and feed sensitivity, pork supply outlook, and an actionable set of procurement hedging strategies tied to likely margin outcomes.
-
Go‑to‑market and channel playbooks: retailer negotiation frameworks, prioritized tactics for foodservice and e‑commerce acceleration, and private‑label vs. branded ROI comparisons.
-
Quality and recall readiness frameworks: traceability, supplier audit protocols, and crisis communication templates informed by recent industry recalls.
-
M&A and partnership shortlists: a curated list of strategic acquisition targets and co‑packing partners prioritized by capability gaps, geographic fit and integration risk.
-
Primary research appendices and model workbook: anonymized retailer and operator interviews, consumer preference matrices, and the forecast spreadsheets used to run bespoke client scenarios.
Competitive landscape — key implications from recent corporate moves
The competitive map is actively being redrawn by capacity investments, consolidation and product differentiation. Select observations that should factor into 2026 strategy:
-
Major capacity additions will change bargaining dynamics. Recent public filings and announcements indicate that significant new processing capacity will be commissioned in the near term. One large entrant is advancing a greenfield sausage facility with multi‑annual throughput expectations; such additions tend to compress spot prices in the commissioning year before re‑balancing to differentiated product premiums.
-
M&A and plant acquisitions remain a fast route to scale. Strategic acquisitions of well‑located plants have been used to accelerate distribution reach and SKU breadth — a tactic that continues to be attractive for companies seeking rapid channel penetration without the lead time of new builds.
-
Premium and specialty players are expanding pockets of defensible margin. Brands that emphasize provenance, seasoning innovation and premium protein mixes are commanding favorable retail placement and higher velocity in select foodservice concepts.
-
Quality incidents are strategic inflection points. Large recalls disrupt category perceptions and accelerate retailer shelf rationalization. Organizations that can credibly demonstrate superior traceability and quality systems will see shortened payback on premium positioning post‑incident.
Strategic playbook — actionable options for 2026
-
Lock and layer input procurement: implement a layered hedging approach for feed commodities to smooth cost volatility through peak commissioning cycles.
-
Prioritize capacity flexibility: if building or expanding, design plants for multi‑protein capability (pork, beef, poultry) to capture shifting preference mixes and to mitigate single‑supply shocks.
-
Invest in traceability and quality automation: the marginal cost of enhanced QA is small relative to the cost of lost shelf access after a recall. Digital traceability is also a premium consumer proposition.
-
Segment your route‑to‑market: tailor products and pricing to the economics of retail, foodservice and e‑commerce rather than a one‑size approach; online channels require different pack formats and fulfillment logic.
-
Use M&A to buy speed to market: prioritize bolt‑on assets that solve distribution or margin shortages rather than trophy brands with high integration complexity.
-
Build a defensive private‑label strategy: use co‑packing partnerships to serve large retailers while protecting branded innovation at premium price points.
-
Prepare for regulatory scrutiny: understand identity standards and mechanically‑separated meat limits embedded in frankfurter regulations; design formulations and labeling practice to avoid enforcement setbacks.
2026 decision checklist for boards and operating executives
- Confirm whether your 2026 capital allocation prioritizes capacity, quality systems or brand innovation — run revised NPV under the base and downside commodity scenarios included in the full model.
- Stress‑test procurement contracts for corn and protein inputs against the USDA baseline and downside outcomes; set clear pass‑through rules for customers.
- Audit your recall readiness and supplier traceability; model the shelf‑access risk of a 30‑ to 90‑day disruption.
- Map your SKU portfolio to channel economics; identify three SKUs to expand in e‑commerce and three to rationalize in brick‑and‑mortar.
- Scan for opportunistic M&A targets that close your distribution or capability gaps within a 12–18 month integration horizon.
How to use this introduction — next steps
This introduction is designed as a concise strategic briefing: it surfaces the most consequential forces and the high‑leverage responses for 2026. The full PW Consulting Hot Dogs and Sausages Market report contains the detailed tables, plant‑level capacity maps, company scorecards, and the complete forecast workbook that decision‑makers will need to finalize capital plans, procurement contracts and commercial strategies. In keeping with the “trailer” principle, we have highlighted the directional findings and proprietary implications here while reserving the full subsegment and regional revenue matrices for the full report and the downloadable model.
If your priority is tactical readiness in 2026 — whether that is executing an acquisition, expanding capacity, or defending a retail roster — the full report provides the actionable analytics, vendor shortlists and scenario templates necessary to move from insight to decision within weeks, not months.
PW Consulting: we translate category complexity into a clear set of strategic choices and executable playbooks so you can capture value as the market reshapes over the next investment cycle.
For detailed analysis of this topic, please visit the official page: Hot Dogs and Sausages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com