

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Perfluoropolyethers Market Set to Grow at 5.85% CAGR to 2032
By pmarketresearch, 2026-07-13
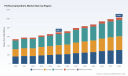
Perfluoropolyethers Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As companies set budgets and capital allocations for 2026, the perfluoropolyethers (PFPE) market is at an inflection point that demands high-fidelity strategic judgement. This briefing summarizes the strategic value of our full PW Consulting market study and outlines the decision levers senior leaders should consider before committing to investment, sourcing, or M&A moves. We present data-driven context — including market scale and growth trajectory — while preserving the detailed segment analytics and proprietary tables that drive deal-level decisions for subscribing clients.
Perfluoropolyethers Market
Market at a glance: what the macro picture tells you
PFPEs are a specialized class of performance fluids and greases used when extreme chemical and thermal stability, dielectric properties, and long life are required. At the macro level, the market reached approximately USD 699 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 forecast horizon, approaching roughly USD 1.03 billion by 2032. That steady expansion masks important structural characteristics — a mix of high-performance demand from capital goods industries and a supply side that is concentrated and technically gated — which should shape any near‑term strategic plan.
Perfluoropolyethers Market
Why this research matters for 2026 decision cycles
- Regulatory inflection points: PFPEs have been the focus of intensified regulatory analysis and market surveillance across jurisdictions. Key recent developments include inclusion on U.S. EPA SNAP program lists and new EU measures on substance surveillance that change compliance costs and market access dynamics.
- Concentrated supplier power: Top-tier manufacturers account for the majority of available commercial product, creating bargaining asymmetries and higher thresholds for new entrants. Our analysis shows industry concentration levels that materially affect pricing elasticity and contract design.
- Data scarcity and confidentiality: Official production volumes are often reported as confidential business data, complicating traditional supply/demand estimation. Our methodology reconciles primary interviews, proprietary shipment proxies, and policy signals to produce defensible forecasts.
- Environmental monitoring and reputational risk: Recent provenance and environmental monitoring activities tied to established producers have elevated due‑diligence requirements for downstream buyers, especially in regulated end-markets.
What the PW Consulting study delivers — practical, decision-ready content
- Robust market sizing and forecasting model (base year 2025; historical run 2020–2025; forward view 2026–2032) with scenario toggles for regulatory tightening and raw material volatility.
- Segmentation frameworks across type, end-use and geography — including demand drivers, substitution risk, and technology readiness — presented as decision matrices rather than raw tables (full split detail available in the full report).
- Supplier and capacity mapping that highlights choke‑points, proprietary chemistries, and third-party tolling risk.
- Regulatory impact matrix that quantifies compliance cost scenarios and market access timelines tied to recent public policy moves.
- Competitive benchmarking and playbooks: company profiles, product positioning, channel strategies, and after-sales/service differentiation to inform sourcing and JV/M&A strategies.
- Practical tools: investment threshold calculators, supplier scorecards, contracting templates with performance and compliance clauses, and an executive dashboard for board-level briefings.
Key market dynamics to factor into 2026 strategy
- End‑market sensitivity and asymmetric demand growth — PFPE demand is decoupled from general industrial expansion. Gains are concentrated in applications needing long-life lubrication, extreme temperature stability, or unique dielectric performance. These pockets will drive premiumization even as overall growth remains mid-single digits.
- Regulatory and market surveillance are accelerating — the U.S. EPA’s SNAPS program has explicitly listed PFPEs for certain acceptable substitutes with conditions, and the EU’s Regulation 2024/590 raises the bar for market surveillance and customs controls, changing time-to-market assumptions for product introductions.
- Supply opacity increases strategic risk — the OECD notes confidentiality in production reporting, and that opacity intensifies the value of proprietary supplier intelligence and multi‑sourcing strategies. Firms without direct intelligence runs the risk of being surprised by capacity constraints or product delisting.
- Reputational and environmental monitoring — recent certified reference material initiatives and environmental studies tied to established producers mean buyers must incorporate provenance and lifecycle reporting into supplier selection to avoid regulatory and reputational hits.
- Consolidation and vertical play — high technical entry barriers favor incumbents and create opportunities for forward integration by downstream players seeking to secure specialized supply or differentiate through service and formulation.
Competitive landscape — how the key players are positioning
The competitive field is dominated by established specialty-chemicals and lubrication players that combine proprietary chemistries, patented formulations and global service networks. Market concentration is meaningful: the top three suppliers hold a commanding portion of available commercial product, and the top five further consolidate access and pricing power. This structure favors strategic incumbency, scale-enabled R&D, and service differentiation.
Perfluoropolyethers Market
- Daikin Industries Ltd. (Osaka, Japan): Known for Demnum PFPE fluids and lubricants, Daikin leverages integrated manufacturing and long-term OEM relationships. Their competitive edge is product consistency and breadth of industrial channel access.
- The Chemours Company (Wilmington, DE, USA): Krytox is positioned as a premium PFPE lubricant brand targeting high-specification applications. Chemours emphasizes performance benchmarking and aftermarket availability for critical assets.
- DuPont de Nemours, Inc. (Wilmington, DE, USA): With MOLYKOTE PFPE-based lubricants, DuPont combines formulation expertise with global distribution channels particularly strong in electronics and industrial maintenance markets.
- Solvay S.A. (Brussels, Belgium): As a producer of Fomblin PFPE fluids, Solvay operates at the intersection of specialty polymer production and regulatory visibility. Recent regulatory compliance and environmental monitoring activities have placed broader scrutiny on regional production footprints.
- Klüber Lubrication (Munich, Germany): Offers branded PFPE oils and greases with a heavy emphasis on engineered solutions and service agreements, appealing to OEMs seeking lifecycle support over commodity supply.
- Nye Lubricants Inc. (Fairhaven, MA, USA): A niche specialist with Uniflor PFPE products, Nye competes on tailored formulations and rapid technical support for precision industries.
- Fuzhou Topda New Material Co., Ltd. (Fuzhou, China) and Anhui Sinograce Chemical Co., Ltd. (Anhui, China): Regional suppliers that provide cost-competitive PFPE products and PFPE-derived solutions for coatings; they are increasingly relevant for buyers seeking cost‑effective alternatives and local sourcing.
Recent developments that change the playbook
- Regulatory & compliance: In 2024, parts of the PFPE chain were incorporated into enhanced surveillance programs, including actions that affect market surveillance and customs controls — a factor that lengthens qualification timelines.
- Monitoring & reference materials: Solvay‑linked initiatives for certified reference materials and local environmental studies have created new transparency vectors but also added potential liabilities for manufacturers and users.
- Industry reporting gaps: Multilateral assessments emphasize that production data is often kept confidential, making primary‑research intelligence and supplier access indispensable for credible commercial planning.
Strategic playbook for 2026 decision-makers
- Adopt a regulation-first product and sourcing strategy. Build regulatory scenarios into NPV and payback models (fast/slow/no-action scenarios) and require suppliers to demonstrate compliance roadmaps as a condition of award.
- Prioritize supplier resilience over lowest-first-cost. Given concentration and opaque production reporting, dual‑sourcing or contractual capacity reservations may be superior to spot procurement savings.
- Invest in formulation & co‑development where feasible. OEMs and specialty users should evaluate partnerships or minority equity to lock technology access and accelerate qualified supply for critical programs.
- Use the CAGR window tactically. With a mid‑single digit expansion path, target investments with clear three- to five-year payback windows and prioritize initiatives that secure margin improvement rather than chasing share in lower-margin pockets.
- Elevate lifecycle compliance and traceability as commercial differentiators. Companies that can offer documented provenance, lifecycle assessment, and regulatory support will command premium positioning in regulated end markets.
- Prepare M&A and bolt-on playbooks focused on capacity, IP, and aftermarket services. Target assets that reduce reliance on single-source proprietary chemistries or expand serviceable aftermarket footprints.
Practical next steps & risk checklist
- Immediate: Run a supplier risk audit that maps single points of failure in PFPE supply and includes compliance certifications and substitute readiness.
- Short-term: Conduct a scenario valuation of key programs using PW Consulting’s forecast model (available with subscription) to identify which product lines merit accelerated capex.
- Medium-term: Negotiate structured supply agreements with performance and compliance KPIs; include price‑indexation and transition plans for regulatory shifts.
- Risk checklist: regulatory non-compliance, supplier concentration, raw-material price shocks, environmental monitoring liabilities, and technology obsolescence.
Conclusion — The PW Consulting PFPE study is designed to be a tactical instrument for 2026 planning cycles. It converts opaque market signals into operational triggers: when to hedge, when to invest, and when to consolidate. For executives looking to convert market growth into durable economic advantage, our full report supplies the withheld segment tables, regional splits, interactive forecast model, and supplier scorecards necessary to move from intent to action.
To access the detailed segmentation, proprietary scenario models, and supplier matrices referenced here, please visit PW Consulting’s Perfluoropolyethers Market report page or contact your client representative for the subscriber pack and workbook.
For detailed analysis of this topic, please visit the official page: Perfluoropolyethers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber Optic Cables Market to Hit USD 19.33B by 2032 at 9.94% CAGR
By pmarketresearch, 2026-07-13
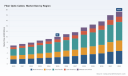
Fiber Optic Cables Market 2026: Strategic Imperatives for Executive Decision-Making
As global connectivity demands accelerate, the fiber optic cables market is re-entering a phase of structural expansion and strategic complexity. PW Consulting’s latest industry study—anchored on a 2025 base year and extending through 2032—shows that the market has expanded from roughly USD 6.8 billion in 2020 to about USD 10.0 billion in 2025 and is projected to approach USD 19.3 billion by 2032 under a compounded growth trajectory (CAGR ~9.94% across the forecast window). For corporate leaders planning capital allocation, supply-chain resilience, or M&A in 2026, these headline figures are not abstract; they define timing windows, margin pressure points, and the scale of operational response required.
Fiber Optic Cables Market
Why this research matters for 2026 corporate strategy
- Timing of capacity investments: The market’s near-term acceleration—evident in the step-up from 2020–2025 baseline to the forecasted growth path—means firms that front-load selective capacity (or secure long-lead inputs) can capture premium tender activity with superior margins. Conversely, late entrants risk higher procurement costs and longer lead times as raw-material scarcity periodically emerges.
- Procurement and raw-material risk: Tightness in preform availability and volatility in quartz and cable-grade input markets have already pressured prices and lead times in early 2026. Procurement teams need decision-ready hedging and supplier-diversification playbooks rather than ad-hoc spot buying.
- Regulatory and sustainability compliance: Carbon and border-adjustment mechanisms are real levers of cost and access. Firms that map carbon intensity into pricing and contract terms will avoid margin erosion and regulatory surprises.
- Product and go-to-market differentiation: Demand is bifurcating—hyperscale data centers and AI workloads are driving capacity and performance requirements, while broadband and 5G backhaul continue to push reach and robustness. Product roadmaps must be calibrated to both high-volume, cost-sensitive deployments and high-performance, higher-margin segments.
What PW Consulting’s report delivers—practical outputs for executives
Our full report is deliberately designed as an operational guide for 2026 decision cycles. High-value deliverables include:
Fiber Optic Cables Market
- Robust market-size model with annual historicals (2020–2025) and a seven-year forecast (2026–2032), including scenario variants that stress-test demand under alternative AI, 5G, and FTTH roll-out assumptions.
- Supply-chain heatmaps identifying single-source vulnerabilities, critical lead-time drivers, and node-level concentration risks—built to support sourcing and inventory strategy workshops.
- Raw-material and unit-cost modeling (including sensitivity to quartz and cable-component pricing and an installation-labor cost ladder) to enable commercial teams to build defensible price escalators into long-term contracts.
- Vendor scorecards and a proprietary supplier-risk index that combine capability, capacity, geographic diversification, ESG credentials, and delivery performance—designed for procurement RFP shortlisting and preferred-supplier governance.
- Commercial playbooks for pricing, terms, and performance guarantees tailored for hyperscale, telco, and enterprise channels—each with negotiation scripts and contractual clauses to mitigate late-delivery exposure.
- Investment decision tools for CapEx sizing, payback analysis, and threshold triggers for greenfield capacity or vertical integration (preform and optical-fiber manufacturing).
Note: This preview intentionally omits granular regional and application breakdowns and company-level score-card data. Those are available in the full PW Consulting package, which includes interactive models and downloadable templates for executive use.
Fiber Optic Cables Market
Competitive landscape: what incumbent moves tell us
The competitive set is composed of diversified incumbents and regional specialists. Several strategic patterns are evident from recent company moves and product innovations:
- R&D and product differentiation are central: Long-standing technology leaders continue to invest in low-loss fibers and specialized multi-core solutions to service hyperscale and sensing applications. Partnerships between manufacturers and academic institutions are being used to accelerate next-generation fiber formats and distributed sensing capabilities.
- Sustainability and certification as barriers to entry: Investments in cleaner processing and reduced solvent use are serving dual objectives—cost reduction and regulatory compliance—creating switching costs for buyers sensitive to carbon penalties and procurement rules.
- Focused product launches address niche installation pain points: Bend-insensitive multimode fibers, low-smoke zero-halogen (LSZH) constructions for transit hubs, and multi-core fibers with embedded sensing are examples of tactical product plays designed to win specific project categories.
- Scale and integration remain decisive: Firms with upstream control of preform and fiber production, or with broad cable-systems expertise (including submarine assemblies), have superior leverage in pricing and delivery for large-scale, cross-border projects.
Representative strategic profiles (high-level):
- Corning Incorporated —deep IP in low-loss fiber and a strong footprint in single- and multi-mode fibers for hyperscale and telecom customers; excels at technology diffusion into high-volume applications.
- Prysmian Group —horizontal systems capability, including submarine and long-haul backhaul, positioning it well where integrated cable-systems expertise is a procurement requirement.
- Nexans —leveraging high-count cable solutions and recent environmental-certification wins to bid competitively on projects where sustainability and system integration are weighted factors.
- YOFC —large-scale upstream integration with capabilities across preform, fiber, and cable production; recent partnerships on multi-core fiber and sensing indicate a pivot to higher-value differentiated products.
- AFL Telecommunications —specialist in connectivity and assembly solutions that accelerate deployment timelines for hyperscale and broadband projects.
- Hengtong Group & ZTT —broad manufacturing portfolios and turnkey solutions that make them natural partners for large regional FTTH and submarine contracts; recent product introductions also target transit and tall-building installations.
Notable recent developments that matter to buyers and strategists: YOFC’s 2025 collaboration on multi-core fiber with embedded distributed acoustic sensing; Nexans’ 2025 ISO 14001 certification at a submarine plant tied to reduced water consumption and solvent elimination; product introductions focused on bend-insensitive multimode and LSZH constructions in 2025–2026. These moves reflect the twin priorities of product differentiation and regulatory compliance.
Key dynamics shaping price and supply in 2026
- Raw-material pressure: Cable-grade inputs and high-purity quartz pricing have historically exhibited wide bands; procurement teams should plan for episodic spikes and consider multi-year supply agreements with volume and indexation clauses.
- Regulatory overlay: Mechanisms like carbon border adjustments are reshaping landed costs and supplier selection. Buyers must evaluate total landed carbon-adjusted cost, not just ex-factory price.
- Demand concentration: Project waves—driven by hyperscale cloud expansions, AI workloads, and national broadband programs—tend to create short windows of intense procurement. Having pre-qualified suppliers and contract templates is a competitive advantage.
Recommended 2026 action plan for executives (prioritized)
- Secure strategic supply partnerships: Negotiate anchor agreements with tier-1 and regional suppliers, embedding price-adjustment formulas tied to transparent cost indices and lead-time SLAs.
- Invest selectively in upstream capacity or JV structures: Where your business model supports it, consider strategic capacity stakes in preform or fiber production to reduce exposure to input scarcity and capture margin uplift.
- Accelerate sustainability investments: Map your carbon footprint across the value chain and prepare for border-adjustment impacts by investing in cleaner process technologies and verified offsets or carbon-efficient suppliers.
- Differentiate product portfolios: Prioritize development or licensing of fibers and cable systems tailored to hyperscale/dense-lumen deployments and embedded sensing—where margin pools are deeper.
- Refine commercial contracts: Build in pass-through mechanisms, performance-based payment schedules, and accelerated remedies for late-delivery to mitigate risk during peak demand windows.
- Use the report’s scenario tools in board decisions: Establish trigger points—lead-time, input-cost, and demand thresholds—that guide when to shift from conservative to aggressive capacity or procurement postures.
How to apply the full report in Board and Procurement forums
Use the report as a decision-support kit: import the interactive forecasts into capital-allocation models, run supplier-risk simulations in procurement war-rooms, and adopt the provided contract templates and negotiation playbooks in sourcing RFx processes. The PW Consulting package is tailored to move quickly from insight to action: each strategic recommendation is accompanied by an implementation checklist and an estimated lead-time-to-impact metric.
Next step
The analysis above highlights the strategic contours for 2026 but intentionally omits the granular region-, type-, and application-level splits and vendor scorecards that underpin project-level choices. PW Consulting’s full report contains those segmented tables, downloadable models, and executable playbooks. For firms preparing procurement cycles, board reviews, or M&A screens in 2026, accessing the complete set of models and supplier diagnostics is the logical next step.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Density SLC NAND Market to Hit USD 2.12B by 2032 at 5.3% CAGR
By pmarketresearch, 2026-07-13
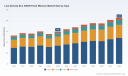
Low Density SLC NAND Flash Memory Market: Strategic Outlook for 2026 Decision-Making
Executive teaser
As hardware roadmaps converge toward resilient, long-life, and deterministic storage for mission-critical embedded systems, Low Density SLC NAND occupies a distinct strategic niche. PW Consulting’s new market study — anchored in a 2025 base year and extending through a 2026–2032 forecast window — synthesizes demand trajectories, supplier economics, regulatory risk and practical procurement playbooks to help executives make confident, time-sensitive decisions in 2026. The market is modest but steady: base-year revenue in 2025 stood at approximately USD 1.49 Billion, and our forecasts indicate a compound annual growth rate (CAGR) of roughly 5.3%, arriving at an anticipated market size near USD 2.12 Billion by 2032. This report is designed as a decision-support instrument: deep enough to guide strategy, selective enough to prompt direct engagement for the proprietary granular tables and pricing curves that matter in contract negotiations.
Low Density SLC NAND Flash Memory Market
Why this matters for 2026 strategic planning
-
Timing of portfolio investments: With mid-single-digit CAGR, low-density SLC remains a specialty segment rather than a volume-driven commodity. Firms deciding whether to invest in SLC-focused production lines, design-in resources, or long-term supply agreements must evaluate the trade-off between higher per-unit margins and constrained market scale.
Low Density SLC NAND Flash Memory Market -
Mission-critical differentiation: Applications that demand extremely high endurance, wide-temperature operation, or radiation tolerance (for aerospace, industrial control, and certain automotive code-storage functions) continue to prefer SLC. Companies that make 2026 product and qualification choices based on lifetime-cost models will find SLC strategically relevant despite its smaller absolute scale.
Low Density SLC NAND Flash Memory Market -
Procurement and contract timing: Volatility in wafer pricing and earlier 2025 price hikes require procurement teams to adopt shorter price-review cycles, stricter escalation clauses, and inventory buffering strategies. The report maps trigger points for renegotiation and provides model clauses for multi-year supply contracts.
Market trajectory — what the headline numbers conceal
The headline CAGR and end-point projection do not capture heterogeneity across use-cases, endurance classes, or temperature-rated variants. Our analysis layers product-class dynamics (e.g., small-form, legacy-process SLC devices vs. radiation-tolerant, mission-grade SLC) onto the macro trajectory, revealing pockets of higher-than-average growth potential driven by aerospace, autonomous systems, and industrial safety applications. The market’s structure also shows a moderate level of supplier concentration: the top three vendors account for roughly 48.7% of revenue, while the top five approach 61.0%. Those concentration metrics have direct implications for supplier risk and bargaining power in 2026.
Dynamics shaping near-term outcomes
-
Raw material & pricing shocks: In 2025 several major NAND suppliers announced price increases exceeding 10%, and spot wafer prices spiked into the double-digit percent range in late 2025. Those moves materially affect BOM economics for embedded systems and compress margin for OEMs that can’t pass increases through to end customers.
-
Regulatory & export controls: Heightened export controls from the U.S. on advanced semiconductor manufacturing and restrictions on select suppliers introduce non-price risk into supply planning. For firms with China-exposed manufacturing or sourcing, alternate qualification paths and local-content rework are pragmatic considerations for 2026 product roadmaps.
-
Geopolitics & tariffs: Escalating trade tensions and newly introduced tariffs on certain regional imports have raised effective landed costs for semiconductor components. Scenario planning in the report simulates tariff-imposed cost cliffs and recommends hedging approaches, including localized second-source strategies and bonded-warehouse use.
-
Supply chain tightness: Spot market dynamics and wafer-price increases create windows where procurement agility — not just scale — determines access to prioritized allocations. Our tactical guidebook for 2026 describes trigger-based inventory and allocation playbooks that minimize capital lock-up while preserving supply resilience.
Competitive landscape — what to monitor in 2026
The Low Density SLC segment is populated by established memory specialists and regional players. Our competitive deep-dive profiles technology, package-level differentiation, and go-to-market motion for each major supplier to support sourcing and partnership decisions.
-
Micron Technology, Inc. — Boise-headquartered Micron has emphasized high-end SLC with exceptional program/erase endurance (up to 100k cycles) and introduced radiation-tolerant variants aimed at space and defense markets. Their positioning signals continued emphasis on mission-critical systems where longevity and radiation-hardening matter most.
-
KIOXIA Corporation — With legacy-process SLC components and industrial-temperature packages, KIOXIA plays to established embedded and industrial code-storage applications. Their product breadth across classic density nodes supports legacy-system replacements and controlled migrations.
-
Winbond Electronics Corporation — Winbond’s ONFi-compliant and HQ serial variants, with extended temperature ratings and automotive/industrial certifications, position them as a pragmatic supplier for harsh-environment and safety-related deployments.
-
Macronix International — Macronix’s parallel and low-voltage SLC offerings remain widely used for firmware and boot storage. Their long-standing ONFi support eases integration into existing board-level designs.
-
Alliance Memory — Focused on serial and parallel SLC with wide temperature support and QSPI options, Alliance targets embedded/IoT device makers seeking compact form factors and rapid access times.
-
GigaDevice Semiconductor — As a regionally significant supplier, GigaDevice supplies cost-effective low-density SLC for industrial and code-storage applications. Their presence is particularly relevant for procurement teams balancing cost and qualification timelines.
Notable recent moves: Micron launched a radiation-tolerant SLC portfolio aimed at space systems in July 2025, and Winbond updated its SLC product brief with ONFi-compliant devices for automotive code storage in September 2025. These product-level developments signal where R&D and customer focus are accelerating.
Practical contents of the PW Consulting report
This market study is intentionally operational. Clients will find the following deliverables that translate directly into 2026 actions:
-
Executive dashboard with headline sizing, CAGR, and supplier concentration metrics, plus scenario-mapped demand curves under alternative geopolitical and pricing states.
-
Segment taxonomies and technology-readiness matrices (product types, temperature grades, endurance classes), with qualification timelines and recommended design-win strategies for each class.
-
Supplier scorecards including technical fit, capacity outlook, contractual red flags, and supplier financial resilience indicators; an M&A watchlist and partner-fit map are included for corporate development teams.
-
Procurement playbook: model contracts, inventory triggers, price-escalation clause templates, and negotiation tactics calibrated to wafer-price volatility and tariff scenarios.
-
Use-case ROI and TCO models: comparative lifetime-cost analyses (SLC vs. alternatives) for selected mission-critical applications supported by sensitivity testing for price and endurance assumptions.
-
Risk register and mitigation matrix covering material price shocks, export-control impacts, single-source failure, and certification/qualification cliffs for automotive and aerospace segments.
-
Implementation roadmap for engineering, procurement and compliance teams to align product qualification, supply strategy, and commercial contracts through the 2026 planning horizon.
Actionable recommendations for 2026
-
Prioritize qualification of at least two suppliers for any long-life SLC use; concentration metrics imply non-trivial single-supplier risk in a market where a few vendors command significant share.
-
Adopt dynamic pricing clauses with transparent pass-through mechanisms tied to wafer-price indices and documented raw-material adjustments to avoid margin erosion when spot costs rise.
-
For space/aerospace and high-reliability industrial designs, favor vendors with demonstrated radiation-tolerant portfolios and high P/E-cycle products, and budget for longer qualification windows.
-
Regionalize supply where tariffs and export controls materially alter landed cost or introduce compliance risk; use bonded-warehousing and local-qualification strategies to preserve market access.
-
Monitor supplier product briefs and roadmap announcements closely — product launches and spec-updates (such as those observed in mid/late 2025) are leading indicators of where lead times and allocation pressure will concentrate.
Methodology & limits — why you’ll want the full dataset
Our base-year is 2025, with historical coverage from 2020–2025 and forecasting to 2032. The forecast uses a hybrid approach blending bottom-up device demand modeling, supplier capacity reads, and scenario-based macro overlays for pricing and geopolitics. To preserve the commercial value of our proprietary analysis and the confidentiality of some supplier-reported figures, granular subsegment tables (including device-level market shares, region-by-application splits, and explicit price curves) are redacted from this public summary. These withheld elements are the decision-grade inputs procurement and product teams need to execute on the recommendations above.
Next step
For procurement directors, product leaders, and corporate strategists preparing 2026 plans, PW Consulting’s full Low Density SLC NAND Flash Memory Market report provides the actionable tables, contract language, and supplier risk heatmaps required to move from strategy to execution. Access to the complete dataset and the supplier-model spreadsheet is available through our report portal; these proprietary materials contain the granular breakouts that underpin the executive recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Low Density SLC NAND Flash Memory Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Brake Pads Market to Reach USD 5.2 Billion by 2032 — 5.0% CAGR: PW Consulting Insight
By pmarketresearch, 2026-07-13
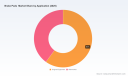
Brake Pads Market: Strategic Imperatives for 2026
As competitors, regulators, and original-equipment manufacturers (OEMs) recalibrate their strategies for the post‑pandemic automotive landscape, brake pads remain a deceptively strategic product category. At first glance the market is mature and commoditized; beneath the surface, however, evolving regulation, material science, and platform transitions are reshaping cost structures, distribution economics, and product roadmaps. This briefing summarizes the strategic value of PW Consulting’s Brake Pads Market research for board-level and executive decision-making in 2026, and highlights the practical actions the full study enables. For commercial reasons we intentionally withhold granular regional and application splits here; the full report contains those tables and downloadable datasets.
Brake Pads Market
Market trajectory and headline economics
Using 2025 as the base year, the global brake pads market has expanded steadily over the past half‑decade and is projected to continue on a moderate growth path through 2032. Our topline model shows the market growing from the low‑single‑digit billions in 2020 to approximately USD 3.8 Billion in 2025, with a steady compound annual growth rate of roughly 5.0% into the 2026–2032 forecast horizon and an expected market size exceeding USD 5 Billion by 2032. These aggregated dynamics mask important inflection points—regulatory compliance costs, raw‑material pricing differentials, and platform shifts tied to electrification—that will materially influence margins and capital allocation decisions in 2026 and beyond.
Brake Pads Market
Regulatory forces and material constraints
-
Copper and heavy‑metal restrictions have moved from policy proposals to enforceable standards in multiple jurisdictions. States such as California and Washington have established sub‑0.5% copper thresholds for brake pads, with certification and marking requirements already in force. The U.S. EPA’s copper‑reduction initiatives similarly raise compliance and traceability demands for suppliers and distributors.
Brake Pads Market -
These regulatory constraints are not purely compliance costs. They alter product design (alternative friction formulations), testing regimes (proof marking and certification), and supply chain complexity (sourcing of specialized binders and friction modifiers). Companies that anticipated the compliance curve enjoy first‑mover cost advantages; others face retrofit expenses and catalog relabeling costs.
-
Material and labor economics compound the picture. Ceramic formulations command a premium because of costlier friction modifiers and binders, while high‑precision manufacturing—especially where certification and low‑dust, low‑noise properties are required—drives up labor content. North American facilities, in particular, report higher unit labor costs tied to stringent quality controls and auditing processes.
Competitive landscape: positioning and strategic moves
The brake pads market presents a mix of global OEM suppliers, specialist niche players, and large aftermarket consolidators. Market concentration at the top remains modest—an indicator of continued fragmentation and opportunity for scale plays. Below we synthesize company positioning and strategic implications for 2026 planning.
-
Brembo S.p.A. (Italy) continues to lead with premium performance and fleet‑oriented severe‑duty lines. Brembo’s product architecture—covering ceramic, sintered, and metallic compounds—targets both high‑performance OEM fitment and specialized fleet requirements. Their recent Severe Duty launch underscores a deliberate move to capture high‑load commercial applications where durability and regulatory compliance are value drivers.
-
Akebono Brake Industry (Japan) has leveraged ceramic expertise and low‑copper formulations to strengthen OEM and aftermarket positions across Asia and North America. Their ProACT and Severe Duty portfolios reflect a strategy of marrying performance with regulatory alignment—an imperative in markets enforcing copper limits.
-
MAT Holdings / Bendix (USA) and other large North American players focus on broad aftermarket coverage and value‑added lines (e.g., QuietCast). Their scale in distribution and catalog breadth is a defensive moat, but margin pressure from raw‑material inflation and certification costs requires product mix optimization.
-
Robert Bosch GmbH and ZF Friedrichshafen (TRW) (Germany) combine OE know‑how with aftermarket branding. Both emphasize low‑noise/low‑dust ceramic solutions and have initiated copper‑free or reduced‑copper formulations, including offerings tailored to hybrid and electric vehicle drivetrains.
-
Textar (TMD Friction) , Continental (ATE) , Knorr‑Bremse , and Nisshinbo retain strong European and OEM coverage with deep intellectual property in friction material science—assets that can be monetized via licensing or co‑development partnerships.
-
Müller Brakes America , Brake Parts Inc. , and specialist performance brands such as EBC Brakes exploit niches—performance, heavy‑duty, and specialty two‑wheel segments—where formulation and compound differentiation justify premium pricing.
-
Hitachi Astemo illustrates the integrated systems play, supplying pads as part of broader brake module and safety system offerings—an increasingly attractive value proposition for OEMs integrating active safety and ADAS functionality.
Recent market signals
-
New product introductions and range extensions in 2025–2026 show manufacturers are prioritizing coverage, compliance, and specialty use cases. Examples include broad portfolio expansions by aftermarket players and Brembo’s Severe Duty line aimed at fleet/high‑load scenarios.
-
Volume plays continue: some regional distributors released hundreds of new SKUs in 2026 to expand coverage and capture replacement demand across older vehicle parc segments.
-
Two parallel trends are apparent: consolidation of SKU coverage to reduce stocking complexity, and targeted premium launches that defend margin against raw‑material inflation.
Market structure: fragmentation and opportunity
The market exhibits moderate concentration at the top and a long tail of regional specialists. That structure has three strategic consequences:
-
Margin expansion is achievable through premiumization (ceramic, severe‑duty formulations) and compliance‑driven product upgrades, but these strategies require upfront R&D and certification investment.
-
Scale in distribution—catalog depth and fulfillment reach—remains a durable competitive advantage in aftermarket channels; digital cataloging and coverage accuracy are differentiators in B2B procurement.
-
M&A remains an actionable lever for buyers seeking rapid entry into low‑copper formulations, geographic coverage, or technical IP. Selective consolidation can unlock procurement synergies and accelerate compliance roadmaps.
What the PW Consulting Brake Pads Market report delivers (practical contents)
-
Top‑down and bottom‑up market sizing with year‑by‑year historicals (2020–2025) and deterministic forecast model (2026–2032) usable in corporate planning systems.
-
Regulatory compliance roadmap detailing jurisdictional timing, certification requirements, and an estimated cost curve for reformulation and proof marking.
-
Competitive heatmap and supplier scorecards covering product portfolios, technical strengths, go‑to‑market models, and partnership opportunities.
-
Raw‑material sensitivity analysis assessing the impact of ceramic‑price swings, binder costs, and labor variance on unit economics.
-
Channel economics and aftermarket distribution playbooks, including SKU rationalization approaches and inventory reduction levers.
-
M&A target shortlist and valuation framework focused on technology, coverage gaps, and regional distribution assets (note: detailed target valuations are contained in the full report).
-
Three scenario plans (baseline, high‑regulation, and accelerated electrification) that translate market trajectories into capex, inventory, and margin implications for 2026 planning cycles.
Priority strategic moves for 2026
-
Adopt a compliance‑first product roadmap: prioritize certification for low‑copper formulations in markets with active regulation and implement traceability systems to avoid distribution interruptions.
-
Segment product architecture by value capture: preserve semi‑metallic cost leadership in price‑sensitive channels while expanding high‑margin ceramic and severe‑duty ranges where technical differentiation is defensible.
-
Invest in catalog accuracy and digital bilateral integration with distributors and OEMs to reduce returns, improve fill rates, and accelerate conversion of aftermarket customers.
-
Pursue targeted M&A or JV activity to secure IP, low‑copper compound capabilities, or regional distribution footholds rather than broad horizontal roll‑ups.
-
Manage procurement through long‑term supply agreements for binders and friction modifiers, and consider dual‑sourcing strategies to mitigate single‑supplier exposure.
-
Develop workforce upskilling programs focused on quality assurance and certification testing to lower rework rates and maintain margin integrity in high‑precision facilities.
Why this matters for 2026 decision cycles
CEOs and heads of strategy must treat brake pads not as a static commodity line but as a node where regulation, materials innovation, and distribution economics converge. Decisions made in 2026—on R&D prioritization, certification investment, and distribution sourcing—will determine who captures the premium pockets of growth identified in our forecast and who will see margin compression as compliance costs bite. The aggregated market growth of about 5.0% CAGR masks both upside pockets and downside exposure; navigating that variance requires the market‑level granularity and scenario tooling contained in the full PW Consulting study.
Next steps
To access the full data tables, company scorecards, regional and application splits, and downloadable forecast models that support capital allocation and M&A screening, consult the PW Consulting Brake Pads Market report page. The full deliverable converts the strategic imperatives summarized here into executable 12‑ and 36‑month plans, tailored to supplier, distributor, and private‑equity buyer use cases.
For detailed analysis of this topic, please visit the official page: Brake Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bead Wire Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Bead Wire (Tyre Bead Wire) Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a concise, action-focused overview of the Bead Wire (Tyre Bead Wire) market that frames where executive choices in 2026 will yield disproportionate advantage. This narrative integrates the headline market dynamics — from historical sizing to a clear forecast trajectory — while deliberately reserving detailed segment-level tables and numerical breakdowns for the full report. Think of this piece as the strategic trailer: it proves we understand the market’s levers and inflection points, while directing your commercial and investment teams to the full study for execution-grade granularity.
Bead Wire (Tyre Bead Wire) Market
Headline market trajectory: sizing, growth, and what it implies
The bead wire market has moved from a modest baseline in 2020 to a materially larger industry by 2025, reflecting steady demand for tire reinforcement in both passenger and commercial vehicle segments. PW Consulting’s base-year assessment (2025) and modelled forecast to 2032 indicate a compound annual growth rate of approximately 6.98% through the forecast window. Under our baseline scenario, market value advances noticeably from 2025 into 2026 and continues to expand through 2032, driven by rising light-vehicle production, replacement tire volumes, and selective premiumization trends.
Bead Wire (Tyre Bead Wire) Market
For strategy teams, two quick implications follow: (1) market expansion is predictable enough to justify staged capacity and capability investments, and (2) growth concentrated in value-added coated and high-performance bead wire variants amplifies margin opportunities for market participants that can deliver consistent quality, regulatory compliance, and supply resilience.
Bead Wire (Tyre Bead Wire) Market
Why 2026 is a pivotal planning year
- Raw-material shock exposure : High-carbon steel wire rod accounts for the majority of bead wire production cost. Recent historical volatility — including a single-quarter price swing of nearly 28% in 2024 — shows material prices remain a dominant earnings risk. Procurement strategies that begin in 2026 will determine unit economics for several fiscal years.
- Regulatory and standards alignment : Global adoption of tensile and coating standards (e.g., ISO 6892-1 and ASTM A825) is tightening quality expectations. Companies that align product development, QA processes, and supplier audits to these standards now will avoid costly retrofits and qualification delays with OEMs.
- OEM demand signals : The global automotive production backdrop — including a projected increase in light-duty vehicle volumes — underpins predictable long-term demand. 2026 decisions on capacity, automation, or regional footprint will intersect with OEM sourcing cycles and should be synchronized accordingly.
What the full report delivers — practical, executable intelligence
PW Consulting’s Bead Wire market study is constructed for buyer-side and supplier-side leaders who need to translate market insight into executable plans. Highlights of the full deliverable include:
- Integrated market-sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario runs (base, downside, and upside) to stress-test capacity and revenue plans.
- Supply-chain heatmaps and raw-material exposure matrices that quantify sensitivity to wire-rod price moves and identify hedging and vertical-integration levers.
- Regulatory and standards impact assessment — mapping compliance requirements to product specifications and certification timelines for primary markets.
- Commercial playbooks for supplier selection, pricing architecture, and contractual protections (indexation clauses, minimum take-or-pay constructs, and quality SLAs).
- Technology and product roadmaps that prioritize coatings, polymer-hybrid innovations, and nickel/hybrid solutions — including implementation timelines, cost buckets, and margin uplift scenarios.
- Actionable M&A and CAPEX decision frameworks: acquisition target screening attributes, integration checklist, and break-even analyses for greenfield lines versus brownfield expansions.
- Benchmarking templates and supplier scorecards that accelerate vendor rationalization without sourcing disruptions.
Each module is designed to move teams from insight to decision — a short-list of prioritized moves for procurement, operations, R&D, and corporate development in 2026.
Competitive landscape — players, positioning, and strategic moves
The bead wire market remains commercially accessible to both regional specialists and globally integrated steel-wire manufacturers. Market concentration metrics show a relatively fragmented landscape, leaving room for scale and differentiation plays. Below, we summarize the strategic posture of leading participants featured in our competitive analysis.
- Bekaert (Belgium) — A technology-forward supplier with a portfolio of precision-engineered high-carbon bead wire. Their configurable diameters, tensile specifications, and multiple coating options position them well for OEMs demanding tightly-controlled mechanical properties and sustainable packaging. Bekaert’s engineering-first approach is an advantage in specifications-heavy premium tire programs.
- Rajratan Global Wire Ltd (India) — A high-volume, cost-competitive producer with substantial manufacturing capacity and an established footprint in South Asia and Southeast Asia. Rajratan’s scale, combined with a broad diameter range and presence across passenger, commercial, and two-wheeler tire segments, gives them strong price-competitive credentials for global and regional tire makers.
- Kiswire Ltd (South Korea) — Known for steel cord leadership, Kiswire brings advanced coating technologies (including nickel and polymer-hybrid approaches) into bead wire applications. Their R&D trajectory emphasises weight reduction and premium reinforcement technologies that appeal to high-performance tire programs and EV-oriented applications.
- Elsewedy Steel (Egypt) — Leveraging a dedicated bead wire production area and sustainability messaging, Elsewedy competes on quality and regional proximity for African, Middle Eastern, and Mediterranean markets. Their recent product showcases signal intent to engage top-tier tire manufacturers.
- Heico Wire Group (USA) — Operating as part of a broader metal processing portfolio, Heico brings flexible production and route-to-market advantages in North America, which can be decisive for just-in-time OEM supply chains.
- Aarti Steel International Limited (India) — A specialist wire producer with a focus on tailored tyre bead wire offerings; suitable for mid-market and regional tire manufacturers seeking a balance of cost and customization.
- Jiangsu Xingda Steel Tyre Cord Co., Ltd (China) — Integrated tyre cord and bead wire capacities with recent expansions; their proximity to large tire clusters and integrated supply chain can provide competitive logistics and lead-time dynamics to Asian tire makers.
Notable recent activity includes product showcases and trade-expo participation by several manufacturers, underlining a market push for differentiation through coatings, sustainability claims, and performance metrics. These tactical moves are early signals of competitive positioning to support new tire programs and premium applications.
Structural dynamics and risk factors
- Raw-material concentration risk — Given the outsized share of production cost attributable to high-carbon steel wire rod, companies that do not implement proactive procurement protections (long-term contracts, blended sourcing, or strategic inventories) will experience margin compression when spot prices spike.
- Standards-driven product requalification — Increasing alignment with tensile and coating standards raises the bar for new suppliers; time-to-qualification is a commercial gating item for OEM programs.
- Cost-to-performance trade-offs — Bead wire generally represents a single-digit percentage of total tire manufacturing costs, but minor composition or coating changes can materially affect tire reliability and performance. This creates a dual imperative: control cost without compromising specification compliance.
- Fragmentation and consolidation opportunity — Current concentration levels indicate both room for consolidation and for niche premium players to thrive. M&A strategies should balance scale benefits with the risk of integration complexity across geographies and product platforms.
Recommended 2026 playbook — prioritized actions
- Hedge and diversify raw-material exposure : Lock in a mix of indexed and fixed-price contracts in 2026, create tiered inventory thresholds, and evaluate upstream partnerships or minority stakes in wire-rod suppliers.
- Accelerate standards-compliance roadmaps : Invest in in-line quality instrumentation and independent certification pipelines so that new product variants can be qualified with OEMs within a single procurement cycle.
- Prioritize premium coatings and hybrid technologies : Reallocate incremental R&D and CAPEX towards higher-margin coated and polymer-hybrid solutions that serve EV and high-performance tire segments.
- Regionalize supply to match OEM footprints : Use a regional supply play where lead-time and inventory costs matter more than unit price — particularly for just-in-time programs in mature automotive clusters.
- Use the report’s M&A matrix : Target bolt-on acquisitions to fill capability gaps (coatings, surface treatment, sustainable packaging) rather than broad horizontal roll-ups that require deep integration.
Next step: where to find the full playbook
This overview surfaces the strategic inflection points we observe heading into 2026, and the decisions that will differentiate winners from laggards. For procurement directors, strategic-planning leads, and corporate development teams planning investments or supplier strategies next year, the full PW Consulting report provides the operational granularity you will need — including downloadable models, supplier scorecards, contract template clauses, and a prioritized action calendar tied to our forecast scenarios.
Accessing the complete study will equip teams to convert the directional hypotheses set out here into executable 90-, 180- and 360-day plans. Our full dataset includes the detailed segment splits, regional demand drivers, and per-variant economics that we intentionally omitted here to preserve the strategic trailer effect and to encourage direct engagement with the full source materials.
PW Consulting remains available to support tailored workshops, model customizations, and rapid due-diligence assignments for supply-chain reconfiguration or M&A activity in the bead wire value chain.
For detailed analysis of this topic, please visit the official page: Bead Wire (Tyre Bead Wire) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rollator Walker Market to reach USD 134.9M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-13
Rollator Walker Market 2026: Strategic Imperatives for Private Equity, Manufacturers and Health Systems
As demographic shifts, product innovation and reimbursement pressure reshape the mobility-aid landscape, 2026 is shaping up to be a pivotal year for executives and investors active in the rollator walker market. PW Consulting’s latest market study synthesizes five years of historical performance with a 2026–2032 forecast to convert industry noise into decision-ready intelligence. This executive introduction highlights the study’s strategic value for corporate planning while intentionally preserving the granular segment-level datapoints that underpin our proprietary models—access to which is available in the full report.
Rollator Walker Market
Market snapshot you can act on
After steady growth through the early 2020s, the rollator walker market reached approximately USD 90.8 Million in our 2025 base year and is forecast to expand at a compound annual growth rate of 5.8% over the 2026–2032 horizon. Underlying this topline are durable secular drivers—aging populations in advanced markets, increased rehabilitation utilization after inpatient stays, and a faster migration to lightweight and premium materials—that together create both near-term margin compression risks and mid-term premiumization opportunities.
Rollator Walker Market
Why 2026 is strategically different
- Regulatory inflection: Medicare billing rules and assistive-device coding remain central to commercial viability in the largest purchaser cohorts. The Durable Medical Equipment (DME) reimbursement environment continues to favor clinically validated devices that can be aligned to existing billing pathways.
- Standards-driven differentiation: ISO 11199-2:2021 has become a de facto quality baseline. Manufacturers that integrate ISO-aligned testing into product design reduce commercial friction with institutional buyers and differentiate on safety and durability.
- Cost-to-serve pressure: Rising logistics and materials costs have accelerated SKU rationalization across suppliers—steel-frame SKUs are being phased out or re-engineered in favor of lightweight aluminum and carbon composites to manage per-unit logistics and customer appeal.
- Product innovation wave: Recent launches demonstrate two clear vectors—off-road, stability-focused designs for broader out-of-home mobility, and ultra-lightweight, carbon-aluminum hybrids for active users seeking portability without sacrificing support.
Strategic levers for decision-makers
For CEOs, private equity sponsors and commercial leaders, the report translates macro growth into executable options across five core levers.
Rollator Walker Market
- Portfolio prioritization: Differentiate between products that drive volume in institutional channels (e.g., durable, low-cost models) and those that enable margin expansion through premiumization (lightweight, carbon components, ergonomic seating). The right SKU set reduces service complexity and improves inventory turns.
- Channel reconfiguration: Institutional procurement, specialty retailers and direct-to-consumer channels each demand distinct commercial models. Our go-to-market maps identify where to deploy inside sales, clinical education teams, and e-commerce investments to optimize acquisition costs.
- Clinical evidence and reimbursement alignment: Devices that can be justified under existing clinical codes capture higher ASPs and lower resistance from payors. We map the clinical outcomes most persuasive to physiotherapists, occupational therapists and procurement committees.
- Supply-chain resilience: Material choices (aluminum vs. composites) and freight sensitivity should inform nearshoring or multi-sourcing strategies. Our scenario models quantify trade-offs between landed cost, weight-sensitive logistics and service lead times.
- M&A and partnership articulation: Rollator product lines can create attractive tuck-in opportunities for distributors or yield platform consolidation targets for strategic consolidators seeking scale in manufacturing, R&D and distribution.
Competitive landscape — who matters and why
The competitive fabric remains a mix of global incumbents, specialty European design houses and regional innovators. Rather than presenting market shares, PW Consulting’s analysis evaluates each firm against four strategic dimensions: product portfolio breadth, manufacturing footprint and materials capability, channel access (institutional vs. retail vs. direct), and clinical/reimbursement positioning.
- Drive Medical (Nashville, TN) — plays to breadth and scale with a portfolio that spans ultralight and performance-oriented rollators. Their product strategy balances mainstream hospital demand with higher-margin lifestyle models.
- Invacare Corporation (Elyria, OH) — legacy strength in bariatric and institutional models. Leadership here is in durability and broad channel penetration, particularly where regulatory and procurement cycles favor established suppliers.
- Bischoff & Bischoff GmbH (Germany) — a premium design-led competitor with successful collaborations that elevate perceived value (e.g., designer partnerships). Recent lightweight aluminum launches underscore a move to combine lifestyle appeal with practical functionality.
- Trionic Sverige AB (Uppsala, Sweden) — differentiated by off-road and ergonomics-focused designs. Their 2026 four-wheel walker introduction signals a focus on posture support and braking systems for active mobility use cases.
- Human Care HC AB (Sweden) — innovative cross-folding and portability design strengths, making the brand attractive in homecare and community mobility segments.
- Evolution Technologies Inc. (Canada), Karman Healthcare, Graham-Field and Nova Medical — represent a cluster of specialists driving incremental innovation around weight, braking systems and modular accessories for specific clinical or lifestyle subsegments.
Recent product launches in early 2026 illustrate how competitive advantage is increasingly built from engineering trade-offs rather than price alone: lightweight aluminum rollators with improved seating ergonomics, and four-wheel designs with responsive braking and posture support. These moves suggest an arms race along usability, perceived safety and premium materials rather than purely on price.
Regulatory and standards dynamics that shape strategy
- Reimbursement alignment: Manufacturers and distributors that map product claims and clinical data to established billing codes reduce cycle time to payer acceptance and accelerate institutional adoption.
- Standards compliance: ISO 11199-2:2021 compliance is table stakes for procurement teams in hospitals and long-term care facilities. Embedding standardized testing into product roadmaps reduces the cost of customer qualification.
- Procurement behavior: Large buyers increasingly adopt value-based procurement frameworks that weight lifecycle costs, clinical outcomes and safety—benefitting vendors who can demonstrate lower total cost of ownership (TCO).
Practical contents of the PW Consulting study
This report is built for operators and investors who must make 2026 capital allocation, go-to-market and product decisions. Key practical deliverables include:
- Top-down market sizing with scenario forecasts to 2032, including sensitivity to reimbursement shifts, raw-material price trajectories and channel migration.
- Demand- and supply-side unit economics: contribution-margin models by device archetype, SKU-level cost-of-goods with freight and aftermarket support overlays.
- Go-to-market playbooks for institutional, retail and direct channels—resource allocation, sales force sizing, and digital strategies tuned to adoption cycles.
- Clinical and reimbursement playbook mapping device features to claims and billing pathways to accelerate hospital and DME adoption.
- Comprehensive competitor dossiers: capability matrices, patent and design-intellectual-property analyses, recent product roadmaps, and scenario-based response strategies.
- M&A screening models and synergy calculators for tuck-ins and roll-ups, including integration-risk checklists and three-year synergy capture timelines.
- Operational scorecards and KPIs for manufacturing prioritization (weight vs. durability trade-offs), SKU rationalization, and after-sales service economics.
How to use this intelligence in 90 days
- CEOs: Prioritize one quick-win SKU rationalization and one medium-term premium product program. Use our TCO thresholds to de-risk pricing moves with major institutional customers.
- Private equity: Apply our M&A screening model to shortlist targets that deliver scale in distribution or that own design/IP assets enabling material-light rollators.
- Product leaders: Validate new materials and braking-system investments against our clinical-efficacy matrix before committing to tooling or supplier contracts.
- Commercial teams: Rebalance channel investments toward specialty retailers and digital D2C pilots where margin-accretive adoption curves are visible in our channel analysis.
Why PW Consulting’s study matters for 2026 decisions
We translate industry signal noise into prioritized, risk-weighted actions. The combination of an actionable forecast (anchored by a 2025 base), scenario-based cashflow impacts, and supplier- and channel-level playbooks gives decision-makers the capacity to shift from defensive inventory and cost plays to selective premiumization and targeted consolidation.
Importantly, this executive brief does not reproduce the full set of granular splits by region, device type or application that drive valuation and operational levers. Those segment-level tables, underlying models, and downloadable scenario workbooks are available in the full PW Consulting report and downloadable client kit—designed to be immediately used by strategy teams and transaction committees.
Next steps
If you are planning capital allocation, product roadmap shifts, or potential M&A activity in 2026, PW Consulting’s Rollator Walker Market study is the tactical intelligence you need to move from hypothesis to executable plan. The full report contains the segment breakout tables, scenario model access, and detailed competitor appendices required to run due diligence and build three-year operating plans.
Contact PW Consulting to obtain the full report and the accompanying modeling toolkit—our team will walk you through the specific modules most relevant to your corporate role and decision timetable.
For detailed analysis of this topic, please visit the official page: Rollator Walker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Inkjet Printer Head Market to Reach USD 148.3M by 2032, 4.1% CAGR
By pmarketresearch, 2026-07-13
Inkjet Printer Head Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
The inkjet printer head market is at an inflection point. After a steady recovery through the early 2020s, the global market — measured on a USD million revenue basis — expanded from roughly USD 93 million in 2020 to about USD 112.5 million in the 2025 base year used for this research. Our forecasting horizon through 2032 projects a compound annual growth rate (CAGR) of 4.1%, with the market continuing to evolve in complexity and commercial opportunity as industrial, packaging, electronics and additive-manufacturing applications deepen their reliance on high-performance printheads.
Inkjet Printer Head Market
This preview is designed to orient senior executives, product leaders and corporate strategists to the forces that will determine winners and losers in 2026. It highlights directional market dynamics, technology inflection points, competitive positioning and the practical, decision-focused deliverables included in the full PW Consulting study — while intentionally withholding the granular, proprietary segment breakdowns that are only available in the complete report.
Inkjet Printer Head Market
Why 2026 matters
-
Operational cadence: Investment cycles and capex plans locked down in 2026 will shape manufacturing throughput and materials sourcing into the early 2030s. With the market already above the USD 100‑million mark in recent years and a predictable mid-single‑digit CAGR, 2026 is the last full year for many firms to align roadmaps with forecasted demand curves.
Inkjet Printer Head Market -
Technology convergence: Advances in thin‑film piezoelectric fabrication, MEMS-based silicon actuators and recirculation architectures are lowering barriers to higher-viscosity fluids and multi-color heads. These technical advances create opportunities to displace incumbent solutions in established verticals and to address adjacent industrial deposition markets.
-
Regulatory and sustainability inflection: Tighter environmental rules and circular‑economy initiatives — particularly in Europe — are accelerating adoption of monitoring-enabled printheads and sustainable materials strategies. Compliance with standards such as RoHS variants, flame retardancy benchmarks and PCB material safety protocols is increasingly non-negotiable for OEMs and end users.
Market trajectory and what it implies
The market’s trajectory over 2020–2025 demonstrates resilience despite episodic demand swings. The transition into 2026 is best described as measured growth rather than runaway expansion: the sector is maturing. For executives this means strategy should shift from “land-grab” expansion to focused value capture — optimizing unit economics, reducing total cost of ownership for buyers and extracting services revenue tied to predictive maintenance and nozzle-health analytics.
Consolidation dynamics are visible. The market concentration metrics indicate that a small set of global OEMs controls a meaningful share of revenue and technology supply — creating an environment where partnerships, selective M&A and component-level differentiation are effective levers for middle-tier players to scale rapidly. For large incumbents, the imperative is to defend platform positions while accelerating adjacent capabilities (e.g., electronics, ink chemistry partnerships, and embedded diagnostics).
Technology and supply‑chain realities
-
PZT and thin‑film piezo technology remain a performance backbone. Sputtered PZT actuators and fine ceramics piezoelectric stacks enable trillions of actuations in modern heads, delivering both durability and cost‑efficiency at scale. These materials and processes are central to long‑lived industrial heads used in high-throughput packaging and textile machines.
-
Recirculation, multi‑color heads and high‑viscosity capabilities are moving from niche to mainstream. Vendors are addressing reliability and clogging through mechanical and software controls rather than purely chemical fixes — a shift that elevates the role of electronics and embedded diagnostics in product roadmaps.
-
PCB and materials compliance has become a functional differentiator. Printhead modules and their PCBs increasingly must meet flammability and hazardous‑substance standards, a requirement that affects supplier selection, certification timelines and aftermarket liability.
Competitive landscape — who to watch
The competitive set is technologically heterogeneous but strategically aligned around high-resolution, industrial-grade printheads and systems integration. Leading OEMs are leveraging proprietary actuator technologies, platformized mechanical designs and service ecosystems to sustain margins.
-
Konica Minolta (Tokyo) — A leader in thin‑film piezo platforms and high-resolution industrial heads. Recent launches in late 2025 showcased multi‑color jetting capability from a single head and new KM1800i variants designed for demanding PCB and deposition uses. These product moves underscore a strategy of enabling higher throughput applications while ensuring regulatory compliance across PCB and material standards.
-
Xaar plc (Cambridge, UK) — Known for industrial drop‑on‑demand piezo heads and modular printbars, Xaar’s engineering emphasis on ceramics and high-viscosity fluid handling positions it strongly in packaging and industrial graphics, where robustness and throughput are prioritized.
-
FUJIFILM Dimatix (Lebanon, NH) — Their VersaDrop and sputtered PZT actuator technology underpins strong performance in materials deposition and specialized industrial applications. Their technology depth makes them a frequent partner for companies trialing functional inks or electronic deposition use cases.
-
Meteor Inkjet (Cambridge, UK) — A critical ecosystem player rather than a head manufacturer, Meteor differentiates through electronics, software and nozzle‑health monitoring that enable third‑party heads to be run at optimal performance. Their recent support announcements for new Ricoh hardware illustrate the rising importance of electronic and software compatibility layers.
-
Ricoh (Tokyo) — A major force in MEMS and thin‑film piezo-based heads with designs emphasizing recirculation and high-speed coding/packaging use. Ricoh’s product families are commonly selected where industrial uptime and long maintenance intervals are required.
-
Seiko Instruments (SII Printek, Matsudo) — Offers heads with isolated channel architectures and a strong presence in wide‑format and coding applications. Their differentiated fluidic architectures reduce cross‑talk and maintenance overhead in demanding environments.
-
Kyocera (Kyoto) — Focuses on fine‑ceramics actuators for high-speed, high‑image‑quality needs and has recently introduced hardware aimed at high‑viscosity materials, signaling intent to capture share in materials‑heavy industrial markets.
Across the competitive set, recent product activity (late‑2025 to mid‑2026) shows a clear emphasis on multi‑color capability, high‑viscosity material handling and enhanced electronics/software support. These trends reflect buyers’ priorities: higher throughput, lower downtime, and more rapid integration into industrial production lines.
Regulation, sustainability and operational risk
-
Compliance is now table stakes. Leading vendors publicly ensure compliance with flammability standards, RoHS variants and industry PCB protocols — a necessary condition for participation in regulated supply chains.
-
Environmental and circular‑economy initiatives in key markets are driving demand for monitoring-enabled heads and reduced consumable consumption. Buyers are increasingly procuring systems that provide measurable ink‑use efficiencies and defect-reduction telemetry.
-
Materials availability — especially for specialized piezo ceramics and thin‑film deposition inputs — remains a strategic procurement risk. Buyers and OEMs that lock in multi‑year supply agreements or vertically integrate thin-film processing gain a durable advantage.
What PW Consulting’s full report delivers
The full study is built for action. For executives evaluating investments in 2026, the report provides:
-
Proprietary market sizing and scenario forecasts through 2032, including demand drivers by vertical and technology pathway (note: detailed segment tables and proprietary model outputs are reserved for the full report).
-
Technology benchmarking: comparative analysis of actuator types, fluidic architectures, and electronics/software stacks with recommended adoption roadmaps by use case.
-
Buy‑side playbooks: total cost of ownership (TCO) templates, procurement negotiation anchors, and integration checklists for OEMs and end users.
-
Supply chain and materials heatmap: critical input risk assessments, supplier scorecards and mitigation options (including capex scenarios for in‑house thin‑film capability).
-
Competitive intelligence dossiers on leading vendors, with product roadmaps, go‑to‑market strategies and potential M&A targets aligned to 2026 strategic windows.
-
Regulatory and compliance compendium: practical guidance for meeting flammability, hazardous‑substance and circular‑economy requirements across major markets.
-
Operational and service design templates: nozzle‑health analytics, predictive maintenance architectures, and aftermarket monetization models.
How to use these insights in 2026
-
Product strategy — prioritize platform architectures that support modular upgrades (electronic and fluidic) to protect R&D investments against rapid technology shifts.
-
Partnerships — seek alliances with electronics/software specialists to deliver differentiated uptime and telemetry; consider commercial models that bundle hardware with predictive‑maintenance services.
-
Procurement — secure multi‑year supply agreements for critical thin‑film and piezo materials; build flexibility clauses that allow for rapid scaling as forecasted demand materializes.
-
M&A and investment — target companies that add nozzle‑health, software, or specialized materials capabilities; prioritize assets that accelerate time‑to‑market for high‑viscosity and multi‑color heads.
-
Regulatory readiness — embed compliance validation early in product development cycles to avoid costly rework and to access regulated buyers sooner.
Final note — a preview, not the whole story
This introduction synthesizes the strategic contours that will define winning plays in the inkjet printer head market across 2026 and beyond. It intentionally abstracts away the granular segment tables, regional splits and proprietary model outputs that are required to translate insight into executable plans. For organizations planning procurement cycles, product roadmaps or acquisition screens in 2026, the full PW Consulting report provides the detailed, actionable intelligence and model access necessary to move from strategy to execution.
Contact PW Consulting to request the full market study, access the model workbook and schedule a bespoke briefing for your leadership team.
For detailed analysis of this topic, please visit the official page: Inkjet Printer Head Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Margarine Market 2026 Strategic Preview — Navigating Moderate Growth, Supply Pressure, and the Sustainability Turn
As companies plan budgets, product roadmaps, and M&A pipelines for 2026, the margarine market presents a classic strategic paradox: structural stability at the top-line level, but accelerating disruption at the input, regulatory, and channel layers. Our PW Consulting Margarine Market study (base year 2025) shows a market that finished 2025 at roughly USD 23.6 Million and is projected to grow at a measured compound annual growth rate (CAGR) of 2.1% through the 2026–2032 forecast window, reaching the high‑20s by 2032. These headline figures mask important vectors of change that will determine winners and losers in the next 12–24 months.
Margarine Market
Executive snapshot — what 2026 decision-makers need to know
-
Top-line stability: After modest volatility in the early 2020s, the global market has resumed a steady, low-single-digit growth trajectory. That predictability creates an opening for margin-focused investments rather than aggressive volume gambits.
Margarine Market -
Fragmented competitive structure: Industry concentration is low-to-moderate; the leading three firms control roughly one quarter of the market while the top five account for just under 30%. The implication is clear — scale matters, but meaningful niches remain contestable.
Margarine Market -
Input and regulatory risk are the principal sources of strategic surprise. Cost exposure to vegetable oils, compounded by trade measures and sustainability regulations, will be the single largest determinant of producer margin trajectories in 2026.
-
Commercial levers will be differentiated by channel: innovation and premiumization in retail and foodservice versus cost-efficiency and formulation reliability in industrial/bakery segments.
Market dynamics shaping 2026 strategy
-
Raw material volatility and substitution dynamics: The market’s sensitivity to vegetable oil inputs has increased. Price volatility and evolving sourcing policies are prompting formulators to redesign recipes, optimize blends, and accelerate substitution where acceptable. Procurement teams must adopt a more sophisticated hedging and supplier segmentation approach; tactical spot buying is no longer sufficient for margin management.
-
Regulatory pressure and traceability requirements: New regulatory frameworks—particularly in major consumption markets—are elevating the cost of compliance for palm-based inputs. Requirements for geolocation, chain-of-custody documentation, and risk-based due diligence will force manufacturers to either absorb compliance costs, pass them to customers, or reformulate with certified alternatives. The 2026 compliance calendar makes this a near-term board-level issue.
-
Channel-driven product innovation: Retail and foodservice continue to demand differentiated spreads—high-fibre, functional lipids (omega enrichment), and cleaner label formulations. Conversely, industrial customers prioritize processing stability and cost per bake. Our interviews indicate that successful product launches in 2024–25 focused on either clear consumer-facing claims or demonstrable operational efficiencies for B2B customers.
-
Sustainability as a competitive moat: Sustainability certification and transparent supply chains have moved from marketing garnish to procurement prerequisite. Brand owners and industrial buyers increasingly pre-qualify suppliers on documented low-deforestation risk or certified-sourcing credentials. Producers without clear, auditable sourcing strategies will face narrowing of tender opportunities.
Competitive landscape — strategic moves to watch
The market is populated by a mix of global commodity integrators, regional specialty players, and ingredient system suppliers. Each group operates with distinct strategic logic:
-
Global integrators and oil majors: These firms leverage upstream integration to offset input volatility and supply certified volumes to global customers. They are natural acquirers when scale can unlock cost synergies across processing and logistics.
-
Regional value-add players: European and APAC-focused manufacturers compete on brand recognition, product tailoring, and service to biscuits/bakery segments. Their agility on formulation often outpaces global players constrained by large-scale asset footprints.
-
Ingredient solutions and co-manufacturers: Suppliers that offer functional blends and customized ingredient systems capture premium margins by solving processing, shelf life, and labeling trade-offs for industrial customers.
Recent strategic moves underline these dynamics and signal where momentum lies:
-
Strategic consolidation in Europe: A notable acquisition completed in 2025 transferred a portfolio of European margarines and production assets to a regional player, reinforcing the thesis that scale plus local brand equity is a defendable strategy in mature markets.
-
Product-led democratization: Brand launches aimed at affordability and micro-/small-food enterprises indicate a two-track growth approach — premiumization coexisting with economy packs targeting volume-seeking customers.
-
Functional differentiation: New launches introduced enriched and flavored variants, reflecting continued demand for marginal innovation that commands price premiums without requiring radical manufacturing changes.
What PW Consulting’s report delivers — practical outputs for 2026 planning
The full Margarine Market study is structured to convert insight into action. Key deliverables that inform strategic planning include:
-
Market sizing and seven-year forecast (2026–2032) with scenario variants reflecting oil-price stress, regulatory tightening, and demand elasticity assumptions. These scenarios enable CFOs to run stress tests against realistic upside/downside cases.
-
Go-to-market playbooks for retail, industrial, and bakery channels: SKU rationalization frameworks, pricing ladders, and co-packing models tailored to margin maximization and shelf-space economics.
-
Supply‑chain and procurement playbook: Supplier segmentation, dual-sourcing templates, and a hedging matrix designed to reduce earnings volatility tied to vegetable-oil swings.
-
Regulatory compliance checklist and sourcing roadmap: Practical steps to align formulations and traceability systems with emerging due-diligence regimes, including a compliance implementation timeline keyed to 2026 deadlines.
-
M&A and partnership heatmap: Target archetypes (asset deals, bolt-on brand acquisitions, and tolling arrangements), valuation multiples observed in recent transactions, and integration playbooks that protect margin and retain customer relationships.
-
Product innovation pipeline: Short- and medium-term R&D priorities, cost-to-implement estimates, and projected payback periods for common reformulation and premiumization initiatives.
How strategic leaders should use this intelligence in 2026
-
Make procurement a board agenda item. Elevated input risk plus regulatory compliance demands mean procurement decisions will have outsized P&L and reputational impact this year.
-
Prioritize SKU portfolio simplification in industrial channels while selectively expanding consumer-facing innovation in markets where premium spreads can be defended by brand and claims.
-
Accelerate traceability projects. Even modest upfront investment in supplier digitalization and certification will pay dividends as buyers and regulators pre-qualify suppliers on documented low‑risk sourcing.
-
Use M&A strategically to buy either processing scale in constrained geographies or branded access to retail channels where organic growth is slow and shelf space is highly contested.
-
Model multiple cost scenarios when setting 2026 prices — include a mid-case based on our 2.1% CAGR baseline and two stress cases that reflect higher input-price shocks and accelerated substitution trends.
Why this preview and why now
The margarine market in 2026 is not a high-growth, headline-grabbing sector, but it is strategically rich. Predictable top-line growth provides a stable platform for operational excellence, while input and regulatory pressures create asymmetries that well-prepared firms can exploit. Our study is designed to move beyond descriptive analysis and provide the prescriptive tools procurement, R&D, commercial, and corporate development teams need to convert modest market growth into outsized returns.
Next steps — how to access the full strategic playbook
This article highlights the report’s strategic value and the principal themes any executive team must address in 2026. The full PW Consulting Margarine Market study contains the granular segment-level analyses, regional scenarios, channel economics, and a prioritized implementation roadmap that we intentionally do not reproduce here. For licensing access, tailored executive briefings, or to commission a customized scenario modeled on your asset and customer footprint, please visit our report page or contact our industry desk.
For detailed analysis of this topic, please visit the official page: Margarine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com