

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Brake Pads Market to Reach USD 5.2 Billion by 2032 — 5.0% CAGR: PW Consulting Insight

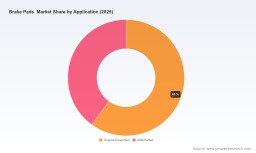
Brake Pads Market: Strategic Imperatives for 2026
As competitors, regulators, and original-equipment manufacturers (OEMs) recalibrate their strategies for the post‑pandemic automotive landscape, brake pads remain a deceptively strategic product category. At first glance the market is mature and commoditized; beneath the surface, however, evolving regulation, material science, and platform transitions are reshaping cost structures, distribution economics, and product roadmaps. This briefing summarizes the strategic value of PW Consulting’s Brake Pads Market research for board-level and executive decision-making in 2026, and highlights the practical actions the full study enables. For commercial reasons we intentionally withhold granular regional and application splits here; the full report contains those tables and downloadable datasets.
Brake Pads Market
Market trajectory and headline economics
Using 2025 as the base year, the global brake pads market has expanded steadily over the past half‑decade and is projected to continue on a moderate growth path through 2032. Our topline model shows the market growing from the low‑single‑digit billions in 2020 to approximately USD 3.8 Billion in 2025, with a steady compound annual growth rate of roughly 5.0% into the 2026–2032 forecast horizon and an expected market size exceeding USD 5 Billion by 2032. These aggregated dynamics mask important inflection points—regulatory compliance costs, raw‑material pricing differentials, and platform shifts tied to electrification—that will materially influence margins and capital allocation decisions in 2026 and beyond.
Brake Pads Market
Regulatory forces and material constraints
-
Copper and heavy‑metal restrictions have moved from policy proposals to enforceable standards in multiple jurisdictions. States such as California and Washington have established sub‑0.5% copper thresholds for brake pads, with certification and marking requirements already in force. The U.S. EPA’s copper‑reduction initiatives similarly raise compliance and traceability demands for suppliers and distributors.
Brake Pads Market -
These regulatory constraints are not purely compliance costs. They alter product design (alternative friction formulations), testing regimes (proof marking and certification), and supply chain complexity (sourcing of specialized binders and friction modifiers). Companies that anticipated the compliance curve enjoy first‑mover cost advantages; others face retrofit expenses and catalog relabeling costs.
-
Material and labor economics compound the picture. Ceramic formulations command a premium because of costlier friction modifiers and binders, while high‑precision manufacturing—especially where certification and low‑dust, low‑noise properties are required—drives up labor content. North American facilities, in particular, report higher unit labor costs tied to stringent quality controls and auditing processes.
Competitive landscape: positioning and strategic moves
The brake pads market presents a mix of global OEM suppliers, specialist niche players, and large aftermarket consolidators. Market concentration at the top remains modest—an indicator of continued fragmentation and opportunity for scale plays. Below we synthesize company positioning and strategic implications for 2026 planning.
-
Brembo S.p.A. (Italy) continues to lead with premium performance and fleet‑oriented severe‑duty lines. Brembo’s product architecture—covering ceramic, sintered, and metallic compounds—targets both high‑performance OEM fitment and specialized fleet requirements. Their recent Severe Duty launch underscores a deliberate move to capture high‑load commercial applications where durability and regulatory compliance are value drivers.
-
Akebono Brake Industry (Japan) has leveraged ceramic expertise and low‑copper formulations to strengthen OEM and aftermarket positions across Asia and North America. Their ProACT and Severe Duty portfolios reflect a strategy of marrying performance with regulatory alignment—an imperative in markets enforcing copper limits.
-
MAT Holdings / Bendix (USA) and other large North American players focus on broad aftermarket coverage and value‑added lines (e.g., QuietCast). Their scale in distribution and catalog breadth is a defensive moat, but margin pressure from raw‑material inflation and certification costs requires product mix optimization.
-
Robert Bosch GmbH and ZF Friedrichshafen (TRW) (Germany) combine OE know‑how with aftermarket branding. Both emphasize low‑noise/low‑dust ceramic solutions and have initiated copper‑free or reduced‑copper formulations, including offerings tailored to hybrid and electric vehicle drivetrains.
-
Textar (TMD Friction) , Continental (ATE) , Knorr‑Bremse , and Nisshinbo retain strong European and OEM coverage with deep intellectual property in friction material science—assets that can be monetized via licensing or co‑development partnerships.
-
Müller Brakes America , Brake Parts Inc. , and specialist performance brands such as EBC Brakes exploit niches—performance, heavy‑duty, and specialty two‑wheel segments—where formulation and compound differentiation justify premium pricing.
-
Hitachi Astemo illustrates the integrated systems play, supplying pads as part of broader brake module and safety system offerings—an increasingly attractive value proposition for OEMs integrating active safety and ADAS functionality.
Recent market signals
-
New product introductions and range extensions in 2025–2026 show manufacturers are prioritizing coverage, compliance, and specialty use cases. Examples include broad portfolio expansions by aftermarket players and Brembo’s Severe Duty line aimed at fleet/high‑load scenarios.
-
Volume plays continue: some regional distributors released hundreds of new SKUs in 2026 to expand coverage and capture replacement demand across older vehicle parc segments.
-
Two parallel trends are apparent: consolidation of SKU coverage to reduce stocking complexity, and targeted premium launches that defend margin against raw‑material inflation.
Market structure: fragmentation and opportunity
The market exhibits moderate concentration at the top and a long tail of regional specialists. That structure has three strategic consequences:
-
Margin expansion is achievable through premiumization (ceramic, severe‑duty formulations) and compliance‑driven product upgrades, but these strategies require upfront R&D and certification investment.
-
Scale in distribution—catalog depth and fulfillment reach—remains a durable competitive advantage in aftermarket channels; digital cataloging and coverage accuracy are differentiators in B2B procurement.
-
M&A remains an actionable lever for buyers seeking rapid entry into low‑copper formulations, geographic coverage, or technical IP. Selective consolidation can unlock procurement synergies and accelerate compliance roadmaps.
What the PW Consulting Brake Pads Market report delivers (practical contents)
-
Top‑down and bottom‑up market sizing with year‑by‑year historicals (2020–2025) and deterministic forecast model (2026–2032) usable in corporate planning systems.
-
Regulatory compliance roadmap detailing jurisdictional timing, certification requirements, and an estimated cost curve for reformulation and proof marking.
-
Competitive heatmap and supplier scorecards covering product portfolios, technical strengths, go‑to‑market models, and partnership opportunities.
-
Raw‑material sensitivity analysis assessing the impact of ceramic‑price swings, binder costs, and labor variance on unit economics.
-
Channel economics and aftermarket distribution playbooks, including SKU rationalization approaches and inventory reduction levers.
-
M&A target shortlist and valuation framework focused on technology, coverage gaps, and regional distribution assets (note: detailed target valuations are contained in the full report).
-
Three scenario plans (baseline, high‑regulation, and accelerated electrification) that translate market trajectories into capex, inventory, and margin implications for 2026 planning cycles.
Priority strategic moves for 2026
-
Adopt a compliance‑first product roadmap: prioritize certification for low‑copper formulations in markets with active regulation and implement traceability systems to avoid distribution interruptions.
-
Segment product architecture by value capture: preserve semi‑metallic cost leadership in price‑sensitive channels while expanding high‑margin ceramic and severe‑duty ranges where technical differentiation is defensible.
-
Invest in catalog accuracy and digital bilateral integration with distributors and OEMs to reduce returns, improve fill rates, and accelerate conversion of aftermarket customers.
-
Pursue targeted M&A or JV activity to secure IP, low‑copper compound capabilities, or regional distribution footholds rather than broad horizontal roll‑ups.
-
Manage procurement through long‑term supply agreements for binders and friction modifiers, and consider dual‑sourcing strategies to mitigate single‑supplier exposure.
-
Develop workforce upskilling programs focused on quality assurance and certification testing to lower rework rates and maintain margin integrity in high‑precision facilities.
Why this matters for 2026 decision cycles
CEOs and heads of strategy must treat brake pads not as a static commodity line but as a node where regulation, materials innovation, and distribution economics converge. Decisions made in 2026—on R&D prioritization, certification investment, and distribution sourcing—will determine who captures the premium pockets of growth identified in our forecast and who will see margin compression as compliance costs bite. The aggregated market growth of about 5.0% CAGR masks both upside pockets and downside exposure; navigating that variance requires the market‑level granularity and scenario tooling contained in the full PW Consulting study.
Next steps
To access the full data tables, company scorecards, regional and application splits, and downloadable forecast models that support capital allocation and M&A screening, consult the PW Consulting Brake Pads Market report page. The full deliverable converts the strategic imperatives summarized here into executable 12‑ and 36‑month plans, tailored to supplier, distributor, and private‑equity buyer use cases.
For detailed analysis of this topic, please visit the official page: Brake Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com