

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low-Density SLC NAND Market to Hit USD 2.12B by 2032 at 5.3% CAGR

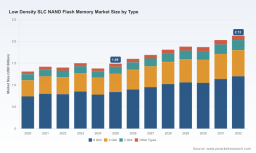
Low Density SLC NAND Flash Memory Market: Strategic Outlook for 2026 Decision-Making
Executive teaser
As hardware roadmaps converge toward resilient, long-life, and deterministic storage for mission-critical embedded systems, Low Density SLC NAND occupies a distinct strategic niche. PW Consulting’s new market study — anchored in a 2025 base year and extending through a 2026–2032 forecast window — synthesizes demand trajectories, supplier economics, regulatory risk and practical procurement playbooks to help executives make confident, time-sensitive decisions in 2026. The market is modest but steady: base-year revenue in 2025 stood at approximately USD 1.49 Billion, and our forecasts indicate a compound annual growth rate (CAGR) of roughly 5.3%, arriving at an anticipated market size near USD 2.12 Billion by 2032. This report is designed as a decision-support instrument: deep enough to guide strategy, selective enough to prompt direct engagement for the proprietary granular tables and pricing curves that matter in contract negotiations.
Low Density SLC NAND Flash Memory Market
Why this matters for 2026 strategic planning
-
Timing of portfolio investments: With mid-single-digit CAGR, low-density SLC remains a specialty segment rather than a volume-driven commodity. Firms deciding whether to invest in SLC-focused production lines, design-in resources, or long-term supply agreements must evaluate the trade-off between higher per-unit margins and constrained market scale.
Low Density SLC NAND Flash Memory Market -
Mission-critical differentiation: Applications that demand extremely high endurance, wide-temperature operation, or radiation tolerance (for aerospace, industrial control, and certain automotive code-storage functions) continue to prefer SLC. Companies that make 2026 product and qualification choices based on lifetime-cost models will find SLC strategically relevant despite its smaller absolute scale.
Low Density SLC NAND Flash Memory Market -
Procurement and contract timing: Volatility in wafer pricing and earlier 2025 price hikes require procurement teams to adopt shorter price-review cycles, stricter escalation clauses, and inventory buffering strategies. The report maps trigger points for renegotiation and provides model clauses for multi-year supply contracts.
Market trajectory — what the headline numbers conceal
The headline CAGR and end-point projection do not capture heterogeneity across use-cases, endurance classes, or temperature-rated variants. Our analysis layers product-class dynamics (e.g., small-form, legacy-process SLC devices vs. radiation-tolerant, mission-grade SLC) onto the macro trajectory, revealing pockets of higher-than-average growth potential driven by aerospace, autonomous systems, and industrial safety applications. The market’s structure also shows a moderate level of supplier concentration: the top three vendors account for roughly 48.7% of revenue, while the top five approach 61.0%. Those concentration metrics have direct implications for supplier risk and bargaining power in 2026.
Dynamics shaping near-term outcomes
-
Raw material & pricing shocks: In 2025 several major NAND suppliers announced price increases exceeding 10%, and spot wafer prices spiked into the double-digit percent range in late 2025. Those moves materially affect BOM economics for embedded systems and compress margin for OEMs that can’t pass increases through to end customers.
-
Regulatory & export controls: Heightened export controls from the U.S. on advanced semiconductor manufacturing and restrictions on select suppliers introduce non-price risk into supply planning. For firms with China-exposed manufacturing or sourcing, alternate qualification paths and local-content rework are pragmatic considerations for 2026 product roadmaps.
-
Geopolitics & tariffs: Escalating trade tensions and newly introduced tariffs on certain regional imports have raised effective landed costs for semiconductor components. Scenario planning in the report simulates tariff-imposed cost cliffs and recommends hedging approaches, including localized second-source strategies and bonded-warehouse use.
-
Supply chain tightness: Spot market dynamics and wafer-price increases create windows where procurement agility — not just scale — determines access to prioritized allocations. Our tactical guidebook for 2026 describes trigger-based inventory and allocation playbooks that minimize capital lock-up while preserving supply resilience.
Competitive landscape — what to monitor in 2026
The Low Density SLC segment is populated by established memory specialists and regional players. Our competitive deep-dive profiles technology, package-level differentiation, and go-to-market motion for each major supplier to support sourcing and partnership decisions.
-
Micron Technology, Inc. — Boise-headquartered Micron has emphasized high-end SLC with exceptional program/erase endurance (up to 100k cycles) and introduced radiation-tolerant variants aimed at space and defense markets. Their positioning signals continued emphasis on mission-critical systems where longevity and radiation-hardening matter most.
-
KIOXIA Corporation — With legacy-process SLC components and industrial-temperature packages, KIOXIA plays to established embedded and industrial code-storage applications. Their product breadth across classic density nodes supports legacy-system replacements and controlled migrations.
-
Winbond Electronics Corporation — Winbond’s ONFi-compliant and HQ serial variants, with extended temperature ratings and automotive/industrial certifications, position them as a pragmatic supplier for harsh-environment and safety-related deployments.
-
Macronix International — Macronix’s parallel and low-voltage SLC offerings remain widely used for firmware and boot storage. Their long-standing ONFi support eases integration into existing board-level designs.
-
Alliance Memory — Focused on serial and parallel SLC with wide temperature support and QSPI options, Alliance targets embedded/IoT device makers seeking compact form factors and rapid access times.
-
GigaDevice Semiconductor — As a regionally significant supplier, GigaDevice supplies cost-effective low-density SLC for industrial and code-storage applications. Their presence is particularly relevant for procurement teams balancing cost and qualification timelines.
Notable recent moves: Micron launched a radiation-tolerant SLC portfolio aimed at space systems in July 2025, and Winbond updated its SLC product brief with ONFi-compliant devices for automotive code storage in September 2025. These product-level developments signal where R&D and customer focus are accelerating.
Practical contents of the PW Consulting report
This market study is intentionally operational. Clients will find the following deliverables that translate directly into 2026 actions:
-
Executive dashboard with headline sizing, CAGR, and supplier concentration metrics, plus scenario-mapped demand curves under alternative geopolitical and pricing states.
-
Segment taxonomies and technology-readiness matrices (product types, temperature grades, endurance classes), with qualification timelines and recommended design-win strategies for each class.
-
Supplier scorecards including technical fit, capacity outlook, contractual red flags, and supplier financial resilience indicators; an M&A watchlist and partner-fit map are included for corporate development teams.
-
Procurement playbook: model contracts, inventory triggers, price-escalation clause templates, and negotiation tactics calibrated to wafer-price volatility and tariff scenarios.
-
Use-case ROI and TCO models: comparative lifetime-cost analyses (SLC vs. alternatives) for selected mission-critical applications supported by sensitivity testing for price and endurance assumptions.
-
Risk register and mitigation matrix covering material price shocks, export-control impacts, single-source failure, and certification/qualification cliffs for automotive and aerospace segments.
-
Implementation roadmap for engineering, procurement and compliance teams to align product qualification, supply strategy, and commercial contracts through the 2026 planning horizon.
Actionable recommendations for 2026
-
Prioritize qualification of at least two suppliers for any long-life SLC use; concentration metrics imply non-trivial single-supplier risk in a market where a few vendors command significant share.
-
Adopt dynamic pricing clauses with transparent pass-through mechanisms tied to wafer-price indices and documented raw-material adjustments to avoid margin erosion when spot costs rise.
-
For space/aerospace and high-reliability industrial designs, favor vendors with demonstrated radiation-tolerant portfolios and high P/E-cycle products, and budget for longer qualification windows.
-
Regionalize supply where tariffs and export controls materially alter landed cost or introduce compliance risk; use bonded-warehousing and local-qualification strategies to preserve market access.
-
Monitor supplier product briefs and roadmap announcements closely — product launches and spec-updates (such as those observed in mid/late 2025) are leading indicators of where lead times and allocation pressure will concentrate.
Methodology & limits — why you’ll want the full dataset
Our base-year is 2025, with historical coverage from 2020–2025 and forecasting to 2032. The forecast uses a hybrid approach blending bottom-up device demand modeling, supplier capacity reads, and scenario-based macro overlays for pricing and geopolitics. To preserve the commercial value of our proprietary analysis and the confidentiality of some supplier-reported figures, granular subsegment tables (including device-level market shares, region-by-application splits, and explicit price curves) are redacted from this public summary. These withheld elements are the decision-grade inputs procurement and product teams need to execute on the recommendations above.
Next step
For procurement directors, product leaders, and corporate strategists preparing 2026 plans, PW Consulting’s full Low Density SLC NAND Flash Memory Market report provides the actionable tables, contract language, and supplier risk heatmaps required to move from strategy to execution. Access to the complete dataset and the supplier-model spreadsheet is available through our report portal; these proprietary materials contain the granular breakouts that underpin the executive recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Low Density SLC NAND Flash Memory Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com