

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Perfluoropolyethers Market Set to Grow at 5.85% CAGR to 2032

Perfluoropolyethers Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As companies set budgets and capital allocations for 2026, the perfluoropolyethers (PFPE) market is at an inflection point that demands high-fidelity strategic judgement. This briefing summarizes the strategic value of our full PW Consulting market study and outlines the decision levers senior leaders should consider before committing to investment, sourcing, or M&A moves. We present data-driven context — including market scale and growth trajectory — while preserving the detailed segment analytics and proprietary tables that drive deal-level decisions for subscribing clients.
Perfluoropolyethers Market
Market at a glance: what the macro picture tells you
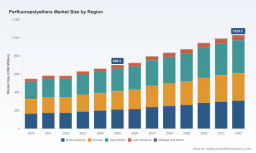
PFPEs are a specialized class of performance fluids and greases used when extreme chemical and thermal stability, dielectric properties, and long life are required. At the macro level, the market reached approximately USD 699 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 forecast horizon, approaching roughly USD 1.03 billion by 2032. That steady expansion masks important structural characteristics — a mix of high-performance demand from capital goods industries and a supply side that is concentrated and technically gated — which should shape any near‑term strategic plan.
Perfluoropolyethers Market
Why this research matters for 2026 decision cycles
- Regulatory inflection points: PFPEs have been the focus of intensified regulatory analysis and market surveillance across jurisdictions. Key recent developments include inclusion on U.S. EPA SNAP program lists and new EU measures on substance surveillance that change compliance costs and market access dynamics.
- Concentrated supplier power: Top-tier manufacturers account for the majority of available commercial product, creating bargaining asymmetries and higher thresholds for new entrants. Our analysis shows industry concentration levels that materially affect pricing elasticity and contract design.
- Data scarcity and confidentiality: Official production volumes are often reported as confidential business data, complicating traditional supply/demand estimation. Our methodology reconciles primary interviews, proprietary shipment proxies, and policy signals to produce defensible forecasts.
- Environmental monitoring and reputational risk: Recent provenance and environmental monitoring activities tied to established producers have elevated due‑diligence requirements for downstream buyers, especially in regulated end-markets.
What the PW Consulting study delivers — practical, decision-ready content
- Robust market sizing and forecasting model (base year 2025; historical run 2020–2025; forward view 2026–2032) with scenario toggles for regulatory tightening and raw material volatility.
- Segmentation frameworks across type, end-use and geography — including demand drivers, substitution risk, and technology readiness — presented as decision matrices rather than raw tables (full split detail available in the full report).
- Supplier and capacity mapping that highlights choke‑points, proprietary chemistries, and third-party tolling risk.
- Regulatory impact matrix that quantifies compliance cost scenarios and market access timelines tied to recent public policy moves.
- Competitive benchmarking and playbooks: company profiles, product positioning, channel strategies, and after-sales/service differentiation to inform sourcing and JV/M&A strategies.
- Practical tools: investment threshold calculators, supplier scorecards, contracting templates with performance and compliance clauses, and an executive dashboard for board-level briefings.
Key market dynamics to factor into 2026 strategy
- End‑market sensitivity and asymmetric demand growth — PFPE demand is decoupled from general industrial expansion. Gains are concentrated in applications needing long-life lubrication, extreme temperature stability, or unique dielectric performance. These pockets will drive premiumization even as overall growth remains mid-single digits.
- Regulatory and market surveillance are accelerating — the U.S. EPA’s SNAPS program has explicitly listed PFPEs for certain acceptable substitutes with conditions, and the EU’s Regulation 2024/590 raises the bar for market surveillance and customs controls, changing time-to-market assumptions for product introductions.
- Supply opacity increases strategic risk — the OECD notes confidentiality in production reporting, and that opacity intensifies the value of proprietary supplier intelligence and multi‑sourcing strategies. Firms without direct intelligence runs the risk of being surprised by capacity constraints or product delisting.
- Reputational and environmental monitoring — recent certified reference material initiatives and environmental studies tied to established producers mean buyers must incorporate provenance and lifecycle reporting into supplier selection to avoid regulatory and reputational hits.
- Consolidation and vertical play — high technical entry barriers favor incumbents and create opportunities for forward integration by downstream players seeking to secure specialized supply or differentiate through service and formulation.
Competitive landscape — how the key players are positioning
The competitive field is dominated by established specialty-chemicals and lubrication players that combine proprietary chemistries, patented formulations and global service networks. Market concentration is meaningful: the top three suppliers hold a commanding portion of available commercial product, and the top five further consolidate access and pricing power. This structure favors strategic incumbency, scale-enabled R&D, and service differentiation.
Perfluoropolyethers Market
- Daikin Industries Ltd. (Osaka, Japan): Known for Demnum PFPE fluids and lubricants, Daikin leverages integrated manufacturing and long-term OEM relationships. Their competitive edge is product consistency and breadth of industrial channel access.
- The Chemours Company (Wilmington, DE, USA): Krytox is positioned as a premium PFPE lubricant brand targeting high-specification applications. Chemours emphasizes performance benchmarking and aftermarket availability for critical assets.
- DuPont de Nemours, Inc. (Wilmington, DE, USA): With MOLYKOTE PFPE-based lubricants, DuPont combines formulation expertise with global distribution channels particularly strong in electronics and industrial maintenance markets.
- Solvay S.A. (Brussels, Belgium): As a producer of Fomblin PFPE fluids, Solvay operates at the intersection of specialty polymer production and regulatory visibility. Recent regulatory compliance and environmental monitoring activities have placed broader scrutiny on regional production footprints.
- Klüber Lubrication (Munich, Germany): Offers branded PFPE oils and greases with a heavy emphasis on engineered solutions and service agreements, appealing to OEMs seeking lifecycle support over commodity supply.
- Nye Lubricants Inc. (Fairhaven, MA, USA): A niche specialist with Uniflor PFPE products, Nye competes on tailored formulations and rapid technical support for precision industries.
- Fuzhou Topda New Material Co., Ltd. (Fuzhou, China) and Anhui Sinograce Chemical Co., Ltd. (Anhui, China): Regional suppliers that provide cost-competitive PFPE products and PFPE-derived solutions for coatings; they are increasingly relevant for buyers seeking cost‑effective alternatives and local sourcing.
Recent developments that change the playbook
- Regulatory & compliance: In 2024, parts of the PFPE chain were incorporated into enhanced surveillance programs, including actions that affect market surveillance and customs controls — a factor that lengthens qualification timelines.
- Monitoring & reference materials: Solvay‑linked initiatives for certified reference materials and local environmental studies have created new transparency vectors but also added potential liabilities for manufacturers and users.
- Industry reporting gaps: Multilateral assessments emphasize that production data is often kept confidential, making primary‑research intelligence and supplier access indispensable for credible commercial planning.
Strategic playbook for 2026 decision-makers
- Adopt a regulation-first product and sourcing strategy. Build regulatory scenarios into NPV and payback models (fast/slow/no-action scenarios) and require suppliers to demonstrate compliance roadmaps as a condition of award.
- Prioritize supplier resilience over lowest-first-cost. Given concentration and opaque production reporting, dual‑sourcing or contractual capacity reservations may be superior to spot procurement savings.
- Invest in formulation & co‑development where feasible. OEMs and specialty users should evaluate partnerships or minority equity to lock technology access and accelerate qualified supply for critical programs.
- Use the CAGR window tactically. With a mid‑single digit expansion path, target investments with clear three- to five-year payback windows and prioritize initiatives that secure margin improvement rather than chasing share in lower-margin pockets.
- Elevate lifecycle compliance and traceability as commercial differentiators. Companies that can offer documented provenance, lifecycle assessment, and regulatory support will command premium positioning in regulated end markets.
- Prepare M&A and bolt-on playbooks focused on capacity, IP, and aftermarket services. Target assets that reduce reliance on single-source proprietary chemistries or expand serviceable aftermarket footprints.
Practical next steps & risk checklist
- Immediate: Run a supplier risk audit that maps single points of failure in PFPE supply and includes compliance certifications and substitute readiness.
- Short-term: Conduct a scenario valuation of key programs using PW Consulting’s forecast model (available with subscription) to identify which product lines merit accelerated capex.
- Medium-term: Negotiate structured supply agreements with performance and compliance KPIs; include price‑indexation and transition plans for regulatory shifts.
- Risk checklist: regulatory non-compliance, supplier concentration, raw-material price shocks, environmental monitoring liabilities, and technology obsolescence.
Conclusion — The PW Consulting PFPE study is designed to be a tactical instrument for 2026 planning cycles. It converts opaque market signals into operational triggers: when to hedge, when to invest, and when to consolidate. For executives looking to convert market growth into durable economic advantage, our full report supplies the withheld segment tables, regional splits, interactive forecast model, and supplier scorecards necessary to move from intent to action.
To access the detailed segmentation, proprietary scenario models, and supplier matrices referenced here, please visit PW Consulting’s Perfluoropolyethers Market report page or contact your client representative for the subscriber pack and workbook.
For detailed analysis of this topic, please visit the official page: Perfluoropolyethers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com