

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fiber Optic Cables Market to Hit USD 19.33B by 2032 at 9.94% CAGR

Fiber Optic Cables Market 2026: Strategic Imperatives for Executive Decision-Making
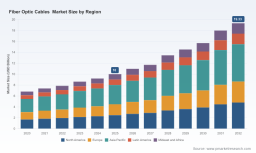
As global connectivity demands accelerate, the fiber optic cables market is re-entering a phase of structural expansion and strategic complexity. PW Consulting’s latest industry study—anchored on a 2025 base year and extending through 2032—shows that the market has expanded from roughly USD 6.8 billion in 2020 to about USD 10.0 billion in 2025 and is projected to approach USD 19.3 billion by 2032 under a compounded growth trajectory (CAGR ~9.94% across the forecast window). For corporate leaders planning capital allocation, supply-chain resilience, or M&A in 2026, these headline figures are not abstract; they define timing windows, margin pressure points, and the scale of operational response required.
Fiber Optic Cables Market
Why this research matters for 2026 corporate strategy
- Timing of capacity investments: The market’s near-term acceleration—evident in the step-up from 2020–2025 baseline to the forecasted growth path—means firms that front-load selective capacity (or secure long-lead inputs) can capture premium tender activity with superior margins. Conversely, late entrants risk higher procurement costs and longer lead times as raw-material scarcity periodically emerges.
- Procurement and raw-material risk: Tightness in preform availability and volatility in quartz and cable-grade input markets have already pressured prices and lead times in early 2026. Procurement teams need decision-ready hedging and supplier-diversification playbooks rather than ad-hoc spot buying.
- Regulatory and sustainability compliance: Carbon and border-adjustment mechanisms are real levers of cost and access. Firms that map carbon intensity into pricing and contract terms will avoid margin erosion and regulatory surprises.
- Product and go-to-market differentiation: Demand is bifurcating—hyperscale data centers and AI workloads are driving capacity and performance requirements, while broadband and 5G backhaul continue to push reach and robustness. Product roadmaps must be calibrated to both high-volume, cost-sensitive deployments and high-performance, higher-margin segments.
What PW Consulting’s report delivers—practical outputs for executives
Our full report is deliberately designed as an operational guide for 2026 decision cycles. High-value deliverables include:
Fiber Optic Cables Market
- Robust market-size model with annual historicals (2020–2025) and a seven-year forecast (2026–2032), including scenario variants that stress-test demand under alternative AI, 5G, and FTTH roll-out assumptions.
- Supply-chain heatmaps identifying single-source vulnerabilities, critical lead-time drivers, and node-level concentration risks—built to support sourcing and inventory strategy workshops.
- Raw-material and unit-cost modeling (including sensitivity to quartz and cable-component pricing and an installation-labor cost ladder) to enable commercial teams to build defensible price escalators into long-term contracts.
- Vendor scorecards and a proprietary supplier-risk index that combine capability, capacity, geographic diversification, ESG credentials, and delivery performance—designed for procurement RFP shortlisting and preferred-supplier governance.
- Commercial playbooks for pricing, terms, and performance guarantees tailored for hyperscale, telco, and enterprise channels—each with negotiation scripts and contractual clauses to mitigate late-delivery exposure.
- Investment decision tools for CapEx sizing, payback analysis, and threshold triggers for greenfield capacity or vertical integration (preform and optical-fiber manufacturing).
Note: This preview intentionally omits granular regional and application breakdowns and company-level score-card data. Those are available in the full PW Consulting package, which includes interactive models and downloadable templates for executive use.
Fiber Optic Cables Market
Competitive landscape: what incumbent moves tell us
The competitive set is composed of diversified incumbents and regional specialists. Several strategic patterns are evident from recent company moves and product innovations:
- R&D and product differentiation are central: Long-standing technology leaders continue to invest in low-loss fibers and specialized multi-core solutions to service hyperscale and sensing applications. Partnerships between manufacturers and academic institutions are being used to accelerate next-generation fiber formats and distributed sensing capabilities.
- Sustainability and certification as barriers to entry: Investments in cleaner processing and reduced solvent use are serving dual objectives—cost reduction and regulatory compliance—creating switching costs for buyers sensitive to carbon penalties and procurement rules.
- Focused product launches address niche installation pain points: Bend-insensitive multimode fibers, low-smoke zero-halogen (LSZH) constructions for transit hubs, and multi-core fibers with embedded sensing are examples of tactical product plays designed to win specific project categories.
- Scale and integration remain decisive: Firms with upstream control of preform and fiber production, or with broad cable-systems expertise (including submarine assemblies), have superior leverage in pricing and delivery for large-scale, cross-border projects.
Representative strategic profiles (high-level):
- Corning Incorporated —deep IP in low-loss fiber and a strong footprint in single- and multi-mode fibers for hyperscale and telecom customers; excels at technology diffusion into high-volume applications.
- Prysmian Group —horizontal systems capability, including submarine and long-haul backhaul, positioning it well where integrated cable-systems expertise is a procurement requirement.
- Nexans —leveraging high-count cable solutions and recent environmental-certification wins to bid competitively on projects where sustainability and system integration are weighted factors.
- YOFC —large-scale upstream integration with capabilities across preform, fiber, and cable production; recent partnerships on multi-core fiber and sensing indicate a pivot to higher-value differentiated products.
- AFL Telecommunications —specialist in connectivity and assembly solutions that accelerate deployment timelines for hyperscale and broadband projects.
- Hengtong Group & ZTT —broad manufacturing portfolios and turnkey solutions that make them natural partners for large regional FTTH and submarine contracts; recent product introductions also target transit and tall-building installations.
Notable recent developments that matter to buyers and strategists: YOFC’s 2025 collaboration on multi-core fiber with embedded distributed acoustic sensing; Nexans’ 2025 ISO 14001 certification at a submarine plant tied to reduced water consumption and solvent elimination; product introductions focused on bend-insensitive multimode and LSZH constructions in 2025–2026. These moves reflect the twin priorities of product differentiation and regulatory compliance.
Key dynamics shaping price and supply in 2026
- Raw-material pressure: Cable-grade inputs and high-purity quartz pricing have historically exhibited wide bands; procurement teams should plan for episodic spikes and consider multi-year supply agreements with volume and indexation clauses.
- Regulatory overlay: Mechanisms like carbon border adjustments are reshaping landed costs and supplier selection. Buyers must evaluate total landed carbon-adjusted cost, not just ex-factory price.
- Demand concentration: Project waves—driven by hyperscale cloud expansions, AI workloads, and national broadband programs—tend to create short windows of intense procurement. Having pre-qualified suppliers and contract templates is a competitive advantage.
Recommended 2026 action plan for executives (prioritized)
- Secure strategic supply partnerships: Negotiate anchor agreements with tier-1 and regional suppliers, embedding price-adjustment formulas tied to transparent cost indices and lead-time SLAs.
- Invest selectively in upstream capacity or JV structures: Where your business model supports it, consider strategic capacity stakes in preform or fiber production to reduce exposure to input scarcity and capture margin uplift.
- Accelerate sustainability investments: Map your carbon footprint across the value chain and prepare for border-adjustment impacts by investing in cleaner process technologies and verified offsets or carbon-efficient suppliers.
- Differentiate product portfolios: Prioritize development or licensing of fibers and cable systems tailored to hyperscale/dense-lumen deployments and embedded sensing—where margin pools are deeper.
- Refine commercial contracts: Build in pass-through mechanisms, performance-based payment schedules, and accelerated remedies for late-delivery to mitigate risk during peak demand windows.
- Use the report’s scenario tools in board decisions: Establish trigger points—lead-time, input-cost, and demand thresholds—that guide when to shift from conservative to aggressive capacity or procurement postures.
How to apply the full report in Board and Procurement forums
Use the report as a decision-support kit: import the interactive forecasts into capital-allocation models, run supplier-risk simulations in procurement war-rooms, and adopt the provided contract templates and negotiation playbooks in sourcing RFx processes. The PW Consulting package is tailored to move quickly from insight to action: each strategic recommendation is accompanied by an implementation checklist and an estimated lead-time-to-impact metric.
Next step
The analysis above highlights the strategic contours for 2026 but intentionally omits the granular region-, type-, and application-level splits and vendor scorecards that underpin project-level choices. PW Consulting’s full report contains those segmented tables, downloadable models, and executable playbooks. For firms preparing procurement cycles, board reviews, or M&A screens in 2026, accessing the complete set of models and supplier diagnostics is the logical next step.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com