

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rollator Walker Market to reach USD 134.9M by 2032 at 5.8% CAGR

Rollator Walker Market 2026: Strategic Imperatives for Private Equity, Manufacturers and Health Systems
As demographic shifts, product innovation and reimbursement pressure reshape the mobility-aid landscape, 2026 is shaping up to be a pivotal year for executives and investors active in the rollator walker market. PW Consulting’s latest market study synthesizes five years of historical performance with a 2026–2032 forecast to convert industry noise into decision-ready intelligence. This executive introduction highlights the study’s strategic value for corporate planning while intentionally preserving the granular segment-level datapoints that underpin our proprietary models—access to which is available in the full report.
Rollator Walker Market
Market snapshot you can act on
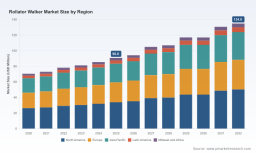
After steady growth through the early 2020s, the rollator walker market reached approximately USD 90.8 Million in our 2025 base year and is forecast to expand at a compound annual growth rate of 5.8% over the 2026–2032 horizon. Underlying this topline are durable secular drivers—aging populations in advanced markets, increased rehabilitation utilization after inpatient stays, and a faster migration to lightweight and premium materials—that together create both near-term margin compression risks and mid-term premiumization opportunities.
Rollator Walker Market
Why 2026 is strategically different
- Regulatory inflection: Medicare billing rules and assistive-device coding remain central to commercial viability in the largest purchaser cohorts. The Durable Medical Equipment (DME) reimbursement environment continues to favor clinically validated devices that can be aligned to existing billing pathways.
- Standards-driven differentiation: ISO 11199-2:2021 has become a de facto quality baseline. Manufacturers that integrate ISO-aligned testing into product design reduce commercial friction with institutional buyers and differentiate on safety and durability.
- Cost-to-serve pressure: Rising logistics and materials costs have accelerated SKU rationalization across suppliers—steel-frame SKUs are being phased out or re-engineered in favor of lightweight aluminum and carbon composites to manage per-unit logistics and customer appeal.
- Product innovation wave: Recent launches demonstrate two clear vectors—off-road, stability-focused designs for broader out-of-home mobility, and ultra-lightweight, carbon-aluminum hybrids for active users seeking portability without sacrificing support.
Strategic levers for decision-makers
For CEOs, private equity sponsors and commercial leaders, the report translates macro growth into executable options across five core levers.
Rollator Walker Market
- Portfolio prioritization: Differentiate between products that drive volume in institutional channels (e.g., durable, low-cost models) and those that enable margin expansion through premiumization (lightweight, carbon components, ergonomic seating). The right SKU set reduces service complexity and improves inventory turns.
- Channel reconfiguration: Institutional procurement, specialty retailers and direct-to-consumer channels each demand distinct commercial models. Our go-to-market maps identify where to deploy inside sales, clinical education teams, and e-commerce investments to optimize acquisition costs.
- Clinical evidence and reimbursement alignment: Devices that can be justified under existing clinical codes capture higher ASPs and lower resistance from payors. We map the clinical outcomes most persuasive to physiotherapists, occupational therapists and procurement committees.
- Supply-chain resilience: Material choices (aluminum vs. composites) and freight sensitivity should inform nearshoring or multi-sourcing strategies. Our scenario models quantify trade-offs between landed cost, weight-sensitive logistics and service lead times.
- M&A and partnership articulation: Rollator product lines can create attractive tuck-in opportunities for distributors or yield platform consolidation targets for strategic consolidators seeking scale in manufacturing, R&D and distribution.
Competitive landscape — who matters and why
The competitive fabric remains a mix of global incumbents, specialty European design houses and regional innovators. Rather than presenting market shares, PW Consulting’s analysis evaluates each firm against four strategic dimensions: product portfolio breadth, manufacturing footprint and materials capability, channel access (institutional vs. retail vs. direct), and clinical/reimbursement positioning.
- Drive Medical (Nashville, TN) — plays to breadth and scale with a portfolio that spans ultralight and performance-oriented rollators. Their product strategy balances mainstream hospital demand with higher-margin lifestyle models.
- Invacare Corporation (Elyria, OH) — legacy strength in bariatric and institutional models. Leadership here is in durability and broad channel penetration, particularly where regulatory and procurement cycles favor established suppliers.
- Bischoff & Bischoff GmbH (Germany) — a premium design-led competitor with successful collaborations that elevate perceived value (e.g., designer partnerships). Recent lightweight aluminum launches underscore a move to combine lifestyle appeal with practical functionality.
- Trionic Sverige AB (Uppsala, Sweden) — differentiated by off-road and ergonomics-focused designs. Their 2026 four-wheel walker introduction signals a focus on posture support and braking systems for active mobility use cases.
- Human Care HC AB (Sweden) — innovative cross-folding and portability design strengths, making the brand attractive in homecare and community mobility segments.
- Evolution Technologies Inc. (Canada), Karman Healthcare, Graham-Field and Nova Medical — represent a cluster of specialists driving incremental innovation around weight, braking systems and modular accessories for specific clinical or lifestyle subsegments.
Recent product launches in early 2026 illustrate how competitive advantage is increasingly built from engineering trade-offs rather than price alone: lightweight aluminum rollators with improved seating ergonomics, and four-wheel designs with responsive braking and posture support. These moves suggest an arms race along usability, perceived safety and premium materials rather than purely on price.
Regulatory and standards dynamics that shape strategy
- Reimbursement alignment: Manufacturers and distributors that map product claims and clinical data to established billing codes reduce cycle time to payer acceptance and accelerate institutional adoption.
- Standards compliance: ISO 11199-2:2021 compliance is table stakes for procurement teams in hospitals and long-term care facilities. Embedding standardized testing into product roadmaps reduces the cost of customer qualification.
- Procurement behavior: Large buyers increasingly adopt value-based procurement frameworks that weight lifecycle costs, clinical outcomes and safety—benefitting vendors who can demonstrate lower total cost of ownership (TCO).
Practical contents of the PW Consulting study
This report is built for operators and investors who must make 2026 capital allocation, go-to-market and product decisions. Key practical deliverables include:
- Top-down market sizing with scenario forecasts to 2032, including sensitivity to reimbursement shifts, raw-material price trajectories and channel migration.
- Demand- and supply-side unit economics: contribution-margin models by device archetype, SKU-level cost-of-goods with freight and aftermarket support overlays.
- Go-to-market playbooks for institutional, retail and direct channels—resource allocation, sales force sizing, and digital strategies tuned to adoption cycles.
- Clinical and reimbursement playbook mapping device features to claims and billing pathways to accelerate hospital and DME adoption.
- Comprehensive competitor dossiers: capability matrices, patent and design-intellectual-property analyses, recent product roadmaps, and scenario-based response strategies.
- M&A screening models and synergy calculators for tuck-ins and roll-ups, including integration-risk checklists and three-year synergy capture timelines.
- Operational scorecards and KPIs for manufacturing prioritization (weight vs. durability trade-offs), SKU rationalization, and after-sales service economics.
How to use this intelligence in 90 days
- CEOs: Prioritize one quick-win SKU rationalization and one medium-term premium product program. Use our TCO thresholds to de-risk pricing moves with major institutional customers.
- Private equity: Apply our M&A screening model to shortlist targets that deliver scale in distribution or that own design/IP assets enabling material-light rollators.
- Product leaders: Validate new materials and braking-system investments against our clinical-efficacy matrix before committing to tooling or supplier contracts.
- Commercial teams: Rebalance channel investments toward specialty retailers and digital D2C pilots where margin-accretive adoption curves are visible in our channel analysis.
Why PW Consulting’s study matters for 2026 decisions
We translate industry signal noise into prioritized, risk-weighted actions. The combination of an actionable forecast (anchored by a 2025 base), scenario-based cashflow impacts, and supplier- and channel-level playbooks gives decision-makers the capacity to shift from defensive inventory and cost plays to selective premiumization and targeted consolidation.
Importantly, this executive brief does not reproduce the full set of granular splits by region, device type or application that drive valuation and operational levers. Those segment-level tables, underlying models, and downloadable scenario workbooks are available in the full PW Consulting report and downloadable client kit—designed to be immediately used by strategy teams and transaction committees.
Next steps
If you are planning capital allocation, product roadmap shifts, or potential M&A activity in 2026, PW Consulting’s Rollator Walker Market study is the tactical intelligence you need to move from hypothesis to executable plan. The full report contains the segment breakout tables, scenario model access, and detailed competitor appendices required to run due diligence and build three-year operating plans.
Contact PW Consulting to obtain the full report and the accompanying modeling toolkit—our team will walk you through the specific modules most relevant to your corporate role and decision timetable.
For detailed analysis of this topic, please visit the official page: Rollator Walker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com