

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bead Wire Market to Reach USD 344.8M by 2032 at 6.98% CAGR

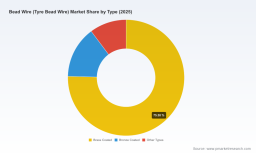
Bead Wire (Tyre Bead Wire) Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a concise, action-focused overview of the Bead Wire (Tyre Bead Wire) market that frames where executive choices in 2026 will yield disproportionate advantage. This narrative integrates the headline market dynamics — from historical sizing to a clear forecast trajectory — while deliberately reserving detailed segment-level tables and numerical breakdowns for the full report. Think of this piece as the strategic trailer: it proves we understand the market’s levers and inflection points, while directing your commercial and investment teams to the full study for execution-grade granularity.
Bead Wire (Tyre Bead Wire) Market
Headline market trajectory: sizing, growth, and what it implies
The bead wire market has moved from a modest baseline in 2020 to a materially larger industry by 2025, reflecting steady demand for tire reinforcement in both passenger and commercial vehicle segments. PW Consulting’s base-year assessment (2025) and modelled forecast to 2032 indicate a compound annual growth rate of approximately 6.98% through the forecast window. Under our baseline scenario, market value advances noticeably from 2025 into 2026 and continues to expand through 2032, driven by rising light-vehicle production, replacement tire volumes, and selective premiumization trends.
Bead Wire (Tyre Bead Wire) Market
For strategy teams, two quick implications follow: (1) market expansion is predictable enough to justify staged capacity and capability investments, and (2) growth concentrated in value-added coated and high-performance bead wire variants amplifies margin opportunities for market participants that can deliver consistent quality, regulatory compliance, and supply resilience.
Bead Wire (Tyre Bead Wire) Market
Why 2026 is a pivotal planning year
- Raw-material shock exposure : High-carbon steel wire rod accounts for the majority of bead wire production cost. Recent historical volatility — including a single-quarter price swing of nearly 28% in 2024 — shows material prices remain a dominant earnings risk. Procurement strategies that begin in 2026 will determine unit economics for several fiscal years.
- Regulatory and standards alignment : Global adoption of tensile and coating standards (e.g., ISO 6892-1 and ASTM A825) is tightening quality expectations. Companies that align product development, QA processes, and supplier audits to these standards now will avoid costly retrofits and qualification delays with OEMs.
- OEM demand signals : The global automotive production backdrop — including a projected increase in light-duty vehicle volumes — underpins predictable long-term demand. 2026 decisions on capacity, automation, or regional footprint will intersect with OEM sourcing cycles and should be synchronized accordingly.
What the full report delivers — practical, executable intelligence
PW Consulting’s Bead Wire market study is constructed for buyer-side and supplier-side leaders who need to translate market insight into executable plans. Highlights of the full deliverable include:
- Integrated market-sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario runs (base, downside, and upside) to stress-test capacity and revenue plans.
- Supply-chain heatmaps and raw-material exposure matrices that quantify sensitivity to wire-rod price moves and identify hedging and vertical-integration levers.
- Regulatory and standards impact assessment — mapping compliance requirements to product specifications and certification timelines for primary markets.
- Commercial playbooks for supplier selection, pricing architecture, and contractual protections (indexation clauses, minimum take-or-pay constructs, and quality SLAs).
- Technology and product roadmaps that prioritize coatings, polymer-hybrid innovations, and nickel/hybrid solutions — including implementation timelines, cost buckets, and margin uplift scenarios.
- Actionable M&A and CAPEX decision frameworks: acquisition target screening attributes, integration checklist, and break-even analyses for greenfield lines versus brownfield expansions.
- Benchmarking templates and supplier scorecards that accelerate vendor rationalization without sourcing disruptions.
Each module is designed to move teams from insight to decision — a short-list of prioritized moves for procurement, operations, R&D, and corporate development in 2026.
Competitive landscape — players, positioning, and strategic moves
The bead wire market remains commercially accessible to both regional specialists and globally integrated steel-wire manufacturers. Market concentration metrics show a relatively fragmented landscape, leaving room for scale and differentiation plays. Below, we summarize the strategic posture of leading participants featured in our competitive analysis.
- Bekaert (Belgium) — A technology-forward supplier with a portfolio of precision-engineered high-carbon bead wire. Their configurable diameters, tensile specifications, and multiple coating options position them well for OEMs demanding tightly-controlled mechanical properties and sustainable packaging. Bekaert’s engineering-first approach is an advantage in specifications-heavy premium tire programs.
- Rajratan Global Wire Ltd (India) — A high-volume, cost-competitive producer with substantial manufacturing capacity and an established footprint in South Asia and Southeast Asia. Rajratan’s scale, combined with a broad diameter range and presence across passenger, commercial, and two-wheeler tire segments, gives them strong price-competitive credentials for global and regional tire makers.
- Kiswire Ltd (South Korea) — Known for steel cord leadership, Kiswire brings advanced coating technologies (including nickel and polymer-hybrid approaches) into bead wire applications. Their R&D trajectory emphasises weight reduction and premium reinforcement technologies that appeal to high-performance tire programs and EV-oriented applications.
- Elsewedy Steel (Egypt) — Leveraging a dedicated bead wire production area and sustainability messaging, Elsewedy competes on quality and regional proximity for African, Middle Eastern, and Mediterranean markets. Their recent product showcases signal intent to engage top-tier tire manufacturers.
- Heico Wire Group (USA) — Operating as part of a broader metal processing portfolio, Heico brings flexible production and route-to-market advantages in North America, which can be decisive for just-in-time OEM supply chains.
- Aarti Steel International Limited (India) — A specialist wire producer with a focus on tailored tyre bead wire offerings; suitable for mid-market and regional tire manufacturers seeking a balance of cost and customization.
- Jiangsu Xingda Steel Tyre Cord Co., Ltd (China) — Integrated tyre cord and bead wire capacities with recent expansions; their proximity to large tire clusters and integrated supply chain can provide competitive logistics and lead-time dynamics to Asian tire makers.
Notable recent activity includes product showcases and trade-expo participation by several manufacturers, underlining a market push for differentiation through coatings, sustainability claims, and performance metrics. These tactical moves are early signals of competitive positioning to support new tire programs and premium applications.
Structural dynamics and risk factors
- Raw-material concentration risk — Given the outsized share of production cost attributable to high-carbon steel wire rod, companies that do not implement proactive procurement protections (long-term contracts, blended sourcing, or strategic inventories) will experience margin compression when spot prices spike.
- Standards-driven product requalification — Increasing alignment with tensile and coating standards raises the bar for new suppliers; time-to-qualification is a commercial gating item for OEM programs.
- Cost-to-performance trade-offs — Bead wire generally represents a single-digit percentage of total tire manufacturing costs, but minor composition or coating changes can materially affect tire reliability and performance. This creates a dual imperative: control cost without compromising specification compliance.
- Fragmentation and consolidation opportunity — Current concentration levels indicate both room for consolidation and for niche premium players to thrive. M&A strategies should balance scale benefits with the risk of integration complexity across geographies and product platforms.
Recommended 2026 playbook — prioritized actions
- Hedge and diversify raw-material exposure : Lock in a mix of indexed and fixed-price contracts in 2026, create tiered inventory thresholds, and evaluate upstream partnerships or minority stakes in wire-rod suppliers.
- Accelerate standards-compliance roadmaps : Invest in in-line quality instrumentation and independent certification pipelines so that new product variants can be qualified with OEMs within a single procurement cycle.
- Prioritize premium coatings and hybrid technologies : Reallocate incremental R&D and CAPEX towards higher-margin coated and polymer-hybrid solutions that serve EV and high-performance tire segments.
- Regionalize supply to match OEM footprints : Use a regional supply play where lead-time and inventory costs matter more than unit price — particularly for just-in-time programs in mature automotive clusters.
- Use the report’s M&A matrix : Target bolt-on acquisitions to fill capability gaps (coatings, surface treatment, sustainable packaging) rather than broad horizontal roll-ups that require deep integration.
Next step: where to find the full playbook
This overview surfaces the strategic inflection points we observe heading into 2026, and the decisions that will differentiate winners from laggards. For procurement directors, strategic-planning leads, and corporate development teams planning investments or supplier strategies next year, the full PW Consulting report provides the operational granularity you will need — including downloadable models, supplier scorecards, contract template clauses, and a prioritized action calendar tied to our forecast scenarios.
Accessing the complete study will equip teams to convert the directional hypotheses set out here into executable 90-, 180- and 360-day plans. Our full dataset includes the detailed segment splits, regional demand drivers, and per-variant economics that we intentionally omitted here to preserve the strategic trailer effect and to encourage direct engagement with the full source materials.
PW Consulting remains available to support tailored workshops, model customizations, and rapid due-diligence assignments for supply-chain reconfiguration or M&A activity in the bead wire value chain.
For detailed analysis of this topic, please visit the official page: Bead Wire (Tyre Bead Wire) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com