

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Ultra-low Temperature Freezers Market to grow at 5.1% CAGR through 2032
By pmarketresearch, 2026-07-13
Ultra-low Temperature Freezers Market: Strategic Outlook for Enterprise Decision-Making in 2026
As laboratories, biobanks, and biopharma facilities accelerate sample-centric strategies, ultra-low temperature (ULT) freezers have moved from commodity infrastructure to mission-critical capital assets. PW Consulting’s latest market study — base year 2025, forecast period 2026–2032 — maps that transition with quantitative rigor and operationally focused guidance. The global ULT freezer market reached approximately USD 683.2 Million in 2025 and is projected to grow at a compound annual growth rate of 5.1% through the forecast window, reaching roughly USD 959.5 Million by 2032. This study is designed to inform the high-stakes procurement, R&D prioritization, site-planning, and M&A choices your organization will make in 2026.
Ultra-low Temperature Freezers Market
Why this study matters for 2026 decisions
-
Capital allocation is shifting from acquisition cost to total cost of ownership (TCO). Energy, maintenance, footprint, and regulatory compliance now dominate lifecycle expenditure—our analysis quantifies these drivers across realistic deployment scenarios.
Ultra-low Temperature Freezers Market -
Regulatory and sustainability pressures are creating near-term technology adoption windows. Compliance with F-gas regulations, ENERGY STAR qualifications, and voluntary green standards is already influencing vendor road maps and purchasing specifications.
Ultra-low Temperature Freezers Market -
Operational risk management is becoming a board-level concern as sample value increases. The study surfaces failure modes, recovery-time requirements, and contingency architectures that materially change facility design and procurement strategies.
Macro dynamics shaping the market
The market's steady mid-single-digit CAGR reflects a blend of incremental demand from research and hospital sectors and periodic, technology-driven upgrades in high-density biobanking and industrial biomanufacturing. Key structural forces include:
-
Energy and sustainability mandates. Regulators and voluntary standards are accelerating retirements of inefficient units and privileging systems that use natural refrigerants or demonstrate demonstrable energy reductions.
-
Technology differentiation. Advances in compressor design, frequency-conversion motor control, Stirling engine alternatives, and AI-enabled remote management are creating product tiers with materially different operational economics.
-
Sample value densification. As sample collection and longitudinal biobanking grow, customers prioritize high-density storage, reliable recovery times, and minimized footprint over first-cost considerations.
Competitive landscape: who’s doing what
The ULT freezer market is moderately consolidated. The top three vendors account for a sizeable portion of market revenue while the top five capture a clear majority—indicative of a market where global scale, regulatory experience, and service networks confer advantage. Our report quantifies that concentration and unpacks the strategic implications for both buyers and smaller suppliers.
Leading suppliers demonstrate distinct positioning strategies:
-
Thermo Fisher Scientific (Waltham, MA): Focuses on energy-efficient platforms with integrated remote monitoring and predictive maintenance. Their recent TSX Core Series (March 2025) reinforces a platform approach—hardware, software, and service bundled to reduce lifecycle risk for research institutions and biopharma customers.
-
PHC Corporation (Tokyo): Emphasizes engineered sample preservation and energy efficiency in regulated lab environments, leveraging product families designed for controlled scientific workflows.
-
Eppendorf SE (Hamburg): Is moving toward compliance-friendly refrigerant options to meet EU F-gas regulations, an important differentiator for European procurement managers focused on long-term compliance risk.
-
Haier Biomedical (Qingdao): Competes on rapid recovery, extended hold times, and aggressive energy claims (recent UltraECO launch, May 2025). Its emphasis on AI-enabled asset management and frequency conversion technology targets large-scale biobanks and hospital networks.
-
Stirling Ultracold (Athens, OH) and Arctiko (Esbjerg): Advance Stirling engine-based and free-piston technologies that offer lower energy use and alternative thermodynamic architectures—relevant where electricity costs, emissions, or off-grid requirements influence buying decisions.
-
Helmer, BINDER, NuAire, So-Low: These vendors round out the market with regionally strong channels or specialty integrations (e.g., climate-chamber combos, clinical workflows), making them attractive partners for targeted deployments.
Recent product launches and regulatory developments—TSX Core Series, UltraECO’s energy claims, Eppendorf’s natural refrigerant variants, and ENERGY STAR qualifications for certain Stirling-based units—are not isolated product stories. Collectively, they signal a market tilt toward certified efficiency, refrigerant transition, and software-enabled uptime guarantees. Procurement teams should treat these not as incremental features but as decision-making thresholds: in many institutional settings, units without these attributes will face steeper operational penalties.
Operational and strategic implications for 2026
For enterprise leaders planning capital and operational budgets in 2026, the study distills several actionable recommendations:
-
Adopt a TCO-first procurement policy: Require vendor submissions to include lifetime energy models calibrated to local utility tariffs and duty cycles, remote monitoring capabilities, and realistic failure/recovery statistics. Our report includes TCO templates and sensitivity ranges you can apply directly.
-
Prioritize regulatory-aligned specifications: Specify refrigerant classes and energy certifications as minimums in RFPs. Early alignment reduces retrofit risk and capex write-downs as regional regulations evolve.
-
Design for resilience and sample value: Move from single-unit thinking to system thinking—integrate redundancy, remote alarm escalation, and documented recovery paths into procurement and service contracts. The report provides site-level risk matrices and contingency playbooks tailored to common facility types.
-
Use vendor scorecards and scenario-based sourcing: We include an operationally weighted vendor-scorecard framework (service responsiveness, certified energy performance, software maturity, spare-part lead times) to de-risk supplier selection and support dual-sourcing strategies.
-
Consider lifecycle partnerships: For high-value collections, capex can be replaced with performance-based contracts tying fees to uptime, temperature compliance, and energy intensity—an approach we model across several scenarios in the study.
What the full report delivers (practical components)
-
Market sizing and validated forecasts (2020–2032) with scenario analysis and sensitivity to energy-price volatility.
-
Vendor benchmarking and a downloadable vendor-scorecard template for procurement teams.
-
Operational playbooks: site-level TCO calculators, redundancy design checklists, and maintenance scheduling templates.
-
Regulatory and sustainability tracker: an annotated timeline of relevant regulations, certifications, and voluntary standards that affect procurement and disposal decisions.
-
M&A and competitive playbook: deal-screening criteria, valuation multipliers, and integration risks specific to ULT product portfolios and service networks.
-
Heat maps and buyer personas that synthesize where high-growth pockets and technical adoption pockets will be through 2032 (note: the report reserves detailed regional and segment percentages for subscribers).
How to use this study in practice — a 90-day playbook for 2026
-
Days 0–30: Run a portfolio audit using our site risk matrix. Identify critical assets and assign sample-value tiers.
-
Days 30–60: Issue an RFP based on the provided TCO template and vendor-scorecard; prioritize offers that include remote monitoring, energy certification, and lifecycle service commitments.
-
Days 60–90: Negotiate performance-based service terms (uptime SLAs, energy intensity guarantees), and align capex timing with the regulatory timeline to minimize retrofit risk.
Closing perspective
By 2026, strategic differentiation in the ULT freezer space will be determined less by catalog features and more by how vendors and buyers manage lifecycle economics, compliance risk, and operational resilience. PW Consulting’s study provides the data-driven foundation and playbooks necessary to translate market signals into defensible capital decisions. We deliberately present high-level market sizing and concentration metrics here to guide your initial thinking; the full report includes the granular segmentation, region- and application-level analyses, and the operational templates you will need to execute with confidence.
To access the complete dataset, detailed segment models, and the procurement-ready tools described above, consult the full Ultra-low Temperature Freezers Market report. The depth provided there is designed to transform 2026 budgeting and procurement cycles from reactive replacement to proactive, value-driven asset management.
For detailed analysis of this topic, please visit the official page: Ultra-low Temperature Freezers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Superhard Materials Market Set for a Steady 6.1% CAGR to 2032
By pmarketresearch, 2026-07-13
Superhard Materials Market 2026: Strategic Preview for Decision-Makers
Executive prologue
As global manufacturers, toolmakers, and advanced materials investors prepare to shape strategies in 2026, Superhard Materials sit at the intersection of industrial productivity, advanced manufacturing, and geopolitically sensitive supply chains. PW Consulting’s latest market study — grounded in a 2020–2025 historical base and forecasting across 2026–2032 with 2025 as the base year — quantifies a clear upward trajectory. The market expanded from roughly USD 4.25 billion in 2020 to about USD 5.72 billion in 2025, and under the base forecast continues to grow through 2032, supported by a mid-single-digit compound annual growth rate (CAGR) of 6.1% over the forecast period.
Super Hard Material (Superhard Materials) Market
This briefing is a strategic “trailer”: it surfaces the lines that matter for board-level choices in 2026 — competitive positioning, supply-chain resilience, regulatory playbooks, and technology differentiation — while deliberately reserving granular subsegment breakdowns for the full PW Consulting report.
Super Hard Material (Superhard Materials) Market
Why Superhard Materials matter in 2026
-
Operational leverage: Superhard materials (synthetic diamond, cubic boron nitride and related composites) remain critical enablers of productivity improvements in cutting, drilling and precision machining across automotive, aerospace, mining and semiconductor equipment supply chains. Marginal gains in tool life and cycle time translate directly to manufacturing cost and throughput advantages — a primary reason capital-intensive manufacturers continue to prioritize investment in these materials.
Super Hard Material (Superhard Materials) Market -
Technological front: Innovation in sintering, bonding, and novel superhard chemistries is opening application spaces (e.g., advanced composites machining, high-speed hybrid machining for electric vehicle components). Proprietary process know-how and IP-backed product platforms are becoming stronger differentiators than bulk production capacity alone.
-
Geopolitics and trade policy: Superhard materials are squarely in the crosshairs of trade-policy and national-security debates. Actions introduced in 2024–2025 have material implications for sourcing, pricing and the shape of global value chains — these dynamics will be a central variable in 2026 planning.
Market health and concentration — what boards must know
The market’s convex growth profile from 2020 through 2025 underlines resilience against cyclical headwinds. With the overall market value growing from approximately USD 4.25B to USD 5.72B in five years, the sector demonstrates steady demand pull. Our forecast continuity through 2032 shows the market moving towards roughly USD 8.66B under the baseline scenario, reflecting sustained industrialization, tool replacement cycles and incremental penetration into higher-value applications.
Market concentration is moderate-to-high: the top three firms capture a meaningful share of global supply, and the top five firms consolidate an even larger portion of the market. That structure shapes bargaining power, margins, and the speed at which technological shifts diffuse across the industry. For acquirers and incumbents, this concentration creates both barriers and opportunities — scale can protect margins, but nimble innovators can capture disproportionate growth in niche high-value segments.
Competitive landscape — key strategic profiles
-
Established Western technology leaders: Global engineering incumbents and specialty synthetic diamond firms continue to set the performance benchmark in high-value superabrasives for demanding industrial use-cases. Their strengths are R&D depth, established OEM relationships, and premium product positioning.
-
High-capacity Chinese manufacturers: Several large-scale producers provide breadth of product range and manufacturing scale. Their presence stabilizes global supply of standard grades and exerts downward pressure on commoditized pricing tiers, while simultaneously accelerating regional supply-chain localization.
-
Specialist mid-sized innovators: A cohort of companies focused on novel compositions (e.g., advanced metal borides and tetrides) and sintering technologies is emerging. These firms offer potential strategic partnerships for incumbents looking to access differentiated performance properties or to accelerate productization of lab-scale advances.
PW Consulting’s full report provides proprietary company profiles, capability maps and scenario-driven competitor scoring to guide M&A, supplier selection and co-development decisions. This briefing selectively highlights that the landscape mixes deep R&D players with high-volume manufacturers — a duality that should shape 2026 sourcing and alliance strategies.
Regulatory and trade dynamics — a 2026 decision risk map
-
Export controls and temporary suspensions: Since late 2024, several policy movements have introduced elevated uncertainty. Controls and notices originating from key producing jurisdictions have at times restricted exports of synthetic diamond materials and related manufacturing equipment, and subsequent administrative actions have created short-term suspensions and carve-outs. These oscillations materially affect lead times, contractual exposure and contingency inventories.
-
Import investigations and trade remedies: Investigations into processed critical minerals and adjacent inputs could lead to tariffs or anti-dumping measures. For firms dependent on cross-border sourcing, this introduces single-issue cost risk and compels a re-evaluation of nearshoring versus global sourcing economics.
-
Operational compliance: Beyond tariffs, dual-use and national security classifications can suddenly change the permissible use or destination of certain equipment and powders. Compliance programs, legal reviews and supplier audits must therefore be built into procurement cycles as a baseline operating expense, not an exception.
Strategic implications for 2026 planning
-
Scenario-driven supply-chain design: Firms should run at least three credible supply scenarios (baseline, constrained-export, and decoupled) that quantify sourcing cost, lead time, and inventory trade-offs over rolling 18–36 month horizons. PW Consulting’s scenario models allow you to stress-test supplier concentration, inventory levels, and price-shock sensitivity to guide inventory vs. just-in-time trade-offs.
-
Tiered supplier playbooks: Adopt a triage approach — preserve long-term relationships with high-technology, high-reliability suppliers; develop alternative sourcing from high-capacity manufacturers for commoditized grades; and engage with niche innovators on co-development contracts for differentiated applications. Structuring contractual flexibility (options, volume bands, escape clauses) will be essential in 2026.
-
Investment and M&A discipline: The market’s mid-single-digit CAGR masks pockets of high growth in specialty composites and engineered grades. Strategic acquisitions should be evaluated through capability-accretion lenses (IP, process control, customer access) rather than headline capacity gains alone.
-
Operational excellence and product premiuming: Incremental cycle-time improvements and tool-life extensions are monetizable. Pricing strategies should capture value for high-performance, certified grades while defending volumes in commoditized tiers through cost-to-serve optimization.
-
Regulatory engagement and policy hedging: Active engagement in standards-setting bodies and pre-emptive compliance investments can reduce disruption risk. Companies should map political exposure at supplier and country level and price potential policy shocks into long-term sourcing contracts.
What the PW Consulting report delivers (practical contents)
-
Robust market model: Annualized historical sizing (2020–2025) and a transparent forecast framework for 2026–2032, with scenario levers for policy shocks, technology adoption rates, and commodity price swings.
-
Actionable segmentation: Multi-dimensional segmentation by product architecture, application clusters and value-chain role with decision-grade implications (note: detailed segment-level tables and unit pricing are available in the full report).
-
Supply-chain maps and risk heatmaps: Geographical and capability overlays identifying single points of failure, latent capacity pockets, and logistics chokepoints.
-
Competitive benchmarking: Strategic profiles of leading firms, capabilities matrices, and partnership/competition scenario analyses to inform M&A targets and supplier selection.
-
Commercial playbooks: Pricing frameworks, commercial KPIs, inventory policies, and templates for supplier contracts that incorporate export-control milestones and force majeure triggers relevant to 2026 planning.
-
Technology roadmaps and IP posture assessments: Comparative analysis of process technologies (e.g., CVD, HPHT, metal-boride synthesis), patent landscapes and commercialization timelines.
Decision checklist for 2026
-
Have you stress-tested your sourcing network for a prolonged export-control scenario and quantified inventory carrying costs versus lost production risk?
-
Are your R&D investments aligned to applications where you can capture premium pricing rather than competing solely on material cost?
-
Do you have contractual flexibility with strategic suppliers that preserves access while enabling rapid reconfiguration if trade policy tightens?
-
Have you built an M&A thesis that prioritizes capability adjacency (process know-how, IP, customer channels) over scale alone?
Concluding guidance
The superhard materials market offers both steady, predictable growth and episodic disruption driven by policy shifts and technological inflection points. For 2026, executives must balance operational resilience with targeted investments in capability differentiation. The industry’s mid-single-digit CAGR and overall expansion through 2032 create a favourable backdrop for patient, strategic plays — but success will hinge on preparing for policy-induced volatility and capturing value through technology and commercial sophistication.
PW Consulting’s full Superhard Materials Market report contains the proprietary subsegment data, supplier scorecards, and downloadable scenario models that translate the insights above into executable 18–36 month plans. For firms planning capital allocation, sourcing realignment, or M&A in 2026, that level of detail is mission-critical.
For detailed analysis of this topic, please visit the official page: Super Hard Material (Superhard Materials) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Push-to-Talk Market to Grow at 11.33% CAGR Through 2032
By pmarketresearch, 2026-07-13
Push-To-Talk Market 2026: Strategic Imperatives for Enterprise Decision-Makers
As organizations accelerate digital transformation across frontline operations, the Push-To-Talk (PTT) market is re-emerging as a strategic communications layer — not merely a convenience but a mission-critical capability for safety, operational resilience, and real-time coordination. PW Consulting’s latest Push-To-Talk Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes commercial, technical, regulatory, and competitive signals to turn ambiguity into actionable strategy. The global market has more than trebled since 2020 and, with a projected compound annual growth rate of 11.33% over our 2026–2032 forecast window, is positioned for sustained expansion that will affect procurement, network planning, and security decisions in 2026 and beyond.
Push-To-Talk Market
Why this research matters to enterprises in 2026
-
Timing and leverage — 2026 is a hinge year. Spectrum reallocation proposals and national-level testing programs have reduced technical and regulatory uncertainty, creating a window for forward-looking organizations to lock in architecture choices that will last a decade.
Push-To-Talk Market -
Risk mitigation — PTT now sits at the intersection of public safety standards, carrier-grade networks, and cloud-native deployments. The report decodes the implications for continuity planning, SLA negotiation, and multi-vendor interoperability so you avoid costly rip-and-replace cycles.
Push-To-Talk Market -
Procurement efficiency — With a growing number of device classes (from rugged handhelds to smartphone-style MCPTT devices) and service models (cloud PTT, carrier-hosted PoC, dedicated emergency networks), procurement teams need a selection framework that balances cost, performance, and compliance. Our study provides that framework in operational terms.
Market trajectory and what the numbers signal
From a market sizing perspective, the Push-To-Talk ecosystem has shown consistent expansion through 2025 and is forecast to more than double by 2032. Our historical series shows an ascension from the low tens of millions in 2020 to USD 37.43 Million in 2025, followed by an accelerated climb to USD 79.34 Million by 2032. That trajectory — underpinned by an 11.33% CAGR across the forecast period — is not merely arithmetic: it reflects technology convergence (broadband PTT over LTE/5G), refreshed public safety priorities, and growing enterprise appetite for real-time coordination tools in logistics, utilities, transportation, and field services.
For decision-makers, the takeaways are clear: budget cycles and vendor engagements that begin in 2026 should assume a multi-year horizon where upgrade paths, interoperability, and lifecycle costs are central to ROI calculations.
What we cover — operational, procurement, and technical deliverables
The report is structured to be immediately actionable for enterprise teams and includes:
-
Strategic market map and TAM dynamics (historical 2020–2025 and scenario-based forecasts 2026–2032) to orient investment and product roadmaps.
-
Vendor selection framework with weighted criteria across reliability, security, integration, and supportability — enabling procurement to run objective RFP evaluations.
-
Device and network deployment playbooks covering rugged handsets, smartphone-style MCPTT devices, carrier-hosted PoC services, and private-network options.
-
TCO and lifecycle models capturing hardware, network subscription, integration, and operational costs under conservative and aggressive adoption scenarios.
-
Interoperability matrix and testing checklist aligned to recent government-led testing efforts to reduce cross-agency friction.
-
Security and compliance checklist that maps to DHS-authorized equipment requirements and recent regulatory guidance.
-
Scenario planning (spectrum shifts, carrier-first responder priorities, and 5G-enabled MCPTT rollouts) that helps leadership stress-test strategy choices.
Competitive landscape — who matters and why
The PTT market remains a mix of specialized device OEMs, software-first cloud players, and carrier-led services. Market concentration is moderate: the top three vendors account for approximately 45% of revenue and the top five about 55%. That structure creates both stability and opportunity — incumbent platforms provide mature capabilities and broad coverage, while a cohort of agile entrants focuses on cloud-native services, lower-cost hardware, or verticalized solutions.
-
Motorola Solutions: Continues to anchor the enterprise and public-safety end of the market with broadband PTT platforms and rugged devices. Their nationwide coverage, product breadth, and integration expertise make them a default choice for large agencies and enterprises with mission-critical requirements.
-
Hytera Communications: Focused on converged MCX/MCPTT systems and deeper integrations with 5G and AI capabilities. Their roadmap highlights the blurring line between traditional narrowband LMR and broadband PTT.
-
Zello and similar cloud-native players: Disrupting with app-first PTT over cellular and Wi‑Fi; they offer rapid deployment and low upfront cost but need to demonstrate parity on security, QoS, and device ruggedness for certain enterprise use cases.
-
Carrier and carrier-partnered solutions (AT&T FirstNet, Verizon Direct Connect, Diga-Talk+): These provide differentiated value around priority access, coverage guarantees, and enterprise SLAs — critical for public-safety adjacent deployments.
-
Rugged device specialists (Zebra, Sonim, Siyata, GLOBAL-PTT, Peak PTT, L3Harris): Compete on durability, battery performance, and field ergonomics. Their product cycles increasingly include 5G-capable and MCPTT-certified handsets to meet DHS and first-responder standards.
Recent product and policy moves in early 2026 underscore two dynamics: vendors are racing to certify and mass-produce rugged MCPTT-capable devices, and regulators are clarifying spectrum and interoperability expectations. For example, national-level testing programs and regulatory reviews of mid-band spectrum have accelerated vendor roadmaps and created clearer migration paths from legacy LMR systems to broadband PTT options.
Regulatory and standards context — operational impacts
-
Spectrum and access: Recent FCC activity has signaled flexible spectrum policy that supports broadband PTT and complementary services. Enterprises should anticipate evolving spectrum availability and incorporate spectrum risk into deployment plans.
-
Interoperability and testing: Government-led interoperability testing programs have produced standard test frameworks and product surveys. Buyers should insist on third-party testing evidence and interoperable APIs as part of procurement requirements.
-
Equipment standards and pricing: MCPTT-capable devices now span a wide price band, and procurement teams must match device TCO to use-case criticality. Durability, certified security features, and network compatibility are non-negotiable for mission-critical roles.
How to use this study in 2026 — three priority moves
-
Run a short-form interoperability audit across current voice and data stacks. Use the report’s interoperability matrix to identify immediate blockers and medium-term remediation needs.
-
Adopt a staged procurement strategy that balances immediate operational needs with a 3–7 year migration plan: pilot cloud PTT where agility is key; commit to carrier-backed or MCPTT-certified solutions for mission-critical operations.
-
Negotiate vendor contracts with forward compatibility clauses and clear performance SLAs across coverage, latency, and priority access — particularly where national emergency networks (or their commercial equivalents) will intersect with enterprise traffic.
Where the study intentionally withholds detail — and why
To preserve the strategic value of the full intelligence package and to ensure that enterprise engagements remain consultative rather than prescriptive, we present high-level market sizing, concentration metrics, and vendor positioning in this preview. Detailed regional and application-level segmentation, vendor scorecards with granular scoring, and modeled revenue splits are reserved for the full report and interactive datasets available on our research portal. This intentional restraint enables organizations to use our proprietary tools and recommendations in context-specific procurement and network-planning scenarios.
Concluding perspective
By 2032 the Push-To-Talk market will look materially different from the narrowband-dominated landscape of a decade prior: broadband PTT, MCPTT, and converged device portfolios will be the norm in both public-safety and enterprise settings. The 11.33% projected CAGR from 2026–2032 and the doubling of market size over the forecast period reflect not only vendor innovation but also shifting regulatory and operational imperatives. For enterprise leaders, the decision in 2026 is not whether to adopt PTT — it is how to adopt it in a way that preserves operational continuity, limits vendor lock-in, and captures the efficiency gains of real-time coordination.
PW Consulting’s full Push-To-Talk Market study provides the analytical depth, procurement tools, and scenario modeling required to make that decision with confidence. For enterprise teams preparing RFPs, planning pilots, or negotiating carrier contracts in 2026, this study converts market momentum into defensible, long-term choices.
For detailed analysis of this topic, please visit the official page: Push-To-Talk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organ-on-a-Chip Market to Soar to USD 509.7M by 2032 at 27.6% CAGR
By pmarketresearch, 2026-07-13
Organ-on-a-Chip Market: A 2026 Strategic Brief for Decision-Makers
As your trusted advisor at PW Consulting, this brief synthesizes the strategic implications of our latest Organ-on-a-Chip (OoC) market study to guide executive decisions in 2026. The sector is no longer an experimental sidebar of academic labs — it is entering a commercial and regulatory inflection that will reshape drug development, toxicology, and precision medicine supply chains. Below I summarize the macro trajectory, interpret competitive and regulatory dynamics, and translate those into actionable choices for pharmaceutical companies, platform providers, investors, and service organizations. The full report — with detailed segmentation, provider scorecards, benchmarking matrices, and primary-data appendices — is available on our site; this article is intended as a high-value executive “trailer” that demonstrates depth while leaving the granular data for the full dossier.
Organ-on-a-chip Market
Market trajectory: From niche tool to growth engine
Historically, organ-on-a-chip solutions moved from proof-of-concept demonstrations toward early commercial adoption between 2020 and 2025. Our base-year accounting shows the market expanding from roughly USD 46.5 million in 2020 to about USD 92.6 million in 2025, reflecting rapid adoption by pharmaceutical R&D, toxicology labs, and translational researchers. The forecast period (2026–2032) projects an annualized growth rate of approximately 27.6% (CAGR), bringing the global market to an estimated USD 509.7 million by 2032. That pace places OoC among the fastest-growing adjacent segments in preclinical technologies and positions it as a meaningful line item in biotech and pharma R&D budgets by the early 2030s.
Organ-on-a-chip Market
Two observations matter for strategy. First, the growth is both structural and regulatory — not merely cyclical. Second, while the aggregate market value remains numerically modest today, the velocity implies rapidly rising strategic importance for customers and suppliers: the platform winners in the next 18–36 months will secure durable commercial moats through regulatory validation, integration with automation/AI workflows, and deep customer co-development arrangements.
Organ-on-a-chip Market
Why 2026 is a decision point
- Regulatory acceleration: Recent regulatory signals have moved OoC from “promising” to “policy-relevant.” The FDA’s ISTAND pilot acceptance of organ-chip submissions for DILI prediction and its 2025 roadmap that explicitly names organ-on-a-chip as a New Approach Methodology (NAM) to reduce animal testing accelerate adoption as an accepted evidence source. This materially changes risk calculus for sponsors considering OoC validation investments.
- Commercial validation: Leading platforms are crossing critical validation thresholds — product launches, partnership announcements, and qualification milestones are clustering now, creating adoption windows for pharma partners and service providers to lock in preferred-vendor status.
- Market structure: The sector remains fragmented (low combined market share among the largest firms), creating opportunity for consolidation, vertical integration, and platform standardization plays. Careful timing of M&A or alliance activity in 2026–2027 can capture disproportionate value as the market consolidates around regulatory-recognized standards.
Competitive landscape: capabilities that matter
Our competitive analysis focuses on capability sets that will determine winners: regulatory engagement and qualification track record; validated biology and predictive performance for regulatory endpoints; automation and throughput; data interoperability and AI analytics; and commercial channel strength. Several providers exemplify differentiated strategic postures:
- Emulate, Inc. — A clear regulatory frontrunner with Organ-Chip systems across key tissues and a submission pathway in FDA ISTAND. Emulate’s emphasis on qualification and strategic pharma partnerships establishes it as the de facto benchmark for regulatory-minded adopters.
- MIMETAS B.V. — Built for throughput and integration, MIMETAS’s OrganoPlate approach appeals to high-throughput screening and automated workflows; their emphasis on scalability and analytics positions them for platform plays in early discovery and CRO integration.
- CN Bio Innovations — Focused on multi-organ and ADME/toxicity workflows, CN Bio has established traction with major pharmaceutical companies and is positioned as a partner for compound triage and pre-IND safety questions.
- InSphero AG — A hybrid model combining microtissues and chip formats with automation-ready solutions; strategic moves to expand phenotypic analysis and U.S. presence show a growth-oriented, acquisition-enabled playbook.
- TissUse GmbH and Hesperos, Inc. — Both emphasize multi-organ integrations and application diversity (from cosmetics to personalized medicine), making them attractive for cross-domain partnerships and translational applications beyond classic pharma endpoints.
Recent product launches, grants, and M&A events indicate momentum: new brain- and liver-focused devices, bioprinting modules for bespoke tissues, grant-funded personalized-medicine programs, and strategic acquisitions to enhance phenotypic analytics and geographic reach. Together, these moves compress the window for late movers to assemble credible competitive propositions.
Regulatory & standards environment: the force multiplier
The regulatory environment is the single most important externality shaping strategic choices. Two developments are particularly consequential. First, the FDA’s public roadmap and active ISTAND pathway (with specific organ-chip qualifications underway) create a path to partial substitution of animal tests in regulatory submissions. Second, European standardization efforts are converging toward shared technical requirements and interlaboratory validation roadmaps.
For commercial players, this means investments that directly support regulatory qualification (robust validation data sets, interlaboratory reproducibility studies, standardized protocols, and transparent performance claims) will be rewarded with faster, broader adoption. For pharma sponsors, early engagement with regulators to co-design validation strategies will reduce late-stage uncertainty and accelerate IND-enabling studies that incorporate OoC-derived evidence.
Strategic implications by stakeholder
- Pharmaceutical R&D leaders — Consider a staged adoption strategy: pilot OoC in high-value decision gates (e.g., DILI, cardiotoxicity) while negotiating collaborative validation agreements with platform providers. Allocate targeted funding to cross-validate OoC outputs against existing in vivo and in vitro assays to build internal confidence curves.
- Platform vendors — Prioritize regulatory engagement, data infrastructure, and automation partners. Establish “regulatory-ready” packages (protocols, validation dossiers, and user training) and pursue partnerships with CROs to scale market access rapidly.
- CROs and service labs — Build integrated OoC-as-a-service offerings with flexible pricing and guaranteed performance SLAs. Leverage comparative datasets to demonstrate cost and time advantages relative to conventional pathways.
- Investors and corporates — The fragmented market and rapid regulatory tailwinds create attractive roll-up opportunities and platform consolidation plays. Invest in companies with not only strong biology, but demonstrable regulatory strategy and data ecosystems.
- Regulators and standards bodies — Prioritize interlaboratory reproducibility studies and open-data repositories to accelerate mutual recognition and reduce duplication of validation effort across jurisdictions.
Operational playbook: practical steps for 2026
- Run controlled pilots that map OoC outputs to existing decision points and quantify impact on attrition, timelines, and cost-per-decision.
- Negotiate data-sharing and IP-lite collaboration agreements with platform providers to secure early access to validated models and co-development pathways for proprietary compounds.
- Invest in data infrastructure and standards adoption (common ontologies, metadata, and API-enabled integration) to future-proof output for regulatory submission packages.
- Perform scenario planning for regulatory acceleration (e.g., faster animal-test reduction timelines) and prepare contingency playbooks for rapid scale-up of OoC-generated evidence in INDs.
- Pursue targeted M&A or minority investments to secure critical capabilities (throughput automation, AI analytics, or specific tissue-model expertise).
What the full PW Consulting report contains
To support implementation, our full market study delivers an operational toolbox: a multi-year market model with revenue and unit forecasts (by product class and channel), segmentation maps, competitive scorecards and capability heatmaps, validated customer willingness-to-pay analyses, regulatory pathway mapping and recommended validation protocols, ROI and value-capture scenarios for strategic buyers, M&A playbooks with target archetypes, and primary-interview-based sentiment analysis from leading pharma, biotech, and regulatory stakeholders.
We deliberately limit disclosure in this executive brief to preserve the report’s role as a premium decision-support asset — especially the granular segmentation splits, proprietary vendor scores, and the detailed financial model. These are available in the full study and underpin the practical recommendations above.
Final read: timing, bets, and risk management
2026 is not a year to be passively observant. The combination of a steep CAGR (~27.6% through 2032), tangible regulatory progress, and active commercial validation means that strategic bets made now will determine leadership positions in the coming consolidation phase. The prudent portfolio approach blends (a) targeted pilots tied to business-critical decision gates, (b) strategic partnerships or minority investments in platform providers that demonstrate regulatory traction, and (c) internal capability development for data integration and cross-platform validation.
Risk management matters: device and biological variability, evolving regulatory expectations, and interoperability challenges remain. Mitigation requires reproducible protocols, cross-vendor benchmarking, and explicit regulatory engagement strategies. Firms that operationalize those mitigations — and move from exploratory pilots to validated decision-use cases — will convert market velocity into commercial advantage.
Next step
This brief outlines the strategic horizon and immediate choices for 2026. For the full evidence base, proprietary segmentation tables, scenario-modeled financial outcomes, and our tactical 90–180 day implementation playbook, please consult the PW Consulting Organ-on-a-Chip Market report on our website or contact your engagement lead to schedule a briefing. The granular data and vendor benchmarking contained in the full report are designed to convert insight into executable advantage — exactly the edge needed as this market accelerates from promise to practice.
For detailed analysis of this topic, please visit the official page: Organ-on-a-chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EMS & ODM Market to Reach USD 1,456.93 Billion by 2032 (7.62% CAGR)
By pmarketresearch, 2026-07-13
EMS and ODM Market 2026 Strategic Preview — PW Consulting
Executive preview: why this study matters for decisions made in 2026
As corporate leadership teams prepare budgets and strategic roadmaps for 2026, the electronics manufacturing services (EMS) and original design manufacturing (ODM) landscape will be a pivotal determinant of capital allocation, supply-chain architecture, and product roadmap timing. Our PW Consulting EMS & ODM Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies an industry that has expanded from roughly USD 603.6 billion in 2020 to about USD 871.3 billion in 2025, and is forecast to continue growing at a compound annual growth rate (CAGR) of 7.62% through the 2026–2032 window. By mid-decade, this growth is being driven less by incremental consumer product cycles and more by structural investments in AI infrastructure, industrial digitalization, and selectively accelerated reshoring initiatives.
EMS and ODM Market
Market trajectory and strategic inflection points
The high-level trajectory is instructive for boards and investment committees. Our base-year analysis (2025) captures a market that has re-accelerated following pandemic-era disruptions and is expected to approach the trillion-dollar threshold in the late-2020s as demand for high-performance computing, AI server platforms, and industrialized IoT manufacturing scales. The 7.62% CAGR built into our forecast embeds three durable dynamics that should inform 2026 decision-making:
EMS and ODM Market
- Technology-driven content inflation: Products built for AI, 5G/6G communications, and electrified mobility carry higher BOM (bill of materials) complexity and integration demands. This raises average selling prices for complex assemblies even when unit volume growth flattens.
- Geopolitical and trade-policy friction: Tariff adjustments and export-control regimes are changing where and how capacity can be economically expanded. The report models several realistic policy scenarios and their implications for sourcing cost and lead-time volatility.
- Supply-chain tightness and component scarcity: Extended lead times on critical components — for example, certain high-voltage power semiconductors — materially increase planning risk for multi-month production ramps. Our scenario analysis quantifies the revenue and timing sensitivity to component lead-time shocks.
What the report delivers — practical, board-ready outputs
The study is designed as an operational playbook, not an academic exercise. Executive teams will find the following actionable modules inside the full report:
EMS and ODM Market
- Market sizing and validated forecast models with alternative scenarios (baseline, accelerated AI investment, and trade-constrained) that translate macro demand into capacity requirements and revenue timing.
- Supply-chain stress tests and supplier-risk heatmaps that combine component lead-time data, trade-policy overlays, and geographic exposure to produce a prioritized list of supply vulnerabilities and mitigation levers.
- Commercial and contract playbooks: recommended procurement structures, pass-through clauses, and contingency pricing templates tailored for high-volatility components and long-lead assemblies.
- Facility and footprint decision support: capex vs. opex tradeoff models, labor-skill forecasts, and a location-risk index that folds regulatory constraints and export-control risk into site selection decisions.
- M&A and partnership intelligence: valuation ranges, capability-synergy frameworks, and a shortlist of candidate targets by capability cluster (server/HPC specialization, high-reliability medical/defense, consumer high-volume, etc.).
- Innovation and productization playbooks: design-for-manufacturability (DFM) levers for AI servers and power-dense systems, plus IP-governance recommendations for ODM collaborations.
Note: this article intentionally omits detailed segment-by-segment tables and granular regional/application percentages to preserve the full value of the primary models and datasets contained in the report. The full report includes those detailed splits and interactive models.
Competitive landscape: who matters and why
The EMS/ODM space remains fragmented relative to some other industrial markets: the top three and five players capture a minority share of global revenue (our CR3 and CR5 metrics are 25% and 29% respectively), leaving ample runway for both scale consolidation and differentiated niche strategies. From a strategic viewpoint, companies cluster into distinct value propositions:
- Scale-integrators with vertical scope (notably firms with large consumer-electronics ancestry) are rapidly pivoting toward AI infrastructure and high-volume server assembly. Their advantage is global manufacturing reach and capital access to fund large, integrated fabs and test lines.
- Specialists focused on compute infrastructure and HCI (high-compute infrastructure) bring deep co-engineering expertise; they are prime partners for OEMs that need speed-to-market for AI servers and edge-compute nodes.
- High-reliability niche EMS providers serve medical, aerospace, and defense applications where certification, traceability, and long-tail aftermarket support justify higher margins and differentiated barriers to entry.
Representative companies we profile in depth in the report (summary view):
- Foxconn Technology Group — the largest global integrator that continues to redeploy capital into AI server manufacturing and large-scale data-center components, including significant new investments in North American production capacity.
- Quanta Computer Inc., Wistron Corporation, Pegatron Corporation — Taiwanese incumbents that combine notebook/server heritage with accelerating server and communications manufacturing footprints; many are investing in co-design capabilities for AI applications.
- Wiwynn Corporation — a specialist positioning around AI servers, storage, and HPE-class infrastructure with design and system-integration strengths attractive to hyperscalers and cloud providers.
- Jabil, Flex, Celestica, Sanmina, Benchmark, Plexus — multinational EMS firms with differentiated vertical focuses (medical, industrial, automotive, aerospace/defense) and localized manufacturing footprints that reduce time-to-market for regulated products.
Our competitive chapter synthesizes recent corporate moves — for example, large-cap investments into AI server capacity, strategic partnerships for communications modules, and targeted product launches around high-performance server platforms — interpreting what these moves mean for partner selection, pricing power, and manufacturing lead times over 2026 and beyond.
Risk environment and key policy headwinds
Decision-making in 2026 must embed an elevated risk premium for trade and supply-side shocks. The report integrates current industry signals, including extended semiconductor lead times and new tariff measures that materially affect power-supply and memory cost lines. It also models the operational impact of export controls on advanced manufacturing equipment — a constraint that limits where capital-intensive capacity can be profitably deployed. Executives should treat these not as one-off events but as a new cadence of policy-driven uncertainty that will influence supply-chain design choices for the next 3–5 years.
Strategic playbook: five priority moves for 2026
Based on our analysis, leaders should consider the following near-term priorities:
- Recalibrate supplier segmentation: move from single-scorecard procurement to multi-dimensional supplier risk profiles that include export-control exposure, critical-component concentration, and surge-capacity performance.
- Invest selectively in co-engineering and DFM capabilities to lower BOM complexity and reduce reliance on scarce components by design substitution where technically feasible.
- Adopt flexible footprint strategies: balance near-shore capacity for critical, latency-sensitive products with low-cost offshore lines for volume items, and include contractual flexibility for capacity reallocation.
- Implement inventory and hedging playbooks for long-lead semiconductors and magnetics; pairing financial hedges with supplier consignment and collaborative forecasting reduces production-day risk.
- Pursue capability partnerships and minority stakes in strategic EMS/ODM providers to secure preferential capacity and control over product roadmaps in high-priority segments (AI servers, medical electronics, EV/charger subsystems).
Why PW Consulting’s dataset is decision-essential
Boards and strategy teams tell us they need market intelligence that goes beyond “who makes what.” They require linked models that translate demand scenarios into capacity needs, margin pressure points, and realistic timelines for product launches. Our report integrates primary interviews, supplier-level operating metrics, and component lead-time signals to create a decision-grade toolkit: scenario-capable forecasts, supplier-risk dashboards, and execution-oriented playbooks designed for procurement, manufacturing, and corporate development teams.
Next steps
This preview highlights the macro trajectory, strategic inflection points, and executive playbook derived from PW Consulting’s EMS & ODM Market Study. For detailed, segment-level forecasts, regional exposure matrices, supplier scorecards, and downloadable decision models (including the sensitivity matrices that demonstrate financial impact under alternative tariff and lead-time assumptions), consult the full report and interactive dashboard on our website. The granular inputs, which we intentionally hold back here to protect the actionable value of the models, are available through the report purchase or a tailored executive briefing.
Contact PW Consulting’s EMS & ODM practice to schedule a strategy session that aligns our modeling with your product roadmap, supplier network, and 2026 capital plans.
For detailed analysis of this topic, please visit the official page: EMS and ODM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Boehmite Market Poised for 6.98% CAGR to $344.79M by 2032
By pmarketresearch, 2026-07-13
Boehmite Market 2026 Strategic Outlook — PW Consulting
Executive snapshot
The boehmite market has moved from a niche industrial feedstock to a strategic raw material integral to electrification, advanced electronics, and specialty flame-retardant formulations. Our base-year analysis (2025) shows the global boehmite market reached approximately USD 215.0 Million, up from USD 163.15 Million in 2020. Under conservative-technology and demand assumptions, our forecast extends through 2032 with the market growing to roughly USD 344.79 Million, equivalent to a compound annual growth rate of about 6.98% during the 2026–2032 forecast window. That trajectory reflects durable structural demand from semiconductor wafer processing, lithium-ion battery separators and related EV supply chains, as well as steady uptake in high-performance polymer films and specialty catalysts.
Boehmite Market
Why this matters for 2026 corporate decision-making
-
Supply-chain strategy: Boehmite now sits at the intersection of materials security and product performance. Companies must choose between pursuing spot-market flexibility and securing long-term offtake with capacity owners that can deliver consistent high-purity grades.
Boehmite Market -
Capital allocation: Investors and corporate development teams need forward-looking demand curves and modular investment cases to decide whether to expand upstream alumina conversion, build in-house refining, or partner with specialty producers.
Boehmite Market -
Regulatory & sustainability risk: Certification (e.g., ASI) and trade policy (notably the EU’s Carbon Border Adjustment Mechanism) are already reshaping cost competitiveness and market access for alumina-derived materials.
-
Product differentiation: High-purity and nano-structured boehmite commands outsized strategic value where performance tolerances are tight—semiconductor and high-energy battery separators are primary examples.
What our Boehmite Market report delivers (practical, transaction-ready content)
-
Integrated demand model: A bottom-up demand model covering 2020–2025 historicals and 2026–2032 forecasts, broken out by type and end-use (high-purity, nano grades, film additives, catalysts) and linked to OEM roadmaps for batteries and semiconductors.
-
Supply & capacity map: Plant-level coverage for primary producers, current capacity, announced expansions, and near-term commissioning risk—enabling procurement teams to stress-test sourcing strategies.
-
Cost and margin toolkit: Unit cost curves, raw-material sensitivity dashboards (alumina, bauxite), and scenario outputs showing the P&L impact of feedstock swings, logistics constraints, and CBAM-style carbon adjustments.
-
Supplier scorecards & due diligence checklist: Comparative profiles across quality, certification (e.g., ASI), capacity flexibility, geographic footprint, and product-development capabilities—formatted for immediate use in RFPs and purchase negotiations.
-
Go-to-market playbooks: Playbooks for entrants and incumbents covering commercialization for battery-grade boehmite, partnerships with OEMs, and premiumization strategies for semiconductor-grade materials.
-
Transaction support materials: M&A heatmaps, diligence templates, and valuation sensitivity analyses for targets across the production and refining chain.
Competitive landscape — positioning and near-term moves
The boehmite ecosystem combines large chemical groups, regional specialists, and niche high-purity producers. The following concise assessments summarize the strategic posture of core players we track closely:
-
Sasol Limited (Johannesburg, South Africa) — Operates PURAL and CATAPAL lines with global distribution via regional subsidiaries. Sasol’s strength is in scalable production and integrated distribution; its FY25 production metrics indicate steady output and operational continuity across its established lines.
-
Nabaltec AG (Witten, Germany) — Focused on APYRAL AOH® products for flame retardants and battery separators. Nabaltec is executing targeted capacity expansion at Schwandorf (announced investment in 2025) to capture growth in Europe and electromobility value chains; its strategy marries specialty-grade chemistry with European supply security.
-
Chinese producers (Anhui Estone, CHALCO Shandong Advanced Material, Shandong Xinhai, Xuancheng Jingrui) — A cluster of vertically integrated and specialty producers is scaling both standard and nano/high-purity grades aimed at domestic EV and electronics markets. Several players emphasize quality upgrades and expanded capacity focused on battery separator applications.
-
Regional specialists (Dequenne, Osang, Silkem, Kawai Lime, Nippon Light Metal) — These firms supply differentiated boehmite grades—ranging from catalyst and ceramic niches to semiconductor-grade materials—often leveraging national supply chains and proprietary synthesis routes. Nippon Light Metal, in particular, is notable for leadership in high-purity alumina-derived boehmite for electronics across the Asia-Pacific region.
Collectively, these dynamics point to a market that is specialized and still relatively fragmented, where technical know-how, certification, and proximity to end-users drive premium positioning more than sheer scale alone.
Market dynamics and near-term risk signals
-
Raw-material backdrop: Feedstock volatility remains a key margin driver. Recent indicators include regional bauxite price dispersion and stability in global alumina pricing during 2025. Supply interruptions (e.g., export controls or logistical issues from major bauxite sources) can introduce short, sharp input-cost pressure.
-
Regulation and certification: ASI-style sustainability certifications are becoming de facto entry barriers for premium contracts. Similarly, trade measures such as the EU’s CBAM raise the economic cost of unmitigated carbon footprints on imported alumina-derived materials.
-
End-market velocity: Semiconductor capital cycles and EV penetration rates will create asymmetric demand pulses. Semiconductor fabs require ultra-consistent quality and traceability; battery manufacturers are increasing specifications for separator performance—both create windows for higher margin capture by compliant suppliers.
-
Consolidation potential: Given the market’s technical entry hurdles and increasing demand concentration in high-value verticals, we expect strategic M&A and alliance activity—especially where access to certification or proximity to OEMs can be acquired.
Strategic imperatives for 2026 — what companies should do now
-
Operationalize multi-supplier strategies: Qualify at least two suppliers across geographies for critical grades; include logistics lead-time and carbon-cost scenarios in procurement contracts.
-
Pursue certification and traceability: If you compete for premium OEM contracts, invest in ASI or equivalent process audits and supply-chain transparency capabilities—this is increasingly priced into contracts.
-
De-risk feedstock: Build alumina-benchmark sensitivity into product pricing and hedging programs; consider forward-buy programs or captive conversion for critical volumes.
-
Differentiate technically: For materials teams, prioritize R&D for nano-structured and ultra-high-purity routes that align with semiconductors and next-gen battery separators.
-
Use scenario-led capital allocation: Adopt the report’s scenario suite to evaluate plant additions, brownfield upgrades, or take-or-pay offtakes against downside demand cases and regulatory cost trajectories.
-
Scan for opportunistic M&A: Seek targets that provide certification, niche grades, or geographic access rather than only volume—these traits unlock pricing power in the medium term.
How to use the full PW Consulting Boehmite Market report
This briefing highlights the strategic options and risk contours we see for 2026. For procurement teams, strategic planners, and corporate development groups that require executable intelligence, the full report supplies the granular segmentation, plant-level capacity mapping, supplier scorecards, and interactive cost models you need to operationalize the recommendations above. We deliberately keep this note high-level to preserve the commercial value of the full datasets and modeling tools—accessing the complete report will provide the detailed splits, quantified scenarios, and transaction-ready materials necessary for immediate implementation.
Final note — timing matters
Boehmite occupies a unique role as both a performance enabler and a potential supply-chain choke point for several rapidly advancing industries. With the market expanding from roughly USD 215.0 Million in 2025 toward the mid-hundreds by 2032 at a near-7% CAGR, 2026 is a pivotal year to lock in supplier relationships, certify processes, and align capital projects with OEM roadmaps. PW Consulting’s Boehmite Market study is designed to move teams from awareness to action—equipping you to make defensible, data-driven choices in a market where material quality, sustainability credentials, and supply security determine strategic winners.
For detailed analysis of this topic, please visit the official page: Boehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Test & Burn-in Sockets Market to Reach USD 2.15 Billion in 2026 (6.05% CAGR)
By pmarketresearch, 2026-07-13
Test & Burn-in Sockets: Strategic Imperatives for 2026 Decision-Makers
Executive summary
The Test & Burn-in Sockets market stands at a strategic crossroad. After half a decade of steady recovery and modernization, PW Consulting’s new market study finds the global market size at roughly USD 2.06 billion in 2025 and forecasts expansion to about USD 2.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 6.05% across the 2026–2032 forecast window. Market concentration remains meaningful (CR3 ~48.6%, CR5 ~62.5%), yet pockets of specialization, technology differentiation, and regional manufacturing dynamics create fertile ground for both established suppliers and agile entrants.
Test & Burn-in Sockets Market
Why this study matters for 2026 strategic decisions
-
Time‑sensitive capital allocation. Memory and advanced compute cycles, testing capital refresh, and qualification programs will force OEMs and test houses to prioritize investments in socket technologies and supporting fixtures over the next 12–24 months. Strategic procurement and capex decisions made in 2026 will lock in costs and supplier relationships for the next five years; our study quantifies the market trajectory and provides the scenario analysis needed to de‑risk those choices.
Test & Burn-in Sockets Market -
Product roadmaps and packaging transitions. The rapid adoption of advanced packaging (chiplet integration, CPO, heterogeneous integration) is changing mechanical, thermal, and signal‑integrity requirements for sockets. The report synthesizes how these technology transitions map to test and burn‑in hardware requirements—critical intelligence for product management, validation teams, and test engineering leaders.
Test & Burn-in Sockets Market -
Supply‑chain and manufacturing resilience. The market’s mid‑to‑high concentration suggests supplier power in selected niches. For procurement and operations teams, the report’s supplier risk matrix and contingency scenarios are tactical tools to ensure continuity of high-volume burn‑in and test runs, especially under surges in demand for AI/HPC and memory modules.
Market trajectory: what the numbers imply (without giving every split)
The headline growth path—from roughly USD 2.06 billion in 2025 to about USD 2.8 billion by 2032 at ~6.05% CAGR—encapsulates three overlapping demand vectors:
-
Volume expansion from next‑generation memory and AI accelerator stacks that require high‑reliability burn‑in and high‑pin‑count test solutions.
-
Higher per‑unit content driven by advanced socket engineering (thermal control, fine‑pitch contact technology, multi‑site modular fixtures) that increase average selling prices and test complexity.
-
Replacement and lifecycle expenditure as qualification cycles tighten and the cost of field failures rises for cloud and edge providers, elevating burn‑in program spend.
While regional and application breakdowns drive tactical supplier selection, the macro picture is clear: incremental growth is real and predictable, but compound risks from packaging shifts and silicon performance requirements demand active strategic management.
Dynamics and technology inflection points
-
Advanced packaging as a disruptor: Industry fora from 2026 (e.g., TestConX sessions) have framed the testing challenge as “Burn‑In at the Inflection Point,” focusing on the interaction between chiplets, CPO, and production test. The upshot: sockets must evolve from passive carriers to active enablers of thermal control, signal integrity, and efficient multi‑site throughput.
-
Mechanical and thermal validation is now mainstream: Presentations at recent conferences emphasized methods for characterizing socket housing deflection and validating mechanical robustness at scale—topics that elevate supplier selection from “does it fit” to “does it preserve yield, SI, and lifetime.”
-
Materials and contact technologies: Elastomeric, pogo‑pin, and SPEC contact approaches coexist; choice depends on frequency, pitch, lifetime, and thermal cycling. Test houses will increasingly prioritize modular systems that allow rapid swap‑outs as device I/O geometries evolve.
-
High‑temperature and high‑current requirements: Defense, aerospace, and certain compute workloads continue to demand rugged, high‑temperature burn‑in solutions—an area where specialized suppliers remain differentiated.
Competitive landscape: reading the supplier map
Buyers face a diverse set of suppliers, ranging from global OEMs with broad portfolios to niche specialists. The market’s CR3/CR5 concentration statistics indicate that while a few suppliers command significant share, there remains enough fragmentation to enable targeted selection based on engineering fit and commercial terms.
-
Yamaichi Electronics (Tokyo) remains a go‑to for high‑density BGA/LGA and custom sockets, leveraging SPEC contact technology to serve AI/HPC and advanced packaging customers that demand signal integrity and high reliability.
-
Enplas (Nagano) is well positioned for high‑volume precision molded solutions—favored by memory and logic manufacturers that prioritize repeatability and injection‑molded cavity performance for throughput economies.
-
Smiths Interconnect (Plastronics) (London) offers modular, high‑temperature, high‑current designs and is often the supplier of choice for defense/aerospace and other sectors where environmental endurance is paramount.
-
Loranger International and Robson Technologies (both California) bring deep custom‑SKU portfolios and turnkey board integration services—valuable for test houses seeking quick time‑to‑market with bespoke QFN and board integration needs.
-
Regional specialists (e.g., LEENO , ISC , WinWay , Yokowo ) deliver optimized sockets for memory and high‑pin‑count packages emerging from East Asia’s manufacturing clusters—an important factor for procurement teams sourcing near fabs.
-
Electronics and materials conglomerates ( 3M , Eaton , Sensata ) bring scale, integrated thermal solutions, and robust contact technologies—options for customers seeking integrated thermal management or established supply reliability.
-
Spring probe and contact specialists ( Rika Denshi , Ironwood , Okins , Johnstech , Aries ) occupy critical niches where contact lifetime and high‑frequency performance are non‑negotiable.
For board‑level integrators and OEM test engineering groups, the choice of supplier will typically hinge on three axes: (1) mechanical and thermal validation capability, (2) contact technology and expected lifetime, and (3) speed of customization and supply continuity. Our report provides supplier scorecards and a matchup framework that lets buyers map those axes to their product portfolios and volume commitments.
Recent market signals and trade‑show intelligence
-
Trade shows in early to mid‑2026 have reinforced the narrative: companies such as Seiken, LSG, and Smiths Interconnect used TestConX and SWTest to highlight burn‑in and socket innovations, interposers, and probe solutions. These public signals point to suppliers prioritizing modularity, SI validation, and thermal control in their product roadmaps.
-
Conference sessions focused on “next‑generation test socket evaluation” and methods for characterizing large housing deflection indicate that cross‑industry testing standards and performance benchmarks are coalescing—an important trend for buyers planning multi‑vendor deployments or seeking to shorten qualification cycles.
What the PW Consulting report contains (high‑value, action‑oriented deliverables)
-
Market model and scenario forecasts (2020–2032) with base‑year calibration and three demand scenarios to support capex planning and procurement negotiation strategies.
-
Supplier scorecards and a capability matrix covering mechanical, thermal, SI, contact technology, customization lead times, and supply‑chain resilience—designed for rapid shortlisting.
-
Technical annexes: test methodologies, qualification protocols, and validation checklists for mechanical deflection, thermal cycling, and signal‑integrity acceptance criteria.
-
Commercial playbook: pricing benchmarks, total cost of test (TCoT) models, and procurement negotiation levers that reflect lifecycle, yield impact, and replacement cadence.
-
Strategic scenarios: implications of packaging shifts (chiplet/CPO), multi‑site burn‑in scaling strategies, and supplier consolidation or partnership playbooks.
-
M&A and investment heatmap: pockets of attractive consolidation, capability acquisition targets, and licensing considerations for contact and interposer IP.
Strategic implications and immediate actions for 2026
-
Reassess supplier qualification gates: tighten mechanical and thermal acceptance criteria in RFPs and include modularity and interchangeability clauses to mitigate rework when device form factors change.
-
Lock in multi‑year agreements for capacity where supplier exposure is constrained, but keep options for rapid technology swaps—use the report’s supplier risk scoring to prioritize partners.
-
Invest in in‑house validation capability for SI and thermal characterization to shorten qualification loops and reduce dependence on external labs during packaging inflection events.
-
Run a TCoT assessment across the product portfolio this year: higher per‑unit socket costs can be justified if they materially reduce field failure risk and improve throughput; our models show the breakpoints across common packaging scenarios.
Call to action
The 2026 decision window is narrow: procurement cycles, capital planning, and product qualification schedules converge this year for many semiconductor OEMs and test providers. PW Consulting’s full Test & Burn‑in Sockets Market report equips leaders with the market modeling, supplier evaluations, and technical frameworks necessary to make defensible, value‑creating choices. For the full segmented forecasts, supplier scorecards, and the technical annexes that underpin the strategic recommendations summarized here, please consult the complete report on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Test & Burn-in Sockets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
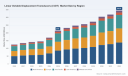
Linear Variable Displacement Transducers (LVDT) Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our comprehensive LVDT market research—designed to equip executives making strategic choices in 2026. This piece illustrates the research’s strategic value, highlights the inflection points shaping supplier and OEM strategies, and previews the kinds of actionable outputs included in the full study. In keeping with the “trailer” principle, we deliberately surface high-confidence, decision-relevant signals while withholding the granular segmentation tables and tactical data that are available in the full report.
Linear Variable Displacement Transducers (LVDT) Market
Why LVDTs matter to 2026 corporate strategy
LVDTs remain a foundational sensing technology across industrial automation, test & measurement, oil & gas, nuclear, aerospace, and transportation sectors. After a period of recovery and reinvestment, the LVDT market sits on a clear expansion path: our analysis uses a 2025 base and projects a multi-year CAGR of 6.98% through the 2026–2032 forecast window. The market moves from an estimated USD 215.0 Million in 2025 to a projected USD 232.44 Million in 2026, and continues to expand toward the mid-hundreds by 2032.
Linear Variable Displacement Transducers (LVDT) Market
For executives, this trajectory reframes priorities in three ways: (1) product roadmaps must balance legacy mechanical reliability with digital retrofit opportunities; (2) supply chain and raw-material resilience (stainless steels and specialty alloys among them) should be incorporated into medium-term sourcing plans; and (3) consolidation and targeted inorganic growth are attractive because market concentration remains low—leading three suppliers account for under one-fifth of revenue and the top five for less than one-third—leaving significant room for scale-driven margin improvement.
Linear Variable Displacement Transducers (LVDT) Market
What this study gives you—practical, transaction-grade outputs
- Executive playbook: concise, prioritized actions for product, commercial, and M&A teams calibrated to immediate 12–24 month windows and medium-term (3–5 year) bets.
- Financial runway models: revenue and margin scenarios that reflect demand shocks, raw-material volatility, and adoption curves for digital output retrofits.
- Competitive scorecards: qualitative and quantitative assessments of 12+ suppliers across technology, environmental robustness, certification, price competitiveness, and aftermarket capability.
- Customer journey and procurement maps: OEM and end-user buying criteria, total cost of ownership drivers, and switching frictions for retrofit vs. replacement decisions.
- Technology roadmaps and retrofit playbooks: when to invest in high-precision metrology-grade LVDTs versus ruggedized, large-bore, or radiation-resistant designs—and how to monetize signal conditioning and digitization services.
- Regulatory and compliance matrix: the practical implications of industry certifications and application-specific standards (including nuclear-grade and aerospace requirements) on time-to-market and cost.
- Supply-chain resilience plan: single-sourced components, alternative materials, and quality contingencies prioritized by risk exposure and commercial impact.
Market structure and strategic implications
The market’s growth profile—supporting mid-single-digit CAGR through the forecast horizon—reflects steady industrial demand and pockets of accelerated replacement or retrofit activity. Two structural features deserve immediate attention.
- Fragmentation as opportunity: Low market concentration creates an attractive environment for M&A that can accelerate scale, broaden product portfolios (e.g., large-bore or radiation-resistant offerings), and close gaps in regional distribution or aftermarket reach.
- Legacy installed base: A large installed population of legacy LVDTs drives recurring aftermarket and retrofit opportunities. Signal conditioners and digital-output adaptors that preserve mechanical sensors while enabling modern control systems represent a high-margin, low-capex pathway to recurring revenue—illustrated by recent product launches that provide digital outputs for existing sensors.
Competitive dynamics—who matters and why
The competitive landscape blends global OEMs with specialist, often regional, manufacturers. Each archetype creates different strategic moves for buyers, partners, and potential acquirers.
- Global diversified suppliers (e.g., large automation groups): bring product breadth, channel reach, and integration into larger sensing and control portfolios. They are preferred where one-stop sourcing, global field support, and broad product families are priorities.
- Precision metrology specialists: excel at sub-micron repeatability and are often chosen for laboratory, calibration, and high-value process-control applications. Their engineering depth and material choices (high-grade stainless bodies, for instance) matter when accuracy and long-term stability are mission-critical.
- Rugged- and environment-focused firms: supply large-bore, submersible, radiation-resistant, and high-temperature designs—positions that benefit from tailored engineering and certification capabilities rather than scale alone.
Representative firms in the study illustrate these archetypes. Honeywell combines broad product ranges and application depth suited to industrial and offshore environments. Solartron Metrology (part of a major instrumentation group) targets precision, research, and metrology markets with high-grade material choices and sub-micron repeatability. Niche players are innovating at the edges: NewTek Sensor Solutions has introduced large-bore and radiation-resistant LVDTs and delivered signal conditioners that modernize legacy installations; Stellar Technology and Active Sensors emphasize ruggedized and DIN-rail conditioned systems; Keyence and AMETEK-family brands supply high-precision sensors for automated measurement and test systems.
Our analysis cross-checks product specifications, recent product announcements, certification claims (ISO9001 and aerospace accreditations, for example), and field-use cases to produce supplier profiles that are practical for sourcing and partnership decisions.
Technology vectors shaping winners
- Digital retrofits and signal conditioning: Product introductions that bridge legacy analog LVDTs to digital control systems materially expand addressable serviceable markets and shorten sales cycles for upgrades.
- Specialized mechanical designs: Large-bore, radiation-tolerant, and high-temperature LVDTs open verticals (nuclear, downhole oil & gas, and aerospace) where suppliers can command premium pricing due to certification and engineering entry barriers.
- Material and manufacturing choices: Use of corrosion- and wear-resistant stainless steels and precision assembly directly correlates with lifecycle economics in harsh environments.
Regulatory and procurement signals for 2026
Regulatory posture and industry certification have become de facto procurement filters in regulated verticals. Recent supplier announcements about radiation-resistant products and explicit references to aerospace and quality certifications underline how compliance is now a commercial differentiator. Procurement teams should build compliance-ready RFQs and accelerate supplier pre-qualification to avoid multi-month delays in project timelines.
Actionable recommendations for decision-makers in 2026
- Rebalance R&D spend: allocate a tranche to digital-interface adaptation for legacy sensors and a tranche to specialty mechanical designs (large-bore, radiation-resistant). Both have differentiated payback timelines.
- Pursue tuck-in M&A: prioritize targets that provide certification assets, aftermarket distribution, or specialized product lines that your organization lacks—fragmentation makes bolt-on acquisitions accretive.
- Embed supply resilience: identify single-sourced components and create dual-sourcing plans, especially for critical stainless and alloy components used in harsh-environment designs.
- Monetize installed base: develop retrofit-as-a-service offerings that convert one-time sales into recurring revenue via digital signal conditioning and lifecycle services.
- Operationalize compliance: incorporate certification gates into new-product development and supplier selection to shorten qualification cycles in aerospace, nuclear, and oil & gas verticals.
What you won’t find in this preview and why that matters
This preview intentionally avoids publishing the granular regional and application-level splits, supplier-by-segment market shares, and detailed pricing matrices that are necessary for tactical procurement and transaction diligence. Those granular deliverables—along with interactive models, supplier scorecards, and primary-interview transcripts—are included in the full PW Consulting LVDT market report and are the kind of intelligence procurement, corporate development, and product leaders consistently use to justify capex, conclude supplier contracts, or price acquisitions.
Next steps
For teams preparing 2026 budgets, executing on product roadmaps, or evaluating M&A targets: the full report converts the strategic frames above into transaction-grade deliverables—financial models, prioritized target lists, sourcing playbooks, and a phased commercialization plan. If you want to convert the market’s 6.98% CAGR and other high-level signals into a defensible business case, the complete study is the required next step.
PW Consulting’s market model is grounded in cross-validated primary interviews, product-specification triangulation, and scenario-based forecasting. Our clients use it to compress due diligence timeframes, de-risk product launches, and identify the narrow paths to margin expansion in an otherwise fragmented market. Reach out to access the full study and the proprietary models that power the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Linear Variable Displacement Transducers (LVDT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com