

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Superhard Materials Market Set for a Steady 6.1% CAGR to 2032

Superhard Materials Market 2026: Strategic Preview for Decision-Makers
Executive prologue
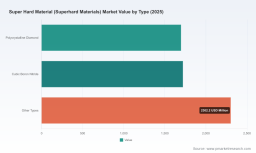
As global manufacturers, toolmakers, and advanced materials investors prepare to shape strategies in 2026, Superhard Materials sit at the intersection of industrial productivity, advanced manufacturing, and geopolitically sensitive supply chains. PW Consulting’s latest market study — grounded in a 2020–2025 historical base and forecasting across 2026–2032 with 2025 as the base year — quantifies a clear upward trajectory. The market expanded from roughly USD 4.25 billion in 2020 to about USD 5.72 billion in 2025, and under the base forecast continues to grow through 2032, supported by a mid-single-digit compound annual growth rate (CAGR) of 6.1% over the forecast period.
Super Hard Material (Superhard Materials) Market
This briefing is a strategic “trailer”: it surfaces the lines that matter for board-level choices in 2026 — competitive positioning, supply-chain resilience, regulatory playbooks, and technology differentiation — while deliberately reserving granular subsegment breakdowns for the full PW Consulting report.
Super Hard Material (Superhard Materials) Market
Why Superhard Materials matter in 2026
-
Operational leverage: Superhard materials (synthetic diamond, cubic boron nitride and related composites) remain critical enablers of productivity improvements in cutting, drilling and precision machining across automotive, aerospace, mining and semiconductor equipment supply chains. Marginal gains in tool life and cycle time translate directly to manufacturing cost and throughput advantages — a primary reason capital-intensive manufacturers continue to prioritize investment in these materials.
Super Hard Material (Superhard Materials) Market -
Technological front: Innovation in sintering, bonding, and novel superhard chemistries is opening application spaces (e.g., advanced composites machining, high-speed hybrid machining for electric vehicle components). Proprietary process know-how and IP-backed product platforms are becoming stronger differentiators than bulk production capacity alone.
-
Geopolitics and trade policy: Superhard materials are squarely in the crosshairs of trade-policy and national-security debates. Actions introduced in 2024–2025 have material implications for sourcing, pricing and the shape of global value chains — these dynamics will be a central variable in 2026 planning.
Market health and concentration — what boards must know
The market’s convex growth profile from 2020 through 2025 underlines resilience against cyclical headwinds. With the overall market value growing from approximately USD 4.25B to USD 5.72B in five years, the sector demonstrates steady demand pull. Our forecast continuity through 2032 shows the market moving towards roughly USD 8.66B under the baseline scenario, reflecting sustained industrialization, tool replacement cycles and incremental penetration into higher-value applications.
Market concentration is moderate-to-high: the top three firms capture a meaningful share of global supply, and the top five firms consolidate an even larger portion of the market. That structure shapes bargaining power, margins, and the speed at which technological shifts diffuse across the industry. For acquirers and incumbents, this concentration creates both barriers and opportunities — scale can protect margins, but nimble innovators can capture disproportionate growth in niche high-value segments.
Competitive landscape — key strategic profiles
-
Established Western technology leaders: Global engineering incumbents and specialty synthetic diamond firms continue to set the performance benchmark in high-value superabrasives for demanding industrial use-cases. Their strengths are R&D depth, established OEM relationships, and premium product positioning.
-
High-capacity Chinese manufacturers: Several large-scale producers provide breadth of product range and manufacturing scale. Their presence stabilizes global supply of standard grades and exerts downward pressure on commoditized pricing tiers, while simultaneously accelerating regional supply-chain localization.
-
Specialist mid-sized innovators: A cohort of companies focused on novel compositions (e.g., advanced metal borides and tetrides) and sintering technologies is emerging. These firms offer potential strategic partnerships for incumbents looking to access differentiated performance properties or to accelerate productization of lab-scale advances.
PW Consulting’s full report provides proprietary company profiles, capability maps and scenario-driven competitor scoring to guide M&A, supplier selection and co-development decisions. This briefing selectively highlights that the landscape mixes deep R&D players with high-volume manufacturers — a duality that should shape 2026 sourcing and alliance strategies.
Regulatory and trade dynamics — a 2026 decision risk map
-
Export controls and temporary suspensions: Since late 2024, several policy movements have introduced elevated uncertainty. Controls and notices originating from key producing jurisdictions have at times restricted exports of synthetic diamond materials and related manufacturing equipment, and subsequent administrative actions have created short-term suspensions and carve-outs. These oscillations materially affect lead times, contractual exposure and contingency inventories.
-
Import investigations and trade remedies: Investigations into processed critical minerals and adjacent inputs could lead to tariffs or anti-dumping measures. For firms dependent on cross-border sourcing, this introduces single-issue cost risk and compels a re-evaluation of nearshoring versus global sourcing economics.
-
Operational compliance: Beyond tariffs, dual-use and national security classifications can suddenly change the permissible use or destination of certain equipment and powders. Compliance programs, legal reviews and supplier audits must therefore be built into procurement cycles as a baseline operating expense, not an exception.
Strategic implications for 2026 planning
-
Scenario-driven supply-chain design: Firms should run at least three credible supply scenarios (baseline, constrained-export, and decoupled) that quantify sourcing cost, lead time, and inventory trade-offs over rolling 18–36 month horizons. PW Consulting’s scenario models allow you to stress-test supplier concentration, inventory levels, and price-shock sensitivity to guide inventory vs. just-in-time trade-offs.
-
Tiered supplier playbooks: Adopt a triage approach — preserve long-term relationships with high-technology, high-reliability suppliers; develop alternative sourcing from high-capacity manufacturers for commoditized grades; and engage with niche innovators on co-development contracts for differentiated applications. Structuring contractual flexibility (options, volume bands, escape clauses) will be essential in 2026.
-
Investment and M&A discipline: The market’s mid-single-digit CAGR masks pockets of high growth in specialty composites and engineered grades. Strategic acquisitions should be evaluated through capability-accretion lenses (IP, process control, customer access) rather than headline capacity gains alone.
-
Operational excellence and product premiuming: Incremental cycle-time improvements and tool-life extensions are monetizable. Pricing strategies should capture value for high-performance, certified grades while defending volumes in commoditized tiers through cost-to-serve optimization.
-
Regulatory engagement and policy hedging: Active engagement in standards-setting bodies and pre-emptive compliance investments can reduce disruption risk. Companies should map political exposure at supplier and country level and price potential policy shocks into long-term sourcing contracts.
What the PW Consulting report delivers (practical contents)
-
Robust market model: Annualized historical sizing (2020–2025) and a transparent forecast framework for 2026–2032, with scenario levers for policy shocks, technology adoption rates, and commodity price swings.
-
Actionable segmentation: Multi-dimensional segmentation by product architecture, application clusters and value-chain role with decision-grade implications (note: detailed segment-level tables and unit pricing are available in the full report).
-
Supply-chain maps and risk heatmaps: Geographical and capability overlays identifying single points of failure, latent capacity pockets, and logistics chokepoints.
-
Competitive benchmarking: Strategic profiles of leading firms, capabilities matrices, and partnership/competition scenario analyses to inform M&A targets and supplier selection.
-
Commercial playbooks: Pricing frameworks, commercial KPIs, inventory policies, and templates for supplier contracts that incorporate export-control milestones and force majeure triggers relevant to 2026 planning.
-
Technology roadmaps and IP posture assessments: Comparative analysis of process technologies (e.g., CVD, HPHT, metal-boride synthesis), patent landscapes and commercialization timelines.
Decision checklist for 2026
-
Have you stress-tested your sourcing network for a prolonged export-control scenario and quantified inventory carrying costs versus lost production risk?
-
Are your R&D investments aligned to applications where you can capture premium pricing rather than competing solely on material cost?
-
Do you have contractual flexibility with strategic suppliers that preserves access while enabling rapid reconfiguration if trade policy tightens?
-
Have you built an M&A thesis that prioritizes capability adjacency (process know-how, IP, customer channels) over scale alone?
Concluding guidance
The superhard materials market offers both steady, predictable growth and episodic disruption driven by policy shifts and technological inflection points. For 2026, executives must balance operational resilience with targeted investments in capability differentiation. The industry’s mid-single-digit CAGR and overall expansion through 2032 create a favourable backdrop for patient, strategic plays — but success will hinge on preparing for policy-induced volatility and capturing value through technology and commercial sophistication.
PW Consulting’s full Superhard Materials Market report contains the proprietary subsegment data, supplier scorecards, and downloadable scenario models that translate the insights above into executable 18–36 month plans. For firms planning capital allocation, sourcing realignment, or M&A in 2026, that level of detail is mission-critical.
For detailed analysis of this topic, please visit the official page: Super Hard Material (Superhard Materials) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com