

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Boehmite Market Poised for 6.98% CAGR to $344.79M by 2032

Boehmite Market 2026 Strategic Outlook — PW Consulting
Executive snapshot
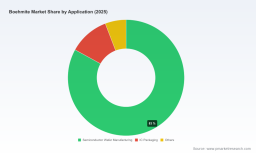
The boehmite market has moved from a niche industrial feedstock to a strategic raw material integral to electrification, advanced electronics, and specialty flame-retardant formulations. Our base-year analysis (2025) shows the global boehmite market reached approximately USD 215.0 Million, up from USD 163.15 Million in 2020. Under conservative-technology and demand assumptions, our forecast extends through 2032 with the market growing to roughly USD 344.79 Million, equivalent to a compound annual growth rate of about 6.98% during the 2026–2032 forecast window. That trajectory reflects durable structural demand from semiconductor wafer processing, lithium-ion battery separators and related EV supply chains, as well as steady uptake in high-performance polymer films and specialty catalysts.
Boehmite Market
Why this matters for 2026 corporate decision-making
-
Supply-chain strategy: Boehmite now sits at the intersection of materials security and product performance. Companies must choose between pursuing spot-market flexibility and securing long-term offtake with capacity owners that can deliver consistent high-purity grades.
Boehmite Market -
Capital allocation: Investors and corporate development teams need forward-looking demand curves and modular investment cases to decide whether to expand upstream alumina conversion, build in-house refining, or partner with specialty producers.
Boehmite Market -
Regulatory & sustainability risk: Certification (e.g., ASI) and trade policy (notably the EU’s Carbon Border Adjustment Mechanism) are already reshaping cost competitiveness and market access for alumina-derived materials.
-
Product differentiation: High-purity and nano-structured boehmite commands outsized strategic value where performance tolerances are tight—semiconductor and high-energy battery separators are primary examples.
What our Boehmite Market report delivers (practical, transaction-ready content)
-
Integrated demand model: A bottom-up demand model covering 2020–2025 historicals and 2026–2032 forecasts, broken out by type and end-use (high-purity, nano grades, film additives, catalysts) and linked to OEM roadmaps for batteries and semiconductors.
-
Supply & capacity map: Plant-level coverage for primary producers, current capacity, announced expansions, and near-term commissioning risk—enabling procurement teams to stress-test sourcing strategies.
-
Cost and margin toolkit: Unit cost curves, raw-material sensitivity dashboards (alumina, bauxite), and scenario outputs showing the P&L impact of feedstock swings, logistics constraints, and CBAM-style carbon adjustments.
-
Supplier scorecards & due diligence checklist: Comparative profiles across quality, certification (e.g., ASI), capacity flexibility, geographic footprint, and product-development capabilities—formatted for immediate use in RFPs and purchase negotiations.
-
Go-to-market playbooks: Playbooks for entrants and incumbents covering commercialization for battery-grade boehmite, partnerships with OEMs, and premiumization strategies for semiconductor-grade materials.
-
Transaction support materials: M&A heatmaps, diligence templates, and valuation sensitivity analyses for targets across the production and refining chain.
Competitive landscape — positioning and near-term moves
The boehmite ecosystem combines large chemical groups, regional specialists, and niche high-purity producers. The following concise assessments summarize the strategic posture of core players we track closely:
-
Sasol Limited (Johannesburg, South Africa) — Operates PURAL and CATAPAL lines with global distribution via regional subsidiaries. Sasol’s strength is in scalable production and integrated distribution; its FY25 production metrics indicate steady output and operational continuity across its established lines.
-
Nabaltec AG (Witten, Germany) — Focused on APYRAL AOH® products for flame retardants and battery separators. Nabaltec is executing targeted capacity expansion at Schwandorf (announced investment in 2025) to capture growth in Europe and electromobility value chains; its strategy marries specialty-grade chemistry with European supply security.
-
Chinese producers (Anhui Estone, CHALCO Shandong Advanced Material, Shandong Xinhai, Xuancheng Jingrui) — A cluster of vertically integrated and specialty producers is scaling both standard and nano/high-purity grades aimed at domestic EV and electronics markets. Several players emphasize quality upgrades and expanded capacity focused on battery separator applications.
-
Regional specialists (Dequenne, Osang, Silkem, Kawai Lime, Nippon Light Metal) — These firms supply differentiated boehmite grades—ranging from catalyst and ceramic niches to semiconductor-grade materials—often leveraging national supply chains and proprietary synthesis routes. Nippon Light Metal, in particular, is notable for leadership in high-purity alumina-derived boehmite for electronics across the Asia-Pacific region.
Collectively, these dynamics point to a market that is specialized and still relatively fragmented, where technical know-how, certification, and proximity to end-users drive premium positioning more than sheer scale alone.
Market dynamics and near-term risk signals
-
Raw-material backdrop: Feedstock volatility remains a key margin driver. Recent indicators include regional bauxite price dispersion and stability in global alumina pricing during 2025. Supply interruptions (e.g., export controls or logistical issues from major bauxite sources) can introduce short, sharp input-cost pressure.
-
Regulation and certification: ASI-style sustainability certifications are becoming de facto entry barriers for premium contracts. Similarly, trade measures such as the EU’s CBAM raise the economic cost of unmitigated carbon footprints on imported alumina-derived materials.
-
End-market velocity: Semiconductor capital cycles and EV penetration rates will create asymmetric demand pulses. Semiconductor fabs require ultra-consistent quality and traceability; battery manufacturers are increasing specifications for separator performance—both create windows for higher margin capture by compliant suppliers.
-
Consolidation potential: Given the market’s technical entry hurdles and increasing demand concentration in high-value verticals, we expect strategic M&A and alliance activity—especially where access to certification or proximity to OEMs can be acquired.
Strategic imperatives for 2026 — what companies should do now
-
Operationalize multi-supplier strategies: Qualify at least two suppliers across geographies for critical grades; include logistics lead-time and carbon-cost scenarios in procurement contracts.
-
Pursue certification and traceability: If you compete for premium OEM contracts, invest in ASI or equivalent process audits and supply-chain transparency capabilities—this is increasingly priced into contracts.
-
De-risk feedstock: Build alumina-benchmark sensitivity into product pricing and hedging programs; consider forward-buy programs or captive conversion for critical volumes.
-
Differentiate technically: For materials teams, prioritize R&D for nano-structured and ultra-high-purity routes that align with semiconductors and next-gen battery separators.
-
Use scenario-led capital allocation: Adopt the report’s scenario suite to evaluate plant additions, brownfield upgrades, or take-or-pay offtakes against downside demand cases and regulatory cost trajectories.
-
Scan for opportunistic M&A: Seek targets that provide certification, niche grades, or geographic access rather than only volume—these traits unlock pricing power in the medium term.
How to use the full PW Consulting Boehmite Market report
This briefing highlights the strategic options and risk contours we see for 2026. For procurement teams, strategic planners, and corporate development groups that require executable intelligence, the full report supplies the granular segmentation, plant-level capacity mapping, supplier scorecards, and interactive cost models you need to operationalize the recommendations above. We deliberately keep this note high-level to preserve the commercial value of the full datasets and modeling tools—accessing the complete report will provide the detailed splits, quantified scenarios, and transaction-ready materials necessary for immediate implementation.
Final note — timing matters
Boehmite occupies a unique role as both a performance enabler and a potential supply-chain choke point for several rapidly advancing industries. With the market expanding from roughly USD 215.0 Million in 2025 toward the mid-hundreds by 2032 at a near-7% CAGR, 2026 is a pivotal year to lock in supplier relationships, certify processes, and align capital projects with OEM roadmaps. PW Consulting’s Boehmite Market study is designed to move teams from awareness to action—equipping you to make defensible, data-driven choices in a market where material quality, sustainability credentials, and supply security determine strategic winners.
For detailed analysis of this topic, please visit the official page: Boehmite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com