

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Push-to-Talk Market to Grow at 11.33% CAGR Through 2032

Push-To-Talk Market 2026: Strategic Imperatives for Enterprise Decision-Makers
As organizations accelerate digital transformation across frontline operations, the Push-To-Talk (PTT) market is re-emerging as a strategic communications layer — not merely a convenience but a mission-critical capability for safety, operational resilience, and real-time coordination. PW Consulting’s latest Push-To-Talk Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes commercial, technical, regulatory, and competitive signals to turn ambiguity into actionable strategy. The global market has more than trebled since 2020 and, with a projected compound annual growth rate of 11.33% over our 2026–2032 forecast window, is positioned for sustained expansion that will affect procurement, network planning, and security decisions in 2026 and beyond.
Push-To-Talk Market
Why this research matters to enterprises in 2026
-
Timing and leverage — 2026 is a hinge year. Spectrum reallocation proposals and national-level testing programs have reduced technical and regulatory uncertainty, creating a window for forward-looking organizations to lock in architecture choices that will last a decade.
Push-To-Talk Market -
Risk mitigation — PTT now sits at the intersection of public safety standards, carrier-grade networks, and cloud-native deployments. The report decodes the implications for continuity planning, SLA negotiation, and multi-vendor interoperability so you avoid costly rip-and-replace cycles.
Push-To-Talk Market -
Procurement efficiency — With a growing number of device classes (from rugged handhelds to smartphone-style MCPTT devices) and service models (cloud PTT, carrier-hosted PoC, dedicated emergency networks), procurement teams need a selection framework that balances cost, performance, and compliance. Our study provides that framework in operational terms.
Market trajectory and what the numbers signal
From a market sizing perspective, the Push-To-Talk ecosystem has shown consistent expansion through 2025 and is forecast to more than double by 2032. Our historical series shows an ascension from the low tens of millions in 2020 to USD 37.43 Million in 2025, followed by an accelerated climb to USD 79.34 Million by 2032. That trajectory — underpinned by an 11.33% CAGR across the forecast period — is not merely arithmetic: it reflects technology convergence (broadband PTT over LTE/5G), refreshed public safety priorities, and growing enterprise appetite for real-time coordination tools in logistics, utilities, transportation, and field services.
For decision-makers, the takeaways are clear: budget cycles and vendor engagements that begin in 2026 should assume a multi-year horizon where upgrade paths, interoperability, and lifecycle costs are central to ROI calculations.
What we cover — operational, procurement, and technical deliverables
The report is structured to be immediately actionable for enterprise teams and includes:
-
Strategic market map and TAM dynamics (historical 2020–2025 and scenario-based forecasts 2026–2032) to orient investment and product roadmaps.
-
Vendor selection framework with weighted criteria across reliability, security, integration, and supportability — enabling procurement to run objective RFP evaluations.
-
Device and network deployment playbooks covering rugged handsets, smartphone-style MCPTT devices, carrier-hosted PoC services, and private-network options.
-
TCO and lifecycle models capturing hardware, network subscription, integration, and operational costs under conservative and aggressive adoption scenarios.
-
Interoperability matrix and testing checklist aligned to recent government-led testing efforts to reduce cross-agency friction.
-
Security and compliance checklist that maps to DHS-authorized equipment requirements and recent regulatory guidance.
-
Scenario planning (spectrum shifts, carrier-first responder priorities, and 5G-enabled MCPTT rollouts) that helps leadership stress-test strategy choices.
Competitive landscape — who matters and why
The PTT market remains a mix of specialized device OEMs, software-first cloud players, and carrier-led services. Market concentration is moderate: the top three vendors account for approximately 45% of revenue and the top five about 55%. That structure creates both stability and opportunity — incumbent platforms provide mature capabilities and broad coverage, while a cohort of agile entrants focuses on cloud-native services, lower-cost hardware, or verticalized solutions.
-
Motorola Solutions: Continues to anchor the enterprise and public-safety end of the market with broadband PTT platforms and rugged devices. Their nationwide coverage, product breadth, and integration expertise make them a default choice for large agencies and enterprises with mission-critical requirements.
-
Hytera Communications: Focused on converged MCX/MCPTT systems and deeper integrations with 5G and AI capabilities. Their roadmap highlights the blurring line between traditional narrowband LMR and broadband PTT.
-
Zello and similar cloud-native players: Disrupting with app-first PTT over cellular and Wi‑Fi; they offer rapid deployment and low upfront cost but need to demonstrate parity on security, QoS, and device ruggedness for certain enterprise use cases.
-
Carrier and carrier-partnered solutions (AT&T FirstNet, Verizon Direct Connect, Diga-Talk+): These provide differentiated value around priority access, coverage guarantees, and enterprise SLAs — critical for public-safety adjacent deployments.
-
Rugged device specialists (Zebra, Sonim, Siyata, GLOBAL-PTT, Peak PTT, L3Harris): Compete on durability, battery performance, and field ergonomics. Their product cycles increasingly include 5G-capable and MCPTT-certified handsets to meet DHS and first-responder standards.
Recent product and policy moves in early 2026 underscore two dynamics: vendors are racing to certify and mass-produce rugged MCPTT-capable devices, and regulators are clarifying spectrum and interoperability expectations. For example, national-level testing programs and regulatory reviews of mid-band spectrum have accelerated vendor roadmaps and created clearer migration paths from legacy LMR systems to broadband PTT options.
Regulatory and standards context — operational impacts
-
Spectrum and access: Recent FCC activity has signaled flexible spectrum policy that supports broadband PTT and complementary services. Enterprises should anticipate evolving spectrum availability and incorporate spectrum risk into deployment plans.
-
Interoperability and testing: Government-led interoperability testing programs have produced standard test frameworks and product surveys. Buyers should insist on third-party testing evidence and interoperable APIs as part of procurement requirements.
-
Equipment standards and pricing: MCPTT-capable devices now span a wide price band, and procurement teams must match device TCO to use-case criticality. Durability, certified security features, and network compatibility are non-negotiable for mission-critical roles.
How to use this study in 2026 — three priority moves
-
Run a short-form interoperability audit across current voice and data stacks. Use the report’s interoperability matrix to identify immediate blockers and medium-term remediation needs.
-
Adopt a staged procurement strategy that balances immediate operational needs with a 3–7 year migration plan: pilot cloud PTT where agility is key; commit to carrier-backed or MCPTT-certified solutions for mission-critical operations.
-
Negotiate vendor contracts with forward compatibility clauses and clear performance SLAs across coverage, latency, and priority access — particularly where national emergency networks (or their commercial equivalents) will intersect with enterprise traffic.
Where the study intentionally withholds detail — and why
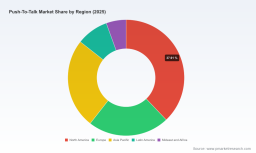
To preserve the strategic value of the full intelligence package and to ensure that enterprise engagements remain consultative rather than prescriptive, we present high-level market sizing, concentration metrics, and vendor positioning in this preview. Detailed regional and application-level segmentation, vendor scorecards with granular scoring, and modeled revenue splits are reserved for the full report and interactive datasets available on our research portal. This intentional restraint enables organizations to use our proprietary tools and recommendations in context-specific procurement and network-planning scenarios.
Concluding perspective
By 2032 the Push-To-Talk market will look materially different from the narrowband-dominated landscape of a decade prior: broadband PTT, MCPTT, and converged device portfolios will be the norm in both public-safety and enterprise settings. The 11.33% projected CAGR from 2026–2032 and the doubling of market size over the forecast period reflect not only vendor innovation but also shifting regulatory and operational imperatives. For enterprise leaders, the decision in 2026 is not whether to adopt PTT — it is how to adopt it in a way that preserves operational continuity, limits vendor lock-in, and captures the efficiency gains of real-time coordination.
PW Consulting’s full Push-To-Talk Market study provides the analytical depth, procurement tools, and scenario modeling required to make that decision with confidence. For enterprise teams preparing RFPs, planning pilots, or negotiating carrier contracts in 2026, this study converts market momentum into defensible, long-term choices.
For detailed analysis of this topic, please visit the official page: Push-To-Talk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com