

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ultra-low Temperature Freezers Market to grow at 5.1% CAGR through 2032

Ultra-low Temperature Freezers Market: Strategic Outlook for Enterprise Decision-Making in 2026
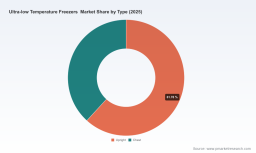
As laboratories, biobanks, and biopharma facilities accelerate sample-centric strategies, ultra-low temperature (ULT) freezers have moved from commodity infrastructure to mission-critical capital assets. PW Consulting’s latest market study — base year 2025, forecast period 2026–2032 — maps that transition with quantitative rigor and operationally focused guidance. The global ULT freezer market reached approximately USD 683.2 Million in 2025 and is projected to grow at a compound annual growth rate of 5.1% through the forecast window, reaching roughly USD 959.5 Million by 2032. This study is designed to inform the high-stakes procurement, R&D prioritization, site-planning, and M&A choices your organization will make in 2026.
Ultra-low Temperature Freezers Market
Why this study matters for 2026 decisions
-
Capital allocation is shifting from acquisition cost to total cost of ownership (TCO). Energy, maintenance, footprint, and regulatory compliance now dominate lifecycle expenditure—our analysis quantifies these drivers across realistic deployment scenarios.
Ultra-low Temperature Freezers Market -
Regulatory and sustainability pressures are creating near-term technology adoption windows. Compliance with F-gas regulations, ENERGY STAR qualifications, and voluntary green standards is already influencing vendor road maps and purchasing specifications.
Ultra-low Temperature Freezers Market -
Operational risk management is becoming a board-level concern as sample value increases. The study surfaces failure modes, recovery-time requirements, and contingency architectures that materially change facility design and procurement strategies.
Macro dynamics shaping the market
The market's steady mid-single-digit CAGR reflects a blend of incremental demand from research and hospital sectors and periodic, technology-driven upgrades in high-density biobanking and industrial biomanufacturing. Key structural forces include:
-
Energy and sustainability mandates. Regulators and voluntary standards are accelerating retirements of inefficient units and privileging systems that use natural refrigerants or demonstrate demonstrable energy reductions.
-
Technology differentiation. Advances in compressor design, frequency-conversion motor control, Stirling engine alternatives, and AI-enabled remote management are creating product tiers with materially different operational economics.
-
Sample value densification. As sample collection and longitudinal biobanking grow, customers prioritize high-density storage, reliable recovery times, and minimized footprint over first-cost considerations.
Competitive landscape: who’s doing what
The ULT freezer market is moderately consolidated. The top three vendors account for a sizeable portion of market revenue while the top five capture a clear majority—indicative of a market where global scale, regulatory experience, and service networks confer advantage. Our report quantifies that concentration and unpacks the strategic implications for both buyers and smaller suppliers.
Leading suppliers demonstrate distinct positioning strategies:
-
Thermo Fisher Scientific (Waltham, MA): Focuses on energy-efficient platforms with integrated remote monitoring and predictive maintenance. Their recent TSX Core Series (March 2025) reinforces a platform approach—hardware, software, and service bundled to reduce lifecycle risk for research institutions and biopharma customers.
-
PHC Corporation (Tokyo): Emphasizes engineered sample preservation and energy efficiency in regulated lab environments, leveraging product families designed for controlled scientific workflows.
-
Eppendorf SE (Hamburg): Is moving toward compliance-friendly refrigerant options to meet EU F-gas regulations, an important differentiator for European procurement managers focused on long-term compliance risk.
-
Haier Biomedical (Qingdao): Competes on rapid recovery, extended hold times, and aggressive energy claims (recent UltraECO launch, May 2025). Its emphasis on AI-enabled asset management and frequency conversion technology targets large-scale biobanks and hospital networks.
-
Stirling Ultracold (Athens, OH) and Arctiko (Esbjerg): Advance Stirling engine-based and free-piston technologies that offer lower energy use and alternative thermodynamic architectures—relevant where electricity costs, emissions, or off-grid requirements influence buying decisions.
-
Helmer, BINDER, NuAire, So-Low: These vendors round out the market with regionally strong channels or specialty integrations (e.g., climate-chamber combos, clinical workflows), making them attractive partners for targeted deployments.
Recent product launches and regulatory developments—TSX Core Series, UltraECO’s energy claims, Eppendorf’s natural refrigerant variants, and ENERGY STAR qualifications for certain Stirling-based units—are not isolated product stories. Collectively, they signal a market tilt toward certified efficiency, refrigerant transition, and software-enabled uptime guarantees. Procurement teams should treat these not as incremental features but as decision-making thresholds: in many institutional settings, units without these attributes will face steeper operational penalties.
Operational and strategic implications for 2026
For enterprise leaders planning capital and operational budgets in 2026, the study distills several actionable recommendations:
-
Adopt a TCO-first procurement policy: Require vendor submissions to include lifetime energy models calibrated to local utility tariffs and duty cycles, remote monitoring capabilities, and realistic failure/recovery statistics. Our report includes TCO templates and sensitivity ranges you can apply directly.
-
Prioritize regulatory-aligned specifications: Specify refrigerant classes and energy certifications as minimums in RFPs. Early alignment reduces retrofit risk and capex write-downs as regional regulations evolve.
-
Design for resilience and sample value: Move from single-unit thinking to system thinking—integrate redundancy, remote alarm escalation, and documented recovery paths into procurement and service contracts. The report provides site-level risk matrices and contingency playbooks tailored to common facility types.
-
Use vendor scorecards and scenario-based sourcing: We include an operationally weighted vendor-scorecard framework (service responsiveness, certified energy performance, software maturity, spare-part lead times) to de-risk supplier selection and support dual-sourcing strategies.
-
Consider lifecycle partnerships: For high-value collections, capex can be replaced with performance-based contracts tying fees to uptime, temperature compliance, and energy intensity—an approach we model across several scenarios in the study.
What the full report delivers (practical components)
-
Market sizing and validated forecasts (2020–2032) with scenario analysis and sensitivity to energy-price volatility.
-
Vendor benchmarking and a downloadable vendor-scorecard template for procurement teams.
-
Operational playbooks: site-level TCO calculators, redundancy design checklists, and maintenance scheduling templates.
-
Regulatory and sustainability tracker: an annotated timeline of relevant regulations, certifications, and voluntary standards that affect procurement and disposal decisions.
-
M&A and competitive playbook: deal-screening criteria, valuation multipliers, and integration risks specific to ULT product portfolios and service networks.
-
Heat maps and buyer personas that synthesize where high-growth pockets and technical adoption pockets will be through 2032 (note: the report reserves detailed regional and segment percentages for subscribers).
How to use this study in practice — a 90-day playbook for 2026
-
Days 0–30: Run a portfolio audit using our site risk matrix. Identify critical assets and assign sample-value tiers.
-
Days 30–60: Issue an RFP based on the provided TCO template and vendor-scorecard; prioritize offers that include remote monitoring, energy certification, and lifecycle service commitments.
-
Days 60–90: Negotiate performance-based service terms (uptime SLAs, energy intensity guarantees), and align capex timing with the regulatory timeline to minimize retrofit risk.
Closing perspective
By 2026, strategic differentiation in the ULT freezer space will be determined less by catalog features and more by how vendors and buyers manage lifecycle economics, compliance risk, and operational resilience. PW Consulting’s study provides the data-driven foundation and playbooks necessary to translate market signals into defensible capital decisions. We deliberately present high-level market sizing and concentration metrics here to guide your initial thinking; the full report includes the granular segmentation, region- and application-level analyses, and the operational templates you will need to execute with confidence.
To access the complete dataset, detailed segment models, and the procurement-ready tools described above, consult the full Ultra-low Temperature Freezers Market report. The depth provided there is designed to transform 2026 budgeting and procurement cycles from reactive replacement to proactive, value-driven asset management.
For detailed analysis of this topic, please visit the official page: Ultra-low Temperature Freezers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com